

Top Machine Learning Companies (2,927)
.png)
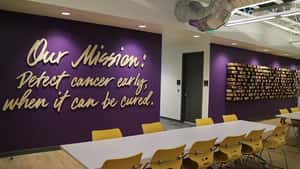
GRAIL is a healthcare company whose mission is to detect cancer early, when it can be cured. GRAIL is using the power of high-intensity sequencing, population-scale clinical studies, and state-of-the-art computer science and data science to enhance the scientific understanding of cancer biology, and to develop and commercialize pioneering products.
GRAIL's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising across 2025 and into 2026, with Galleri driving year-over-year increases and volumes outpacing revenue. Feedback suggests growth accelerated in early 2026 as test adoption broadened.
Strategic Partnerships: Partnerships such as Epic EHR integration and a collaboration with Samsung for Asia expansion are expanding distribution and market access. These relationships also support commercialization through employers, health systems and digital-health channels.
Investor Backing & Capital Strength: A sizable cash balance and recent equity financing provide a substantial runway to fund R&D and commercial expansion. This capital position helps buffer the costs of scaling while regulatory review proceeds.
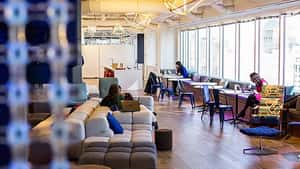
At Capital One, we think and work like a tech company, using our digital fluency to transform everything about the customer experience. We’re bending data to our will, and turning a stodgy industry on its head. That’s reflected in our ranking as the number one business technology innovator in the U.S. in the 2016 InformationWeek Elite 100.
Capital One's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate revenue increased year over year and sequentially, with quarterly revenue reaching roughly the mid‑teens in billions and full-year 2025 revenue rising markedly versus 2024. Earnings also improved in recent quarters alongside higher lending activity.
Market Expansion: The Discover acquisition expanded scale and added a proprietary payment network, with payment‑network volume increasing sharply as Capital One debit customers moved onto the Discover rails. Lending and purchase volumes also grew across cards, consumer banking, and auto, indicating broader reach.
Strong Market Position & Advantage: Capital One holds a leading position in U.S. credit cards and consumer banking, becoming the largest U.S. credit card issuer by balances after integrating Discover. This scale, combined with strong transaction activity, supports a durable competitive footprint.
Cox Enterprises is a family-owned enterprise spanning 125+ years of innovation. Through our diverse network of businesses, our people are shaping the future with bold thinking, cutting-edge technology and an unwavering commitment to doing what’s right. Across a range of industries — including automotive, agriculture, cleantech, journalism and more — we’re building a better future for this generation and the next....

Cox Enterprises's Top Stability & Growth Strengths
Diversified Revenue Streams: The portfolio spans automotive services, broadband, agriculture, media, cleantech, and venture investments, with new areas like Cox Outdoors added in 2025. Cumulative cleantech commitments above $3 billion and a second $300 million Socium Ventures fund further broaden where value can be created.
Innovation-Driven Growth: Technology-focused moves such as Cox Automotive’s acquisition of Fullpath add AI-enabled capabilities to dealer services. Investment activity in advanced recycling and greenhouse agriculture reflects ongoing bets on new technologies.
Market Expansion: Operating businesses are extending reach, from Cox Communications’ plans to serve more than 100,000 additional homes and businesses to Cox Farms’ 700+ greenhouse acres producing over 450 million pounds annually. The creation of Cox Outdoors introduces the company to additional consumer markets.
Mondelēz International, Inc. (NASDAQ: MDLZ) is an American multinational confectionery, food, and beverage company based in Illinois which employs approximately 90,000 individuals around the world. Our Purpose Our purpose is to empower people to snack right. We will lead the future of snacking around the world by offering the right snack, for the right moment, made the right way. Our...
Mondelēz International's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be on an upward trajectory, with sales increasing in 2025 and continuing to rise into the second quarter of 2026. Company updates also indicate an improved full-year outlook, pointing to sustained top-line momentum.
Market Expansion: Geographic performance is described as broad-based, with emerging markets such as Latin America and AMEA cited as key contributors alongside gains in North America. Independent reporting notes that growth is supported across multiple regions rather than a single market alone.
Strong Market Position & Advantage: Category leadership in biscuits and a top-tier position in chocolate, supported by globally recognized brands, are portrayed as competitive advantages. This scale and brand portfolio underpin international distribution across more than 150 countries, aiding growth.
PNC Bank is part of one of the largest diversified financial services institutions in the United States. With a coast-to-coast presence, PNC is organized around its customers and communities for strong relationships and local delivery of retail and business banking including a full range of lending products; specialized services for corporations and government entities, including corporate banking, real estate finance...
PNC Bank's Top Stability & Growth Strengths
Strong Revenue Growth: Year-over-year increases are evident, with 2025 revenue up about 7% and Q3 2026 revenue up roughly 11%, alongside record revenue reported in Q2 2026. Feedback suggests growth is supported by higher net interest income and fees with rising loans and deposits.
Profitability: Net income rose from about $6.0B in 2024 to $7.0B in 2025 and increased ~15% year over year in Q3 2026. Diluted EPS improved as well, indicating stronger earnings performance.
Market Expansion: Branch openings and a plan for 300+ new branches by 2030, combined with the FirstBank acquisition, expanded the footprint and lifted assets to roughly $616B by mid-2026. Raised 2026 guidance for loans, revenue, and net interest income points to continued scaling.
Nexthink is the global leader in digital employee experience management. Our platform empowers IT teams with real-time visibility, analytics, and automation to proactively detect and resolve issues across any application, device, or network—before they affect employees. By shifting IT from reactive problem-solving to continuous optimization, Nexthink enables more than 1,300 organizations to create productive, seamless, and satisfying digital workplaces for...

Nexthink's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have more than tripled between 2021 and 2025 while profitability improved. AI-related ARR also rose from $20 million in Q1 2025 to $109 million in Q1 2026, reinforcing momentum.
Market Expansion: Reported enterprise customers grew from 1,200+ in 2024 to 1,500+ in 2025, and platform reach expanded from 15 million to 25 million endpoints/employees. International moves, including plans for Japan and South America, indicate continued geographic expansion.
Investor Backing & Capital Strength: A majority investment by Vista Equity Partners at an approximately $3 billion valuation in 2025 signals strong external confidence. This transaction follows years of scaling and provides capital support for the next phase.
Ericsson builds the digital connectivity the world relies on. Our technology underpins the mobile networks, platforms, and systems that billions of people, businesses, and societies depend on every day. We are a global leader in communications technology, delivering mobile network infrastructure, cloud software, and wireless connectivity solutions for service providers and enterprises worldwide. Our networks support connectivity across 180+ countries, helping...

Ericsson's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests quarterly reported sales and organic growth have recently improved, led by the Networks business with 7% organic growth in Q3 2026 and a 6% increase in reported sales to SEK 59.5B. Underlying momentum is also visible year-to-date with 4% organic sales growth through September 2026 despite currency and portfolio effects.
Cost & Operational Efficiency: Feedback suggests margins and efficiency have seen progress, with adjusted gross margin near prior-year levels and prior-year improvements in adjusted EBITA and gross margin indicating disciplined execution. This operational resilience supports stability even when headline revenue is uneven.
Strong Market Position & Advantage: Feedback suggests Ericsson retains a strong competitive footing in mobile network infrastructure, with Networks as a clear growth engine across regions like Japan, India, Vietnam, and the Middle East. The company is viewed as a leading vendor in 5G RAN and core markets, underpinning demand durability.
Apptronik is building robots for the real world to improve human quality of life and to help solve the ever-increasing labor shortage problem. Our team has been building some of the most advanced robots on the planet for years, dating back to the DARPA Robotics Challenge. We apply our expertise across the full robotics stack to some of the most...

Apptronik's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Funding is described as exceeding $935 million in Series A with a $520 million extension and a reported multibillion-dollar valuation, which feedback suggests provides substantial resources for scaling production and deployments.
Strong Hiring & Retention: Headcount is portrayed as rising from about 150 to 350+ between late 2024 and mid-2026, and senior hires from major tech and robotics firms indicate a build-out for commercialization.
Strategic Partnerships: Collaborations with Mercedes-Benz, GXO Logistics, Jabil, and Google DeepMind are outlined, suggesting routes to industrial validation, manufacturing scale, and AI capability integration.

Smartling is an AI-native translation platform that's redefining how the world's biggest brands go global — ranked #3 on Fast Company's Most Innovative Companies list. We're growing rapidly at scale and are backed by Battery Ventures, a global technology-focused investment firm. While most companies are still figuring out how to use AI, we've spent years building it into the core...

Smartling's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor backing is underscored by a majority investment from Vitruvian Partners in 2026 with plans to expand AI capabilities, enter new markets, grow international presence, and pursue acquisitions. This signals access to growth capital and strategic support.
Strong Revenue Growth: Industry research characterizes the company as one of the fastest-growing in its space in 2025, indicating strong commercial momentum beyond internal announcements. This aligns with broader signals of scale such as an extensive customer base and large annual translation volume.
Innovation-Driven Growth: AI and AI-human translation usage increased markedly in 2025 alongside launches of new AI features like quality evaluation, translation automation, and agentic localization. These developments suggest product-led expansion and growing enterprise adoption.


LogicMonitor® is the AI-first hybrid observability platform powering the next generation of digital infrastructure. LogicMonitor delivers complete visibility and actionable intelligence across on-premises, cloud, and edge environments. By anticipating issues before they strike, optimizing resources in real time, and enabling faster, smarter decisions, LogicMonitor helps IT and business leaders protect margins, accelerate innovation, and deliver exceptional digital experiences without compromise....

LogicMonitor's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have progressed from more than $300 million in June 2025 to more than $400 million by May 2026, signaling clear top-line momentum. Growth among higher‑spend enterprise accounts is also highlighted as a key contributor.
Investor Backing & Capital Strength: An $800 million equity and strategic financing round at an approximately $2.4 billion valuation is described as providing substantial capacity to fund expansion. Ongoing sponsorship by the controlling shareholder is also noted.
Product Line Growth: AI-led offerings such as Edwin AI are described as contributing a significant share of bookings with very rapid recurring‑revenue growth. The Catchpoint acquisition further extended capabilities into internet performance and digital experience monitoring.
Upside is a technology company that increases the financial power of people and businesses in the real world. Our technology has helped millions of people get more purchasing power on the things they need, and tens of thousands of brick-and-mortar businesses earn measurable profit. Billions of dollars in commerce run through the Upside platform every year, and that value goes...
Upside's Top Stability & Growth Strengths
Market Expansion: Retailer participation expanded from over 50,000 locations in 2022 to about 100,000 by 2025, with 14,669 new locations added in 2025 and rollouts such as The Save Mart Companies’ nearly 200 stores. Feedback suggests consumer reach remains large at around 35 million, alongside substantial transaction and return-visit activity reported for 2025.
Strategic Partnerships: Partnerships and integrations with retailers and financial/tech platforms (e.g., Save Mart, Cary Oil expansion, Marqeta, Varo Bank, and distribution through Uber/Chime/Instacart) broaden access and deepen adoption. Feedback suggests existing partners are scaling usage and piloting new offer models, such as QuickChek’s fuel-offer approach.
Product Line Growth: Expansion beyond fuel into restaurants and grocery shows momentum, with reported year-over-year restaurant transaction gains and high volumes of grocery offers claimed monthly. Feedback suggests new product moves and category breadth (including hardware) are contributing to diversified growth.

Kustomer is the AI-native CX platform that helps companies move beyond reactive support and build customer experience around outcomes. By connecting customer data, workflows, knowledge, AI, and human agents in one system, Kustomer gives teams the context and control to deliver faster, more personal experiences and turn customer interactions into growth opportunities.
Kustomer's Top Stability & Growth Strengths
Investor Backing & Capital Strength: New funding of $60 million in 2023 and a $30 million Series B in August 2025, led by Norwest with participation from existing investors, indicates continued capital support. The company stated these funds will fuel AI innovation, integrations, and international expansion.
Innovation-Driven Growth: The launch of a standalone enterprise AI platform in March 2026, Kustomer Architect in May 2026, and additional Conversation Intelligence and AI QA capabilities in October 2026 point to active product development. These additions emphasize AI-powered customer service and broaden the platform’s capabilities.
Market Expansion: Introducing an AI platform that works with existing helpdesks (initially including Zendesk) extends reach beyond customers replacing their core systems. Expansion priorities also include international growth, as outlined alongside the 2025 financing.

Liftoff is a leading AI-powered performance marketing platform for the mobile app economy. Our end-to-end technology stack helps app marketers acquire and retain high-value users, while enabling publishers to maximize revenue across programmatic and direct demand. Liftoff’s solutions, including Accelerate, Direct, Monetize, Intelligence, and Vungle Exchange, support over 6,600 mobile businesses across 74 countries in sectors such as gaming, social, finance,...

Liftoff's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose about 35% year over year in Q2 2026 to roughly $219–$220 million, marking the eleventh consecutive quarter of growth. Management also guided full-year 2026 revenue to $870–$880 million, extending momentum after approximately 32% growth in 2025.
Healthy Cash Flow: Trailing twelve‑month operating cash flow increased about 90% to $237 million and free cash flow rose 142% to $184 million as of Q2 2026. These gains indicate that expanding revenue is converting into stronger cash generation.
Investor Backing & Capital Strength: The company completed a Nasdaq IPO in 2026 and previously secured a minority investment from General Atlantic at a multi‑billion‑dollar valuation. These milestones suggest strengthened access to capital alongside continued scaling of its advertising platform.

Deepgram is the leading voice AI platform for developers building speech-to-text (STT), text-to-speech (TTS) and full speech-to-speech (STS) offerings. 200,000+ developers build with Deepgram’s voice-native foundational models – accessed through APIs or as self-managed software – due to our unmatched accuracy, latency and pricing. Customers include software companies building voice products, co-sell partners working with large enterprises, and enterprises solving...

Deepgram's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue was described as doubling annually into 2025, with separate market analysis estimating roughly $100M in annualized revenue by mid-2026. The company also indicated it entered 2025 cash-flow positive, underscoring momentum in the business.
Investor Backing & Capital Strength: A $130 million Series C at a $1.3 billion valuation drew new strategic investors alongside existing backers, signaling deep capital support for scaling. Independent coverage also notes total funding exceeding $215 million, reinforcing financial flexibility for expansion.
Market Expansion: International reach expanded with plans for Europe and Asia and a Singapore regional hub, alongside reported strong growth in regional API demand. Product scope also widened from transcription into text-to-speech, real-time voice agents, and an industry entry via the OfOne acquisition.
.jpeg)
We are a world leader in innovative memory solutions that transform how the world uses information to enrich life for all. For over 45 years, our company has been instrumental to the world’s most significant technology advancements, delivering optimal memory and storage systems for a broad range of applications.

Micron Technology's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is surging, with fiscal 2026 reaching $133.19 billion and a record $54.23 billion in the fourth quarter, helped by AI-related demand, higher average selling prices, and strong bit shipment growth. Guidance near $61.5 billion for the next quarter indicates continued momentum.
Profitability: Profitability is expanding sharply, with fiscal 2026 net income at $84.97 billion and gross margin rising to roughly 81% for the year and about 87% in Q4. Higher average selling prices and strong data‑center demand are converting revenue growth into outsized earnings.
Future-Ready Strategy: Capacity expansion and multi‑year customer agreements are being ramped to meet sustained AI memory demand, including new fabrication plants and substantial forward commitments. Management also expects another record year, signaling confidence in the trajectory.

Space was once the quietest place in the universe. Now, it's crowded, contested, and confrontational. We are True Anomaly: the only defense company focused exclusively on space defense. Founded in 2022 by ex-U.S. Space Force members, True Anomaly designs and builds advanced systems for space superiority: agile and powerful spacecraft platforms, mission software engineered for unmatched command and control, and payloads...

True Anomaly's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $650 million Series D in April 2026 lifted total capital raised since 2022 to over $1 billion, with a reported $2.2 billion valuation. These resources are directed toward scaling manufacturing, missions, and hiring, signaling strong capacity to fund expansion.
Strong Hiring & Retention: Headcount moved from roughly 170 in April 2025 toward a stated goal of exceeding 500 by year-end 2026, with third-party estimates during 2026 supporting substantial growth. Hiring tied to facility buildout and a growing mission cadence indicates active team scaling across engineering and operations.
Market Expansion: Selections for additional U.S. Space Force programs in 2026—such as GHOST-R GEO reconnaissance, Kronos battle-management software, Andromeda, and space-based interceptors—indicate widening demand for Jackal spacecraft and Mosaic software. Manufacturing investment in Long Beach and a growing mission pipeline further point to increasing participation in national-security space.
.png)
Collectors has multiple business lines that grade, authenticate, and sell millions of high-value, record-setting collectibles. We're the leader in third-party authentication and grading services for high-value collectibles including trading cards (Professional Sports Authenticator and Card Ladder), coins (Professional Coin Grading Services), video games (Wata), event tickets, autographs, and memorabilia, and with your help we can continue to grow rapidly. Our...

Collectors's Top Stability & Growth Strengths
Strong Market Position & Advantage: PSA’s grading activity scaled to well over 19 million cards in 2025 and continued rising into 2026, while the portfolio also includes SGC and an agreement to add Beckett. This combination points to a commanding position in trading-card authentication and grading.
Market Expansion: New and expanded facilities in the U.S. and internationally, coupled with portfolio additions like the planned Beckett acquisition, extend geographic and category reach. Headcount has grown into the thousands with ongoing recruiting across functions.
Investor Backing & Capital Strength: A $200 million program was announced to expand PSA’s footprint, technology, and staffing over 18 months, alongside prior financing that valued the company in the billions. These commitments indicate ample capital available to scale capacity in response to rising demand.
Learneo is pioneering a platform of productivity and learning businesses. The platform of businesses includes CliffsNotes, the original and iconic study guide company; Course Hero, an online learning platform of academic resources; LanguageTool, a multilingual writing platform; LitCharts, a creator of literature resources; QuillBot, an AI-powered writing companion; Scribbr, a multilingual academic proofreading service; StudentBrands, a suite of supplemental learning...
Learneo's Top Stability & Growth Strengths
Product Line Growth: The portfolio expanded from one to six businesses over 24 months and then to eight with acquisitions such as LanguageTool and Barnes & Noble Education’s Digital Student Solutions (bartleby and Student Brands). This broadened coverage across AI writing, study resources, mathematics, and international markets.
Investor Backing & Capital Strength: A $395 million Series C financing at a reported $3.6 billion valuation, alongside multiple completed acquisitions, indicates substantial capital capacity. This financial position supports continued platform building, integration, and selective hiring.
Strong Revenue Growth: Recognition on the Inc. 5000 list in 2023 and 2024 points to meaningful multi-year revenue expansion. Company materials at the 2022 launch also cited more than $200 million in combined revenue and over 3 million annual subscriptions, demonstrating established scale.
.png)
mabl is the agentic testing harness that helps quality keep pace with AI-powered development. Combining specialized testing agents with deep application context, mabl continuously validates customer experiences, automates testing and maintenance, and brings trusted feedback directly into development. Trusted by industry leaders including Mercedes-Benz, LendingClub Bank, and JetBlue, mabl lets engineering teams move at the speed of the agentic development...

mabl's Top Stability & Growth Strengths
Strong Revenue Growth: Nearly 40% year-over-year ARR growth and a 55% increase in customers spending over $100,000 annually point to expanding recurring revenue and deeper enterprise penetration. The company also cites more than 25 Fortune 500 and nearly 50 Fortune Global 2000 organizations standardizing on its platform.
Market Expansion: Reported international momentum includes 178% growth in APAC and 52% in EMEA, indicating traction beyond the domestic market. These gains complement a rising count of large customers.
Innovation-Driven Growth: Rapid adoption of AI-powered capabilities—such as 700% growth in GenAI Test Assertions over five months and 240% year-over-year growth in GenAI Autoheal—suggests product-led expansion. API test executions rising 97% year over year, mobile test runs increasing sevenfold since April 2024, and more customers using multiple products reinforce this pattern.
CoreWeave, the AI Hyperscaler™, delivers a cloud platform of cutting-edge software powering the next wave of AI. The company's technology provides enterprises and leading AI labs with cloud solutions for accelerated computing. Since 2017, CoreWeave has operated a growing footprint of data centers across the US and Europe. CoreWeave was ranked as one of the TIME100 most influential companies and...

CoreWeave's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue expanded from roughly $1.9B in 2024 to $5.1B in 2025, with mid-2026 quarterly revenue still rising sharply. A very large revenue backlog of about $104B and additional net new commitments point to continued demand.
Strong Market Position & Advantage: The company is described as a leading specialist in AI-focused cloud infrastructure, supported by major contracts and third-party recognition. This advantage is reinforced by large-scale GPU capacity and adoption across AI labs, hyperscalers, and enterprises.
Strategic Partnerships: Relationships with NVIDIA and multiyear agreements with organizations such as Meta and Anthropic underpin access to advanced hardware and sizeable workloads. These alliances appear to support capacity build-out and commercial visibility.


Work Your Passion. Live Your Purpose.

