

Top Payments Companies (2,480)
At Capital One, we think and work like a tech company, using our digital fluency to transform everything about the customer experience. We’re bending data to our will, and turning a stodgy industry on its head. That’s reflected in our ranking as the number one business technology innovator in the U.S. in the 2016 InformationWeek Elite 100.
Capital One's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show total net revenue rising sharply—up 37% in 2025 and about 26% year over year in Q2 2026—while management described performance as reflecting solid top-line growth. Purchase volume also expanded materially, including a 27% increase in 2025 and strong gains into 2026.
Market Expansion: Scale expanded meaningfully with the May 2025 Discover acquisition, which added assets, deposits, loan portfolios, and payment-network capabilities. As of early 2026, reported assets of about $683 billion and deposits near $489 billion underscore the larger combined footprint, and external commentary anticipates further expansion.
Strong Market Position & Advantage: The company is identified as the largest U.S. credit-card issuer by outstanding balances as of year-end 2025 and one of the nation’s largest banks by deposits, with customer-satisfaction leadership among national banks. The addition of Discover’s network further reinforces a differentiated competitive position.
Since 2011, Remitly has been tirelessly delivering on our promises to our customers sending their hard earned money home. Today, we are incredibly proud to have served millions of customers globally. We strive daily to meet our promise to our customers by building peace of mind into everything we do. Join over 2,700 employees across 10 offices who are growing...
Remitly's Top Stability & Growth Strengths
Strong Revenue Growth: Recent disclosures show sustained top-line momentum, with quarterly revenue around $495M and full-year guidance raised to nearly $2B. This trajectory follows a prior year with revenue of about $1.64B and continued growth into 2026.
Profitability: Operating results highlight a shift to positive GAAP net income in 2025 and materially higher adjusted EBITDA in 2026. This indicates improving operating leverage alongside expansion in customers and send volume.
Product Line Growth: Offerings are expanding beyond core remittances with the Global Card, wallet features (including USDC capabilities), business remittances, and “Send Now, Pay Later.” These additions broaden the addressable market and create new monetization avenues.
Moov is a payments infrastructure platform making it easy to accept, store, send, and spend money all from a single, elegantly-designed API. Instead of stitching together multiple vendors, software companies simply add Moov to their products to get the latest in payment technology, user onboarding, licensing, compliance, and more.
Moov's Top Stability & Growth Strengths
Product Line Growth: Current materials show support for accepting payments, bank payments, wallets, issuing cards, payouts, account verification, and multiple rails including ACH, RTP, and FedNow, positioning the company as infrastructure rather than only a card processor. This broader workflow coverage can increase payment volume per customer and create more acquisition opportunities.
Strategic Partnerships: Recent announcements and legal documents reference collaborations with institutions such as Jack Henry, Visa Direct, Coinbase, SouthState Bank, and Veridian Credit Union. These relationships extend distribution into community and regional financial institutions and reinforce enterprise readiness.
Investor Backing & Capital Strength: The funding trajectory progressed from a $5.5M seed and $27M Series A in 2020 to a $45M Series B in 2023 led by Commerce Ventures with participation from Andreessen Horowitz, Bain Capital Ventures, and Visa. This pattern signals sustained access to capital aligned with scaling the business and infrastructure.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating income has risen materially alongside growth, with the latest quarter reporting meaningful GAAP and adjusted operating profits and expanding margins. This indicates the business is scaling while improving earnings quality.
Resilient & Sustainable Growth: Gross profit is expanding at a strong, accelerating pace, with both Cash App and Square contributing and management raising full‑year outlooks. Longer‑term disclosures also highlight multi‑year compounding in gross profit per user across ecosystems.
Cost & Operational Efficiency: A leaner organizational structure and disciplined spending have driven record adjusted operating margins and improved operating leverage. Efficiency gains appear to be a second engine alongside revenue drivers.

Adyen (ADYEN:AMS) is the financial technology platform of choice for leading companies. By providing end-to-end payments capabilities, data-driven insights, and financial products in a single global solution, Adyen helps businesses achieve their ambitions faster. With offices around the world, Adyen works with the likes of Meta, Uber, H&M, eBay, and Microsoft.
Adyen's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a sustained double‑digit pace across multiple periods, and management increased its constant‑currency growth outlook for 2026 after a strong first half. The company is also described as growing faster than the broader payments market by deepening share of wallet with major global merchants.
Profitability: Operating performance remains robust, with EBITDA expanding faster than revenue in 2025 and margins staying very high into 2026. This points to meaningful operating leverage alongside continued scale.
Product Line Growth: Expansion beyond core online payments is evident, with Unified Commerce and Platforms showing rapid gains and newer areas such as issuing, intelligent money movement, and agentic payments ramping. Recent acquisitions (e.g., loyalty and usage‑based billing) further broaden capabilities and potential revenue streams.
The Federal Reserve Bank of Chicago is one of 12 regional Reserve Banks across the United States that, together with the Board of Governors in Washington, D.C., serves as the nation's central bank. The role of the Federal Reserve System, since its establishment by an act of Congress in 1913 , is to foster a strong economy and a stable...
Federal Reserve Bank of Chicago's Top Stability & Growth Strengths
Strong Market Position & Advantage: As one of the 12 Reserve Banks with FOMC participation and nationally followed indices like CFNAI and NFCI, the institution maintains a prominent role in U.S. central banking and research. Materials also highlight influential convenings and system responsibilities that reinforce this position.
Product Line Growth: The introduction of the Chicago Fed Labor Market Indicators in September 2025 added a twice‑monthly data release with real‑time unemployment forecasts, hiring measures, and layoff/separation metrics. This expands recurring research/data offerings beyond maintaining existing outputs.
Resilient & Sustainable Growth: Operating evidence shows modest increases in expenses and compensation alongside continued publications, events, and regional analysis, indicating stable ongoing operations. Financial statements also note a larger 2025 balance sheet while the organization remains active across supervision, payments, and research.
Airwallex is the only unified payments and financial platform for global businesses. Powered by our unique combination of proprietary infrastructure and software, we empower over 250,000+ businesses worldwide – including Brex, Navan, Qantas, SHEIN, McLaren and many more – with fully integrated solutions to manage everything from business accounts, payments, spend management and treasury, to embedded finance at a global...
Airwallex's Top Stability & Growth Strengths
Strong Revenue Growth: Annualized revenue increased from $720M in March 2025 to $1.3B by March 2026, with ARR surpassing $1B in late 2025 and continuing upward. This trajectory points to sustained top-line momentum across the period cited.
Market Expansion: Geographic reach broadened with new regulated entries across multiple regions, alongside plans to deploy over $1B in the U.S. and substantial investment in Europe. Regional performance in the Americas and EMEA also advanced meaningfully, indicating traction beyond APAC.
Investor Backing & Capital Strength: Valuation rose from $6.2B (May 2025) to $11B (June 2026) through successive large funding rounds. Independent reporting corroborated the latest financing, signaling strong capital access and external confidence.
Wise is a global technology company, building the best way to move and manage the world's money. With Wise Account and Wise Business, people and businesses can hold 40 currencies, move money between countries and spend money abroad. Large companies and banks use Wise technology too; an entirely new network for the world's money. Launched in 2011, Wise is one...
Wise's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue increased 19% in FY2026 to about $2.5bn and rose a further 25% year over year to $714m in Q1 FY2027, indicating continued top-line momentum. Growth is broad-based alongside rising customers and cross-border volumes.
Profitability: Income before tax reached roughly $660m in FY2026, equating to a 26% margin while volumes and usage scaled. Profitability held even as the company reduced take rates to remain competitive.
Diversified Revenue Streams: Card spend grew 37% to ~$44bn and customer holdings rose ~40% to ~$39bn in FY2026, with card and other revenue also expanding, indicating monetization beyond transfer fees. Wise Platform partnerships with banks further extend revenue sources beyond direct consumer transfers.
Circle (NYSE: CRCL) is a global, internet financial platform company powering the foundation of an open, borderless, and programmable economy. Circle connects financial institutions, enterprises, and developers to the next generation of the internet financial system through digital assets such as USDC, Circle Payments Network for global money movement, and Arc, an enterprise-grade blockchain designed to become the Economic OS...

Circle's Top Stability & Growth Strengths
Profitability: Adjusted EBITDA more than doubled to $582M in FY2025 and increased again in Q2 2026, indicating improving operating earnings. Pay is considered strengthened further by FY2025 operating earnings outpacing revenue growth.
Diversified Revenue Streams: Other revenue grew 41% in Q2 2026, while the company is expanding payments, tokenized assets, the Circle Payments Network, and its Arc blockchain. Feedback suggests this reflects progress beyond a single revenue source.
Strong Market Position & Advantage: USDC circulation and usage continued to rise (e.g., $73.3B in Q2 2026, +19% YoY; $14.8T on-chain volume, +151% YoY), alongside growth in meaningful wallets. These adoption signals reinforce standing among the largest stablecoin networks.

Flywire is a global payments enablement and software company. We combine our proprietary global payments network, next-gen payments platform and vertical-specific software to deliver the most important and complex payments for our clients and their customers.
Flywire's Top Stability & Growth Strengths
Strong Revenue Growth: Recent filings and earnings updates indicate sustained double-digit increases across annual and quarterly revenue, with momentum continuing into 2026. Guidance was raised during the year, reinforcing ongoing top-line expansion across core verticals.
Profitability: Results point to improving earnings quality, including a shift to positive net income on an annual basis and expanding adjusted EBITDA margins. Management also signaled further margin gains in 2026.
Customer Loyalty & Retention: Disclosures highlight a growing client base alongside net dollar-based retention that indicates expansion within existing customers. Wins across education, travel, healthcare, and B2B suggest durable relationships that support recurring growth.
Riskified (NYSE:RSKD) empowers businesses to unleash ecommerce growth by outsmarting risk. Many of the world’s biggest brands and publicly traded companies selling online rely on Riskified for guaranteed protection against chargebacks, to fight fraud and policy abuse at scale, and to improve customer retention. Developed and managed by the largest team of ecommerce risk analysts, data scientists and researchers, Riskified’s...
Riskified's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue accelerated in 2026, with Q2 delivering the fastest quarterly growth in more than four years and first-half revenue above the prior year. Management raised full-year 2026 revenue guidance after Q2.
Healthy Cash Flow: Operations generated positive free cash flow in Q2 and the first half, and the company ended June 2026 with roughly $223.6M in cash and no debt. Adjusted EBITDA also improved year over year.
Product Line Growth: Customers are adopting additional products and certain verticals (Digital Finance and Tickets & Travel) showed particularly strong momentum. Management highlighted rising multiproduct usage alongside core transaction-risk offerings.
Squarespace is a design-driven platform helping entrepreneurs build brands and businesses online. We empower millions of customers in more than 200 countries and territories with all the tools they need to create an online presence, build an audience, monetize, and scale their business.
Squarespace's Top Stability & Growth Strengths
Strong Revenue Growth: Financial disclosures show 2023 revenue up 17% to $1.012 billion, and annual run-rate revenue up 20% year over year to $1.1795 billion in 2024. This indicates sustained top-line momentum going into the take-private.
Product Line Growth: New offerings such as Squarespace Capital (2025) and Squarespace Balance (March 2026) expand the business from website creation into payments, financing, and business financial services. A 2025 partnership integrating capabilities into Perplexity’s Comet browser further broadens the product ecosystem.
Investor Backing & Capital Strength: The October 2024 take-private by Permira at approximately $7.2 billion explicitly aimed to support expansion and product development. This transaction underscores access to capital and sponsor support for continued scaling.
Initially built to take the pain out of peer-to-peer payments, Cash App has gone from a simple product with a single purpose to a dynamic app, bringing a better way to send, spend, invest, borrow and save to our millions of monthly active users. With a mission to redefine the world's relationship with money by making it more relatable, instantly...

Cash App's Top Stability & Growth Strengths
Profitability: Cash App gross profit has risen strongly over multiple periods, with momentum attributed to growth in Borrow, BNPL products, and the Cash App Card. Company communications indicate continued year-over-year expansion that has supported raised outlooks.
Diversified Revenue Streams: Multiple monetization pillars—consumer lending, card spend/commerce enablement, banking features, and payments—are contributing to growth, while Bitcoin-related revenue has relatively little impact on gross profit. Excluding Bitcoin, segment net revenue growth has been materially stronger, and per-active monetization has increased.
Strong Market Position & Advantage: The platform has built a very large transacting active base and ranks near the top of U.S. finance app downloads, supporting scale-driven advantages. Engagement indicators such as inflows per active and primary banking adoption have increased, signaling deepening usage.

Possible Finance is on a mission to make financial health possible for everyone. We build products for the millions of Americans who live paycheck to paycheck, face unpredictable income, or can't get a fair shot from traditional banks and credit systems — people who are routinely ignored or penalized by mainstream financial institutions. That's why our products are designed differently. We...

Possible Finance's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have risen from 2024 to 2025, with an annualized run rate later surpassing the $125–$130 million range. This momentum is highlighted alongside increases in customer usage and overall scale.
Profitability: The company achieved its first annual net profit (around $3 million), indicating healthier unit economics and improving financial stability. This marks a shift from earlier periods focused on rebuilding.
Market Expansion: Operations expanded into 19 new states in 2025, bringing total coverage to roughly 33–34 states. New offerings such as Possible Advance further extended product reach and addressable market.
Genius AI is building technology to help local businesses run themselves. Genius AI products do the admin work that keeps practitioners from the work they love and the people they serve. From Genius AI to Reception, its products work 24/7 on busywork like booking, marketing, client management, finances, staff and inventory management, and more. Genius AI technology has saved businesses 106M...

Genius AI's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor backing is highlighted by a Series D round at a $1.15B valuation with total capital raised above $125M. This later-stage financing, led by established firms, indicates strong external confidence and resources for expansion.
Strong Revenue Growth: Revenue momentum is described as approaching a $200M annual run-rate alongside significant payment volumes facilitated through the platform. Coupled with scale to 125,000+ businesses, this points to meaningful commercial expansion.
Market Expansion: The company rebranded from GlossGenius to Genius AI to extend beyond beauty/wellness into the broader in-person service economy. New AI agents such as Growth Analyst and Reception demonstrate a widening product and market scope.
Justworks is a cloud-based software platform that takes the busyness out of growing a business and alleviates the unknown. We've combined a simple platform and exceptional 24/7 customer service to help entrepreneurs and businesses grow with confidence by giving them access to corporate-level benefits, automated payroll, HR tools, and compliance support— all in one place.
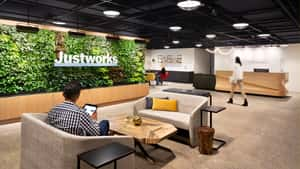
Justworks's Top Stability & Growth Strengths
Strong Revenue Growth: Company statements describe being on track for higher net revenue, and earlier filings documented substantial year-over-year expansion. Additional references point to rising contribution metrics over recent years.
Customer Loyalty & Retention: Company updates highlight record-high satisfaction and retention alongside a recent step-up in new-customer signups. These signals point to a stable, expanding customer base.
Product Line Growth: The business continues broadening its offering beyond core PEO into payroll, benefits, HR tools, and international employment, described under a “One Justworks” strategy. New capabilities and partnerships indicate ongoing investment in breadth.
Waystar harnesses the power of agentic AI, generative AI, and advanced automation to drive meaningful outcomes so providers reach peak financial performance and patients receive care with confidence. The Waystar platform is used by more than 1 million providers and supports over 60% of the U.S. patient population - and integrates with all major HIS and practice management systems. The financial and...
Waystar's Top Stability & Growth Strengths
Strong Revenue Growth: Reported revenue has been rising at a double‑digit pace across fiscal 2025 and the first half of 2026, with both Q1 and Q2 showing solid year‑over‑year increases. Management also raised full‑year 2026 revenue guidance, indicating confidence in continued expansion.
Profitability: Profitability is strong, with adjusted EBITDA growing year over year and margins holding in the low‑40s through fiscal 2025 and recent quarters. The company also reported positive net income and healthy cash generation.
Customer Loyalty & Retention: Net revenue retention remained expansionary and the number of larger clients increased year over year. Subscription revenue grew faster than total revenue in recent periods, suggesting deeper adoption within the existing base.
Flex, an NYC-headquartered FinTech company, has created a trusted rent payment experience. It’s hard to believe that it’s 2024 and paying rent on time is expensive, inflexible, and difficult; we’re here to change that! We enable our users to pay rent throughout the month on a schedule that better fits their finances and budget, while also helping them build credit....
Flex's Top Stability & Growth Strengths
Strong Revenue Growth: Flex Ltd. reported Q1 FY2027 net sales up 21% year over year with FY2026 up 8%, and management guided to further top-line increases. The rent-fintech at getflex.com also cites a tripling of annualized revenue alongside surpassing $10B in annualized payment volume.
Strategic Partnerships: Integrations with RealPage, Yardi, MRI, AppFolio, Entrata, Rent Manager, and Zego, plus a distribution tie-in with Apartment List, embed flexible payments within core property workflows. One announcement highlights selection as a preferred flexible rent technology within RealPage, extending reach across millions of rental units.
Investor Backing & Capital Strength: The rent-fintech reports back-to-back rounds—a $60M Series B followed by a $70M Series B1—bringing total equity funding near $180M and a valuation around $1.2B. These raises accompany disclosures of rapidly scaling revenues and payments volume.
Current is a U.S. based consumer fintech and payments platform with over four million members and a mission to improve financial outcomes. It provides mobile banking services that give its members access to opportunities to improve their financial lives, such as paychecks up to two days early, up to 4% APY, fee-free overdraft, money management tools and insights, fee-free ATMs,...
Current's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as rising at a very strong pace for multiple consecutive years, including a major surge in 2024. This sustained momentum indicates meaningful top-line expansion while advancing toward profitability.
Investor Backing & Capital Strength: Financing activity includes a late-stage equity round and substantial cumulative funding alongside expanded facilities. These signals point to continued access to capital that supports scaling credit and liquidity products.
Product Line Growth: Offerings have broadened beyond core banking into paycheck advances, fee-free overdraft, credit building, savings, teen accounts, and crypto. This expansion suggests more monetization paths and deeper engagement per customer.
At Affirm, we help people say yes to the things that matter with flexible, transparent ways to pay over time. No hidden fees, no compound interest, and no fine print—just a smarter way to spend.

Affirm's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose from $3.22B to $4.26B year over year, with recent quarters also showing solid double‑digit increases. Growth accompanied expanding GMV and usage, indicating breadth rather than a one‑off spike.
Profitability: Operating income turned from a loss to a meaningful profit in FY2026, and margins improved on both the full year and the most recent quarter. The company also reported record profitability and positive cash generation.
Product Line Growth: Affirm Card scaled rapidly, with active cardholders more than doubling and card GMV surging, increasing its share of total transactions. Direct‑to‑consumer products, including the Card, are cited as key drivers of GMV growth.


Work Your Passion. Live Your Purpose.

