

Top Hardware Companies (3,098)
Mondelēz International, Inc. (NASDAQ: MDLZ) is an American multinational confectionery, food, and beverage company based in Illinois which employs approximately 90,000 individuals around the world. Our Purpose Our purpose is to empower people to snack right. We will lead the future of snacking around the world by offering the right snack, for the right moment, made the right way. Our...
Mondelēz International's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue increased year over year in the latest full year, with organic sales also up, and subsequent quarterly updates continued to show growth. Emerging markets contributed more than developed markets, helping sustain the top line.
Healthy Cash Flow: The company consistently generates multi‑billion‑dollar free cash flow and has continued dividends and share repurchases. This supports financial flexibility to invest and return capital despite cost headwinds.
Strong Market Position & Advantage: The business holds leadership positions in core categories (global leader in biscuits and a top‑two player in chocolate) backed by iconic brands and worldwide reach. Such scale and category strength support resilience across regions and channels.
.png)
We bridge deep tech into farming and ranching. Halter enables farmers and ranchers to remotely shift, virtually fence and proactively monitor their cows’ health and behavior. Can you imagine watching 500 cows or cattle walk calmly towards the milking shed or their next break? No quad bikes, no dogs, no fences. Just a herd of cows walking at their own...
Halter's Top Stability & Growth Strengths
Market Expansion: Geographic reach is widening quickly, with operations scaling across many U.S. states and stated plans to enter the U.K. and Ireland alongside continued growth in New Zealand and Australia. Customer adoption also broadened materially, with notable increases in the number of ranches and farms using the platform.
Investor Backing & Capital Strength: Capital access strengthened through sizable late‑stage rounds at markedly higher valuations within a short span, with independent confirmations of the most recent raise. This trajectory indicates strong investor confidence to fund continued commercial and product expansion.
Strong Revenue Growth: New Zealand filings and reporting indicate materially higher subscription and segment revenues over recent periods. These financial signals align with increased collar deployments and a larger installed base.
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased 10% in 2025 and 9% in H1 2026, with leadership upgrading 2026 guidance to 8–10% sales growth. Growth was reported across all major sectors.
Profitability: Underlying EBIT rose 12% in 2025 and 11% in H1 2026, alongside an improved return on sales. This points to stronger margins in addition to top-line expansion.
Resilient & Sustainable Growth: A record order backlog of roughly £83.6–84.0 billion and multi‑year contracts provide substantial future revenue visibility. The 2026 outlook also signals continued expansion.

REPAY is a full-service payment technology and processing provider that enables the expedient and secure collection of payments through any channel at any time. Our omnichannel payment platform provides direct integration with enterprise management systems and access to a suite of payment solutions, including credit/debit card processing, ACH processing, Instant Funding, IVR/phone pay, text pay, electronic bill payment and presentment...
REPAY's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show clear acceleration, with reported revenue rising strongly and organic growth remaining positive, while late‑2025 normalized trends also improved. Management’s outlook indicates continued growth through 2026.
Market Expansion: Scale and reach expanded meaningfully through the KUBRA acquisition, adding breadth across bill‑payment verticals and materially increasing overall platform activity. Distribution indicators such as software relationships and the AP supplier network also grew markedly.
Healthy Cash Flow: Cash generation is solid, highlighted by substantial free cash flow and strong conversion in the latest quarter. Adjusted profitability also improved alongside the expanding revenue base.
McMaster-Carr is trusted by industrial customers around the world to keep manufacturing lines running, operations moving, and turn new ideas into real products. Since 1901, we’ve earned that trust by offering the right products, making them easy to find, and delivering them quickly. Our industry-leading e-commerce experience, indispensable product selection, and world-class service bring hundreds of thousands of customers to our...

McMaster-Carr's Top Stability & Growth Strengths
Market Expansion: Public records and reporting indicate a major new regional headquarters and distribution center in Fort Worth, adding a sixth U.S. node to existing facilities in Illinois, Georgia, Ohio, California, and New Jersey. Additional buildouts at sites like Elmhurst and other regional renewals point to a broader, expanding nationwide footprint.
Innovation-Driven Growth: Project filings describe substantial automation investments at the Texas facility—high-bay racking, tote-shuttle systems, and conveyors—alongside hiring for reliability/automation roles. These moves signal scaling capacity with technology to support same- and next-day fulfillment.
Strong Market Position & Advantage: Industry coverage places the company near the top of MRO/industrial distributor rankings and highlights standout catalog breadth and rapid fulfillment. Company descriptions also cite serving hundreds of thousands of daily customers, indicating strong competitive presence.

At Revel, we are revolutionizing the way the world’s most critical hardware is controlled—across aerospace, automotive, energy, and manufacturing sectors. Our next-generation software stack combines an intuitive command/control interface, a specialized programming language tailored for hardware control, and a high-performance runtime environment. We empower engineers to build, test, and deploy critical systems rapidly, reliably, and safely.

Revel's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor appetite appears strong, with a $150M Series B in February 2026 reportedly valuing the company around $1B and providing substantial runway to scale. The rapid step-up from earlier funding suggests ample capital to expand product and go-to-market.
Market Expansion: Expansion beyond an initial aerospace testing niche into defense, robotics, nuclear, oil & gas, water, power, data centers, and biomedical manufacturing is underway. This broadening footprint indicates movement toward a larger addressable market across multiple industries.
Customer Loyalty & Retention: Conversion of pilots into paying customers and deepening within accounts—such as 80+ RevelTest instances at Impulse Space and a defense contractor scaling from 0 to 25 deployments in two months—signal strong adoption and stickiness. Named customers across advanced hardware companies reinforce ongoing usage.
.png)
We’re the manufacturing partner of choice that helps a diverse customer base design and build products that improve the world. We love to hear your thoughts, comments and ideas so feel free to like, share and comment away. Any question or opinion is good to go as long as it is respectful and falls within the scope of this page. Derogatory...
Flex's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is depicted as rising at Flex Ltd. with accelerating quarterly momentum, while the fintech platforms report sharp increases in transaction volumes and revenue. These patterns indicate solid topline traction across the brands operating under the Flex name.
Investor Backing & Capital Strength: The AI-native banking platform expanded its capital base through multiple funding rounds and achieved unicorn valuation, signaling ample resources to scale. This capital position underpins continued product development and international expansion.
Strategic Partnerships: The rent-payments platform has embedded integrations with major property management systems such as RealPage, Entrata, AppFolio, Yardi, and Apartment List, broadening distribution. Such alliances are presented as key drivers of adoption within multifamily housing ecosystems.
At WHOOP, we’re on a mission to unlock human performance. WHOOP empowers members to perform at a higher level through a deeper understanding of their bodies and daily lives. Our wearable device and performance optimization platform has been adopted by many of the world's greatest athletes and consumers alike.

WHOOP's Top Stability & Growth Strengths
Strong Revenue Growth: Bookings are reported to have grown 103% year over year in 2025, exiting at a roughly $1.1B annualized run rate, indicating rapid top-line momentum. Additional signals such as sustained wholesale growth reinforce that commercial scale is accelerating.
Healthy Cash Flow: Operations are described as cash-flow positive in 2025 while growth accelerated, suggesting improving financial sustainability alongside expansion. This combination points to scaling that is not purely subsidized by burn.
Investor Backing & Capital Strength: A $575M Series G at a $10.1B valuation underscores substantial access to capital and confidence from prominent investors. This financing is framed as enabling continued international expansion and hiring.
At Intenseye, we believe protecting people at work is non-negotiable. That’s why we’re building the world’s most advanced AI-powered platform for industrial environments, designed to help organizations move from reactive programs to proactive risk prevention across safety, operations, and quality management. Our technology gives enterprises the ability to see risk and inefficiency as they emerge, take action in real time, and...

Intenseye's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised is substantial, with a $64M Series B and roughly $90M+ total reported, alongside a valuation step-up from just under $100M in 2021 to approximately $275–300M by 2023. This trajectory indicates strong investor conviction and ample resources to scale.
Market Expansion: Geographic and deployment reach has widened markedly—from 15+ countries in 2021 to 45+ countries and 400+ facilities, covering 100,000+ workers, with a reported 125% footprint increase in 2023. Ongoing enterprise activity is reflected in hundreds of onsite visits and multi-site rollouts with large industrial customers.
Product Line Growth: Offerings have expanded beyond core computer vision to include mobile support, integrations, an AI safety assistant (Chief), and optional Sentinel hardware. Reported scale metrics (e.g., billions of images processed daily and tens of millions of unsafe acts detected) suggest sustained product investment and adoption.

Blissway is a transportation tech startup founded by Stanford grads that uses machine learning and IoT to simplify the collection of tolls and improve road safety. Backed by Y Combinator –the famed startup accelerator– and some of the best investors in Silicon Valley, we have been developing and testing our technology with the Colorado Department of Transportation and transportation agencies...
Blissway's Top Stability & Growth Strengths
Strong Hiring & Retention: Headcount and active hiring are described as increasing, with a new Denver headquarters and dedicated international recruiting indicating continued team expansion. Multiple profiles note ongoing engineering hires and growth in the 11–50 employee range.
Product Line Growth: The company’s offerings now span automated tolling, HOV/express-lane occupancy verification, commercial back-office systems, disaster-recovery/interim tolling, and point-to-point speed enforcement. This broader scope suggests movement from a single-solution focus toward a platform approach.
Market Expansion: Deployments in Colorado and inclusion in Washington State technology studies indicate activity beyond a single corridor, alongside the establishment of a Denver operational hub. References to statewide program use and corridor expansions point to a growing geographic footprint.
Apptronik is building robots for the real world to improve human quality of life and to help solve the ever-increasing labor shortage problem. Our team has been building some of the most advanced robots on the planet for years, dating back to the DARPA Robotics Challenge. We apply our expertise across the full robotics stack to some of the most...
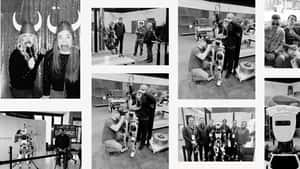
Apptronik's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor participation is substantial, with nearly $1B raised across Series A tranches and backing from corporates like Google and Mercedes‑Benz to fund production and deployment. Feedback suggests this capital base is intended to accelerate scaling of Apollo and broader operations.
Strategic Partnerships: Partnerships span Mercedes‑Benz, GXO Logistics, Jabil, and Google DeepMind, moving Apollo from demos into pilots and industrial integrations. These relationships indicate advancing commercialization and access to manufacturing and AI capabilities.
Strong Hiring & Retention: Headcount expanded into the hundreds with senior hires from Waymo, Boston Dynamics, and Amazon to drive commercialization. Public statements note continued hiring to support production, facilities build‑out, and deployments.
Motive builds technology to improve the safety, productivity, and profitability of businesses that power the physical economy. The Motive Automated Operations Platform combines IoT hardware with AI-powered applications to automate vehicle and equipment tracking, driver safety, compliance, maintenance, spend management, and more. Motive serves more than 120,000 businesses, across a wide range of industries including trucking and logistics, construction, oil...
Motive's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have risen year over year in 2024 and continued to increase through the first nine months of 2025, with ARR also advancing into 2026. Feedback suggests the top line is scaling rather than stalling, supported by SEC-filed figures and subsequent company updates.
Customer Loyalty & Retention: Large-account net dollar retention remained well above 100%, indicating meaningful expansion within existing customers. Feedback suggests this cohort continues to spend more over time, reinforcing durable relationships.
Investor Backing & Capital Strength: The company secured a multi‑billion‑dollar growth financing package in 2026 following what it called a strong quarter. Feedback suggests access to substantial external capital provides runway for continued investment and expansion.
Bilt Rewards is the first loyalty program that rewards members on rent and in their neighborhood, no matter where they live. Bilt Members can earn points and access exclusive benefits on rent payments, condo & co-op fees, and around their neighborhood at local restaurants, fitness studios, rideshare, pharmacy, and more. Ranked the highest-value point currency by top publications, Bilt Points...
Bilt's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as rising quickly, with the company expecting to cross $1B in 2026 and outside estimates placing recent annual revenue in the hundreds of millions. Platform activity also expanded sharply, with annual spend cited at $30B+ in 2024 and a $100B+ annual housing-spend target by year-end 2025.
Market Expansion: The network is said to reach roughly 1 in 4 U.S. apartment buildings and 6.5M+ homes, alongside 40,000–50,000+ merchant partners. The business scope has broadened beyond the original card into housing payments, mortgages, neighborhood commerce, and travel.
Investor Backing & Capital Strength: Capital raises of $200M (Jan 2024), $150M (Aug 2024), and $250M (Jul 2025) were accompanied by a valuation step-up to about $10.75B. This trajectory indicates substantial investor confidence and access to funding to support continued scale.
HRL Laboratories, an IBM company, pioneers the next frontiers of physical and information science. Delivering transformative technologies in automotive, aerospace and defense, HRL advances the critical missions of its customers. As a private company owned by IBM, HRL is a source of innovations that advance the state of the art in profound and far-reaching ways.
HRL Laboratories's Top Stability & Growth Strengths
Strategic Partnerships: An exclusive licensing and manufacturing agreement with MACOM for HRL’s 40nm GaN-on-SiC process moves core technology toward broader commercialization. Additional 2025 collaborations (including DARPA-funded programs and quantum work with Boeing) reinforce a partner-led scaling model.
Product Line Growth: Opening a 60,000-square-foot Camarillo facility expanded infrared hardware fabrication and testing, with large-format focal plane capacity rising from roughly 15 to over 75 per year. GaN-on-SiC reaching Manufacturing Readiness Level 6 and a planned transition to a volume manufacturer signal movement from R&D into productization.
Investor Backing & Capital Strength: Completion of IBM’s acquisition in August 2026 provides institutional resources to integrate HRL’s silicon-spin qubits, quantum sensing, and materials capabilities into a larger roadmap. Independent coverage characterized the deal as adding a second technological approach to IBM’s quantum strategy.

Unusual Machines, Inc. is an American company that manufactures and sells drone components, specializing in First-Person View (FPV) technology. They also operate a drone-focused e-commerce marketplace and are involved in counter-UAS systems.
Unusual Machines, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue more than doubled in 2025 and accelerated through 1H 2026, with Q2 2026 reaching about $16.7M and first-half revenue of $24.8M. The mix pivoted toward enterprise component sales, which became the primary driver by 2025 and dominated in early 2026.
Investor Backing & Capital Strength: The company raised substantial equity, including a $60M at-the-market offering completed May 29, 2026, and reported roughly $229.6M in cash and $86.8M in investments as of June 30, 2026. This capital base is being deployed into facilities, equipment, inventory, and headcount to support scaling.
Future-Ready Strategy: Emphasis on NDAA-compliant, U.S.-made components and Blue UAS/Framework alignment positions the firm to benefit from policy-driven shifts away from Chinese supply chains. Orlando-based manufacturing build-out and the Fat Shark/Rotor Riot acquisitions underpin access to FPV and defense-adjacent demand.
Securing The Freedom of Operations Headquartered in Colorado, Sierra Space is a mission-proven Defense Tech company delivering satellite platforms, critical subsystems, reusable spaceplanes, hypersonic technologies, propulsion systems, and infrastructure for the nation’s most critical missions. With more than three decades of heritage and a record of flight-proven success in space, Sierra Space is trusted by U.S. National Security, Civil customers, and global...
Sierra Space's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised has grown markedly, including a $550 million Series C in March 2026 that lifted total investments since 2021 above $2 billion and valued the company at $8 billion. This financing momentum aligns with sizable government awards and ongoing scale-up efforts.
Market Expansion: The creation of a dedicated defense unit, new manufacturing capacity (e.g., the 60,000-square-foot Victory Works) and a footprint exceeding 1 million square feet indicate expansion from development into larger-scale defense manufacturing. Significant awards since 2023—such as $1.5 billion in defense contracts and Space Development Agency awards of $740 million (2024) and $798 million (2026)—reinforce this broader market reach.
Diversified Customer Base: Activity spans national-security customers, NASA (e.g., a lunar logistics study and payloads for the Dream Chaser inaugural flight), the U.S. Air Force (engine development), and Mitsubishi Heavy Industries (ISS docking components). This mix points to multiple civil, defense, commercial, and international demand sources.
Ibotta (NYSE: IBTA) is a leading performance marketing platform allowing brands to deliver digital promotions to over 200 million consumers through a network of publishers called the Ibotta Performance Network (IPN). The IPN allows marketers to influence what people buy, and where and how often they shop – all while paying only when their campaigns directly result in a sale....
Ibotta's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with major platforms and retailers are expanding distribution and activity. Feedback suggests Uber and Giant Eagle joined in 2026 and a multi‑year 7‑Eleven deal was announced, while relationships with Walmart, Instacart and DoorDash underpin third‑party publisher redemption revenue up 27% year over year in Q2 2026.
Market Expansion: Network usage is scaling across publishers and channels. Feedback suggests Q2 2026 redeemers rose 21% to 20.9M, third‑party publisher redemptions increased 27% year over year, and H1 2026 total redemptions climbed from 163.3M to 179.4M.
Strong Market Position & Advantage: Positioning reflects a leading role in U.S. digital promotions with privileged retailer access. Feedback suggests Walmart exclusivity, a network reaching 200M+ consumers, and 900+ clients representing 3,100+ CPG brands provide a defensible competitive footing.
Boston-based company Piaggio Fast Forward Inc. (PFF) was founded in 2015 by the Piaggio Group (the Italian manufacturer that created the iconic Vespa scooter). In order to bring products to market today, PFF is solving the problem of robotic interaction with people in dynamically changing environments. We’re innovators, neighbors and creators with a passion for local living and pushing the...
Piaggio Fast Forward's Top Stability & Growth Strengths
Product Line Growth: Product offerings have expanded from consumer robots (gita, gitamini) to the B2B kilo platform, with additional features like Forward Following, Trips, and hybrid navigation introduced in 2025–2026. This points to an actively developing portfolio rather than a static lineup.
Market Expansion: The move from consumer-focused products into manufacturing, warehousing, and facilities management signals a broader addressable market. Parent-company materials in 2026 still describe active marketing and Boston-based manufacturing across multiple robot platforms.
Innovation-Driven Growth: Continued releases such as a production-ready hybrid-navigation AI model and other capability updates indicate ongoing R&D and technology maturation. Brand collaborations like the Grogu/Star Wars gitamini also reflect sustained commercialization activity.
.jpeg)
We are a world leader in innovative memory solutions that transform how the world uses information to enrich life for all. For over 45 years, our company has been instrumental to the world’s most significant technology advancements, delivering optimal memory and storage systems for a broad range of applications.

Micron Technology's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate a sharp acceleration in sales, with quarterly revenue several times higher than a year earlier and sequential gains continuing. Management guidance suggests this momentum is expected to carry into the next quarter.
Profitability: Margins and net income have expanded dramatically alongside stronger pricing and mix toward AI-related products. Operating cash generation has also risen substantially, reinforcing financial strength.
Innovation-Driven Growth: Advanced AI memory offerings—such as HBM, high-capacity DIMMs, and server DRAM—are described as ramping rapidly and contributing materially to the top line. Segment data shows broad gains in cloud, core data center, mobile/client, and automotive/embedded tied to these innovations.
Runwise is a fast-paced, customer-focused New York City / Boston based energy tech startup that controls the heating systems in nearly 2000 + buildings throughout the Northeast. Runwise’s unique hardware and software service significantly reduces energy usage, substantially lowering costs and carbon output.
Runwise's Top Stability & Growth Strengths
Market Expansion: Installed footprint is described as advancing from roughly 1,000 to 7,500 and then to 10,000+ buildings across the U.S., with growth beyond an early NYC focus into multiple states. Materials also cite 1,000+ customers and expansion into public-sector portfolios.
Investor Backing & Capital Strength: A $55M Series B in June 2025, alongside additional debt, brought total funding to about $79M to support scaling. Announcements link this capital to team expansion, product development, and entry into new markets.
Product Line Growth: Capabilities expanded from heating optimization into cooling management, water leak detection, gas monitoring, and smart smoke detection. An acquisition added wireless water‑leak monitoring, reinforcing the broader smart building operating system positioning.


Work Your Passion. Live Your Purpose.

