

Top Transportation Companies (4,624)
We are a mobility company that innovates like a start-up and thinks like a technology company. This helps us anticipate change in one of the most complex industries in the world and respond quickly. We depend on a team of 171,000 dynamic, entrepreneurial-minded employees in an environment where great ideas flourish. Our presence spans 343 manufacturing operations and 88 product...

Magna International's Top Stability & Growth Strengths
Profitability: Adjusted earnings are rising faster than sales, with Q2 2026 adjusted EBIT at $677M versus $583M and adjusted EPS at $1.86 versus $1.44, and the 2026 outlook targets a higher adjusted EBIT margin. These results indicate improved earnings quality alongside only modest top-line expansion.
Healthy Cash Flow: Cash generation is robust, with first-half 2026 free cash flow near $1.0B and full-year guidance of $1.75–$1.85B, following strong cash flow in 2025. This points to strengthening liquidity and funding capacity even without rapid revenue growth.
Cost & Operational Efficiency: Earnings improvements are attributed to productivity initiatives and other operating factors, and margins expanded while sales increased only slightly. This suggests better conversion of revenue into operating profit.

At General Motors, our vision is to create a world with Zero Crashes, Zero Emissions, and Zero Congestion. We wholeheartedly embrace the responsibility to lead the change that will make our world better, safer, and more equitable for all. Our industry and company are undergoing a once-in-a-lifetime technological transformation, which is reshaping our approach to technology and innovation. We are expanding...
General Motors's Top Stability & Growth Strengths
Profitability: Profitability is rising, with Q3 results showing adjusted diluted EPS above 30% year over year, net income of about $3.3B, and adjusted EBIT up 22% alongside margin expansion in North America. Recent quarters indicate the company is converting a larger share of revenue into earnings.
Healthy Cash Flow: Cash generation appears strong, highlighted by roughly $5.9B in adjusted automotive free cash flow for the quarter and full‑year guidance calling for $11.5–$12.5B. A new $20B share repurchase authorization underscores confidence in ongoing cash flow.
Strong Market Position & Advantage: Demand for high‑margin full‑size pickups and SUVs remains a key advantage, with wholesale deliveries up 5.2% in the quarter and North American performance anchoring margins. The company continues to be a major U.S. automaker with notable strength in these segments.
Founded in Chicago in 1987 by Stan Day, SRAM, LLC has grown to be one of the world's largest bicycle component manufacturers. Today, we are led by CEO, Ken Lousberg, and Stan Day serves as Chairman of our Board. SRAM’s global footprint helps us bring cycling to every corner of the globe, including your local roads and trails. We design and...

SRAM, LLC's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Evidence indicates revenue returned to growth in 2025 and remained above pre-pandemic levels, aided by aftermarket demand and normalized inventories. This signals a recovery trajectory supported by ongoing investments rather than a transient spike.
Market Expansion: A planned 270,000-square-foot factory in Portugal with phased operations from 2028 and 500+ projected jobs, plus a new Italian facility combining Ochain operations with technical service, extend the European footprint. These moves increase regional capacity and proximity to dealers and OEMs.
Product Line Growth: New releases such as RED AXS and Force AXS, alongside acquisitions including Ochain and earlier additions like Hammerhead and TIME, broaden the component and technology portfolio. This expanded lineup supports engagement across premium segments and the aftermarket.

We are an omnichannel customer acquisition platform with offices throughout the US, Canada and Europe. System1 builds desktop and mobile apps, search engines, and online publications that empower consumers with information while respecting their privacy. We also operate brands that include CouponFollow, Startpage and MapQuest. System1 is a champion of AI technology, investing in the first legal AI called Vinny...

System1's Top Stability & Growth Strengths
Innovation-Driven Growth: New AI agent-oriented products and data offerings were launched in 2026, including a MapQuest Model Context Protocol server, Dogpile Fetch, and the IntentStream audience-intent platform. These initiatives indicate efforts to expand beyond traditional advertising into AI-enabled distribution and data monetization.
Product Line Growth: Owned products show momentum, with Startpage sessions up 31% year over year in Q2 2026 (mobile app +63%) and MapQuest reporting 14% organic traffic growth and 23% site-wide revenue growth in Q1 2026. Segment data also show Products revenue rising 16% to $93.2 million in 2025.
Cost & Operational Efficiency: Margins improved as lower-margin search monetization was deliberately reduced, with adjusted gross margin reaching 85% in Q2 2026. Full-year 2025 also saw adjusted EBITDA increase 9% despite lower revenue, signaling a higher-quality revenue mix.
IG North America is home to tastytrade, tastylive, tastyfx, and tastycrypto—a family of brands built to democratize trading and empower individual investors. Founded in Chicago by the creators of thinkorswim, acquired by London-based IG Group in 2021, we combine startup innovation with the backing of a global fintech leader with 50+ years of experience. From our headquarters in Chicago's Fulton...
tastytrade/ tastylive/ tastyfx/ tastycrypto's Top Stability & Growth Strengths
Strong Revenue Growth: Trading revenue is described as rising consistently across multiple half-year periods, with calendar 2025 up 23% and H2 2025 higher than H1 2025; feedback suggests momentum further accelerated in the second half.
Customer Loyalty & Retention: Long-term customer retention is indicated as improving, with a greater share of customers trading for at least five years by H2 2025; feedback suggests this supports durability in the franchise.
Product Line Growth: The ecosystem is adding features such as 24/5 equities trading, expanded crypto support, stablecoin funding, FX integration, and extended trading hours; feedback suggests these rollouts broaden engagement and revenue opportunities.
It's simple, at DraftKings, we believe life is more fun when you're in on the action. For that reason, we’re committed to responsibly creating the world’s favorite games and betting experiences. We’re developing the most innovative and entertaining real money products and offers; to forever transform how people experience sports; to be a fully vertically integrated sports betting operator. It's...

DraftKings's Top Stability & Growth Strengths
Strong Revenue Growth: Annual revenue rose from $3.67B in 2023 to $6.05B in 2025, and management guides to $6.5–$6.9B for 2026. This multi-year trajectory signals substantial top-line expansion despite quarterly volatility.
Market Expansion: The sportsbook operates in 30 states, Washington, D.C., Puerto Rico, and parts of Canada. Broader geographic access supports continued user and wagering growth.
Diversified Revenue Streams: Sportsbook, iGaming, and the newer Predictions offering provide multiple growth avenues. iGaming revenue grew 7.5% year over year in Q2 2026, while Predictions launched in December 2025 as another channel.

We are the premier AI-native Claims TPA, that blends the technical expertise of our adjusters and the benefits of modern technology. We have an unwavering commitment to be a proactive risk management partner to our clients, drive industry-leading outcomes, and create a fundamentally more data-rich, transparent and better claims experience. We are backed by General Catalyst, Lightspeed, and Valor Equity Partners....
Vega's Top Stability & Growth Strengths
Strong Hiring & Retention: Hiring across claims, sales, marketing, and strategy is actively underway, and third-party estimates indicate headcount rose from roughly a dozen to several dozen within about a year. Company pages and listings also reference multiple offices and continued recruitment, signaling organizational scale-up.
Strong Revenue Growth: Company job postings describe 10× year-over-year revenue growth and a path to a multimillion-dollar run rate in under two years. While company-reported, these signals align with visible expansion in roles and operations.
Strategic Partnerships: A named claims partnership with Nirvana and references to onboarding new partners point to expanding commercial relationships. Case-study content highlights full-lifecycle deployments that suggest deeper integration with customers.
Bankrate is redefining the future of financial decision-making. For nearly five decades, we’ve empowered tens of millions of consumers to make smarter financial choices and helped hundreds of leading financial institutions grow. Today, we’re evolving from a marketplace into a next-generation technology platform—underpinned by proprietary data, AI-driven innovation, and deep enterprise integrations. With our track record of delivering consumers quantifiably...

Bankrate's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with hundreds of financial institutions and an expanded collaboration with TransUnion indicate a robust commercial network and more personalized offer delivery at scale. Integration of historical interest‑rate data into FRED further extends institutional reach and visibility.
Future-Ready Strategy: New leadership, AI‑enabled workflows, and a 2026 brand and platform redesign point to active investment in evolving from a marketplace to a technology‑driven platform. The launch of the Bankrate Data Center and focus on AI/organic search readiness suggest preparation for shifting search and distribution dynamics.
Strong Market Position & Advantage: An established brand serving 100M+ people annually and decades of specialization in rate comparisons underpin a durable position in U.S. personal finance. Third‑party estimates still show millions of monthly visits and strong rankings for mortgage and loan calculators.
Boston-based company Piaggio Fast Forward Inc. (PFF) was founded in 2015 by the Piaggio Group (the Italian manufacturer that created the iconic Vespa scooter). In order to bring products to market today, PFF is solving the problem of robotic interaction with people in dynamically changing environments. We’re innovators, neighbors and creators with a passion for local living and pushing the...
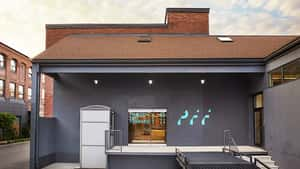
Piaggio Fast Forward's Top Stability & Growth Strengths
Product Line Growth: Product expansion into industrial robotics with kilo alongside ongoing consumer variants (e.g., Star Wars-inspired gitamini) and feature updates points to a broader offering. This widens the use cases from personal cargo robots to workplace and industrial material handling.
Market Expansion: A visible pivot toward B2B use cases, including planned factory deployments and stated fleet rollouts with several Fortune Global 500 companies, indicates broader commercial reach. The Disney collaboration adds an additional retail channel and audience for consumer products.
Innovation-Driven Growth: Continued technology investment—such as hybrid-navigation AI, Forward Following, and Trips—shows an active R&D agenda. A large human-motion dataset and iterative capability releases suggest efforts to improve commercial usefulness in dynamic environments.

ASI is a dual-use software company that deploys predictive AI to the world's most complex operating environments. Backed by leading investors–including Andreessen Horowitz, Renegade Partners, and Spark Capital–we actively manage over 40% of all US air traffic across both public and private sector air operations. Partnering with major airlines like United and Alaska, we optimize thousands of flights daily, delivering...
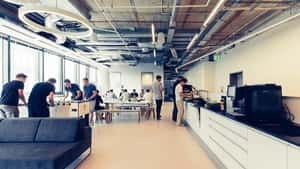
Air Space Intelligence's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $325 million Series C at a reported $3 billion valuation, led by Spark Capital with participation from firms such as Andreessen Horowitz, signals strong capital access and confidence in future scale. The company describes using this capital to expand aviation, defense, energy, logistics, research, and engineering operations.
Market Expansion: Major awards like the FAA’s 12-year program (reported up to $875 million) and a five-year, $99 million U.S. Army contract, alongside airline customers and a National Grid collaboration, indicate expansion across government, commercial, and energy sectors. Partnerships such as Joby Aviation and new defense programs (e.g., DIU and the Open Mission Engine) further extend reach beyond the original aviation focus.
Strong Hiring & Retention: Dealroom reports 26.3% annual team growth with an estimated 173 employees and open positions, while another market source cites an increase from 163 to 228 in a quarter. Active recruiting across engineering, machine learning, cloud, mission operations, and growth roles points to organizational scaling.
Mastery is the World’s First Lovable Transportation Management System™ (TMS) built to support the complex world of logistics and supply chain. Mastery brings to market MasterMind™, a cloud-based SaaS technology solution for large complex organizations, providing interconnected automation, visibility, and productivity across their supply chains.
Mastery Logistics Systems's Top Stability & Growth Strengths
Product Line Growth: Recent announcements highlight expanded integrations with Samsara and ISAAC and the rollout of embedded AI analytics, indicating active investment in platform capabilities. Crane Worldwide Logistics being identified as live on the full Samsara integration further supports ongoing development and deployment.
Market Expansion: Plans to extend MasterMind beyond large asset-based carriers into private fleets and shippers, together with enterprise selections by Bison Transport and Red Classic across multiple periods, point to a widening customer reach. These moves broaden the addressable market even if revenue impact was not disclosed.
Strategic Partnerships: Strategic ties with major transportation providers and ecosystem partners—including Schneider and Werner relationships and integrations with Samsara and ISAAC—underscore collaborative momentum. Such partnerships can open channels for adoption and strengthen go-to-market efforts.
Blissway is a transportation tech startup founded by Stanford grads that uses machine learning and IoT to simplify the collection of tolls and improve road safety. Backed by Y Combinator –the famed startup accelerator– and some of the best investors in Silicon Valley, we have been developing and testing our technology with the Colorado Department of Transportation and transportation agencies...

Blissway's Top Stability & Growth Strengths
Market Expansion: Public-sector documentation of pilots and contract milestones in Colorado, plus a LinkedIn-noted I‑5 deployment in California, point to expanding geographic activity. References to agency engagement in states like Washington and North Carolina further indicate broader market reach.
Strong Hiring & Retention: Active listings across electrical, embedded, software, and machine-learning roles, along with a new Denver headquarters and an 11–50 employee footprint, indicate ongoing team expansion. Built In’s listing of roughly two dozen employees and multiple open roles reinforces continued hiring momentum.
Product Line Growth: The company’s site describes applications spanning all‑electronic tolling, HOV/express‑lane occupancy verification, commercial back‑office systems, interim tolling, and speed enforcement, indicating a broadened offering. Such scope suggests multiple avenues to capture demand across transportation and safety use cases.

People Inc. is America’s largest digital and print publisher. Our 40+ iconic and fast-growing brands harness the best intent-driven content, the fastest sites, and the fewest ads to help nearly 200 million people every month, including 95 percent of US women, make decisions, take action, and find inspiration. People Inc. brands include PEOPLE, Better Homes & Gardens, Verywell, FOOD &...

People Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Digital revenue increased again in Q2 2026 and has risen for an extended multi‑quarter streak, with segment margins also expanding. Digital operating income and adjusted EBITDA both advanced, indicating momentum beyond the top line.
Diversified Revenue Streams: Licensing and performance marketing expanded meaningfully while digital advertising was roughly flat, showing growth is not reliant on a single channel. Non‑session‑based revenue benefited from distribution and content partnerships such as Apple News+ and OpenAI.
Healthy Cash Flow: Operating cash flow and free cash flow improved in the first half of 2026. This signals better cash generation alongside digital expansion.

Dealerware transforms the automotive retailers of today into the mobility network of tomorrow. Launched in 2016, Dealerware manages tens of thousands of vehicles at dealerships in North America across every major manufacturer brand. By combining a mobile-first approach with fresh design thinking, Dealerware’s industry-leading SaaS platform enables best-in-class fleet management and mobility services for the top automotive dealerships and manufacturers.

Dealerware's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital from Wavecrest Growth Partners and Radian Capital following the December 2025 acquisition is positioned to accelerate product development and expand offerings. Subsequent board updates and senior hires indicate resources and governance aligned to scale the business.
Product Line Growth: The introduction of Dealerware Insights in early 2026 and added capabilities like embedded pickup-and-delivery extend the platform beyond core fleet administration into enterprise analytics and broader workflows. This expansion can deepen relationships with dealer groups and OEMs and open incremental product revenue opportunities.
Strategic Partnerships: Integrations with Tekion’s Automotive Retail Cloud and partnerships with myKaarma and HopDrive connect the platform to key dealership systems and service-lane workflows. Such ecosystem ties reduce adoption friction and can widen distribution across the reported base of 3,000+ retailers and 100,000+ connected vehicles.
We started as a company that turned phones into walkie-talkies. Today, we modernize instant voice communication with our industry-leading push-to-talk technology to help mobile workers meet quickly changing, urgent, real-world challenges. We have the highest-rated walkie-talkie app, with over 8 billion messages sent per month and 170 million users in industries such as transportation, retail, construction, hospitality, healthcare, and more....
Zello's Top Stability & Growth Strengths
Strong Market Position & Advantage: Platform activity is substantial, with 5 million monthly active users and roughly 10 billion voice messages each month, alongside 100M+ Android downloads and a reported user base exceeding 150 million. These indicators reflect established scale even if they do not confirm the current growth rate.
Innovation-Driven Growth: The offering has expanded beyond push-to-talk into AI-assisted answers, conversation search, operational insights, task management, transcription, translation, and voice commands during 2025–2026. These capabilities are aimed at increasing value for enterprise and frontline customers.
Strategic Partnerships: Partnerships include a 2023 integration with Cisco Webex and a 2026 co-designed push-to-talk headset with Shokz. Such ecosystem moves can extend enterprise reach and improve adoption among frontline workers.

At Edmunds, we make the car buying experience easier. By combining expert vehicle reviews and real-time consumer and automotive market insights with a suite of intuitive shopping tools, we empower millions of people to buy, sell, and price cars with total confidence. While we are an established leader in automotive tech, our company thrives on innovation and agility, pushing the...

Edmunds's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Corporate ownership by CarMax provides institutional support and resources, which feedback suggests helps Edmunds remain resilient through automotive cycles.
Strong Market Position & Advantage: The platform is characterized as an established automotive research and car‑shopping brand with significant audience scale and recognized tools, indicating enduring competitive positioning.
Strong Hiring & Retention: Estimated headcount has risen modestly over multiple years, which feedback suggests reflects steady organizational stability rather than rapid expansion.
Our platform creates comprehensive digital twins of your supply chain with AI-powered digital workers to automate resolution, improve collaboration and drive outcomes across all stakeholders. Unlike traditional control towers, we enable true real-time execution and intelligent fulfillment, transforming both your supply and customer-facing operations.
FourKites's Top Stability & Growth Strengths
Innovation-Driven Growth: Product expansion beyond shipment tracking into AI agents, inventory intelligence, automated ocean freight booking, and an Outcome-as-a-Service model reflects continued investment in new capabilities. These launches aim to deliver measurable operational results and deepen the platform’s role in supply-chain automation.
Strong Market Position & Advantage: Industry recognition such as a 2024 Leader placement in Gartner’s Real-Time Transportation Visibility Platforms and a 2026 Leader placement in Nucleus Research’s Control Tower matrix, alongside scale serving 1,600+ brands and millions of daily shipments, points to a durable competitive position. These signals indicate established enterprise adoption and credibility in core markets.
Strong Revenue Growth: The Indian subsidiary reported revenue rising from ₹124.4 crore in FY2024 to ₹147.4 crore in FY2025, evidencing tangible top-line expansion within that operation. While not a consolidated global view, this datapoint supports momentum in at least one major entity.
Agero is a leading provider of driver assistance, accident management, consumer affairs support and connected vehicle services for stakeholders across the automotive industry, including the world’s largest automakers, auto retailers, insurers, rideshare providers and other brands. As the driving force behind mobility support throughout all points in the vehicle ownership journey - from purchase to maintenance and breakdown to resell or...
Agero's Top Stability & Growth Strengths
Market Expansion: Evidence indicates the 2026 acquisition of Urgently and added commercial roles broaden Agero’s reach across automotive, fleet, rental, and insurance, taking the combined platform to about 150 million vehicles and roughly 13–14 million annual service events. New and renewed programs further extend activity across roadside assistance, claims, and mobility services.
Strong Market Position & Advantage: Company materials describe service to approximately 150 million drivers, relationships with six of the top ten insurers, and a nationwide network of 8,000+ providers. External recognition such as Frost & Sullivan’s 2025 North American Company of the Year reinforces a durable competitive position in digitalized roadside assistance.
Strategic Partnerships: Renewals and wins like Hagerty and Virginia Farm Bureau Insurance, plus collaborations such as MOTER, point to deep, ongoing enterprise relationships. These ties support recurring service volumes and cross-sell opportunities across roadside, accident management, and connected-vehicle offerings.
SambaSafety is a recognized innovator and leading provider of cloud-based risk management solutions for over 15,000 organizations with automotive mobility exposure, including many on Fortune’s Global 500 list. Employers and insurers benefit from SambaSafety’s continuous monitoring, intuitive insights, risk reduction tools, and configurable pricing solutions. Through the collection, correlation, and analysis of federal, state, local, and telematics data sources, SambaSafety's...
SambaSafety's Top Stability & Growth Strengths
Strong Market Position & Advantage: Scale indicators such as more than 16,000 customers and over 6.5 million drivers monitored point to a significant presence in driver-risk management. Integrations with over 100 telematics providers and long operating history reinforce this position.
Innovation-Driven Growth: Recent launches including AI-powered risk summaries, an AI analyst, and enhancements to monitoring, compliance, and training show active investment in next-generation capabilities. Continued product updates across 2025–2026 suggest sustained innovation momentum.
Market Expansion: Expansion into the UK and Canada alongside broader international capabilities indicates widening geographic reach. Channel growth is supported by partnerships spanning fleets, insurers, and hiring platforms.
Motive builds technology to improve the safety, productivity, and profitability of businesses that power the physical economy. The Motive Automated Operations Platform combines IoT hardware with AI-powered applications to automate vehicle and equipment tracking, driver safety, compliance, maintenance, spend management, and more. Motive serves more than 120,000 businesses, across a wide range of industries including trucking and logistics, construction, oil...
Motive's Top Stability & Growth Strengths
Strong Revenue Growth: Annual recurring revenue exceeded $600 million with year-over-year growth accelerating to 30%, and recognized revenue rose about 22% in the first nine months of 2025 versus the same period in 2024. These figures point to continued scaling in both subscription run rate and reported sales.
Investor Backing & Capital Strength: More than $1.3 billion in growth financing was secured in September 2026, alongside a prior $150 million round in 2025. This capital is intended to fund AI development and go-to-market expansion, indicating deep funding support for further growth.
Customer Loyalty & Retention: ARR from customers spending over $100,000 annually grew nearly 60% year over year, with net revenue retention above 120% for larger accounts. This suggests expansion within the existing customer base and strengthening enterprise relationships.


Work Your Passion. Live Your Purpose.

