

Top Adtech Companies (5,230)
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising year over year in 2025 and accelerating to double‑digit growth in early 2026, with management raising its full‑year outlook. Bookings and room nights are also increasing, reinforcing the top‑line trend.
Profitability: Profitability expanded faster than revenue in 2025 and continued to improve in 2026, including margin expansion in the latest quarter. This indicates operating leverage and stronger earnings quality alongside growth.
Diversified Revenue Streams: B2B has been growing much faster than the consumer business, and advertising/media also expanded strongly in 2025. Multiple engines—B2B, lodging, and advertising—are contributing materially to overall expansion.
RTB House is a global technology company specializing in innovative marketing solutions powered by deep learning algorithms. Founded in 2012, the company has rapidly grown into a leader in the field of personalized advertising, offering a full-funnel marketing platform that drives real results. Our proprietary technology enables brands to deliver highly relevant and precisely targeted ads to consumers, enhancing engagement...

RTB House's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is portrayed as rising over recent years, with directional estimates indicating 2023–24 gains and Polish filings showing long‑term expansion, albeit not strictly linear. This points to continued top‑line momentum even as exact consolidated figures remain private.
Market Expansion: Operations are described across 90+ markets with 4,000+ campaigns and ongoing hiring in multiple regions, and the company states its global expansion is still gathering pace. Geographic references include teams and roles spanning the U.S., Korea, Romania, Poland and other markets.
Product Line Growth: A self‑service platform (rtb.com) launched in 2026 targets SMBs and agencies, expanding beyond the traditional enterprise focus. Offerings are also characterized as extending into DSP, CTV/OTT, first‑party advertising, and AI/Deep Learning.

Rokt is the global leader in ecommerce, unlocking real-time relevance in the moment that matters most - The Transaction Moment. Rokt’s AI Brain and Ecommerce Network powers billions of transactions connecting hundreds of millions of customers, and is trusted to do this by the world’s leading companies including Live Nation, Macy’s, Fanatics, AMC Theatres, PayPal, Uber, Hulu, Staples, Albertsons and...

Rokt's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as reaching about $600M with 43% year-over-year growth in 2024, with consistent references to 40%+ growth and independent estimates indicating expansion toward ~$900M annualized in 2025. This pattern is reinforced by multi‑year growth markers such as 330% revenue growth over a recent three‑year period and listings on major fast‑growth rankings.
Strong Market Position & Advantage: Scale indicators include 33,000+ companies (including more than half of leading global ecommerce brands), 165M monthly active users growing 45%+ YoY, and billions of transactions processed (7.5B+ in 2025 and 13B+ projected in 2026). High‑profile enterprise adoption across sectors (e.g., Uber, Live Nation, Macy’s, PayPal) underscores traction at the transaction moment.
Investor Backing & Capital Strength: Valuation stepped up from $2.4B (2022) to $3.5B in a January 2025 secondary transaction, alongside a prior $325M Series E and a $335M secondary, signaling sustained investor confidence. These capital events coincide with disclosures of rapid revenue growth and continued scaling.

We are an omnichannel customer acquisition platform with offices throughout the US, Canada and Europe. System1 builds desktop and mobile apps, search engines, and online publications that empower consumers with information while respecting their privacy. We also operate brands that include CouponFollow, Startpage and MapQuest. System1 is a champion of AI technology, investing in the first legal AI called Vinny...
System1's Top Stability & Growth Strengths
Cost & Operational Efficiency: Gross margins are far higher than the prior year and adjusted profitability improved in 2025, reflecting a disciplined shift toward higher‑margin Products and tighter spend. Management is intentionally reducing lower‑quality marketing activity to favor the Products business, supporting better unit economics.
Product Line Growth: The Products segment became the majority of revenue by mid‑2026 and showed sequential growth, with Startpage and MapQuest reporting rising sessions and site‑wide revenue. These pockets of traction indicate expanding engagement within specific product lines even as the company reshapes its mix.
Innovation-Driven Growth: New AI and agentic offerings were launched around MapQuest, Dogpile, and the IntentStream data platform, signaling ongoing product innovation. These launches are aimed at modernizing monetization and creating new growth vectors tied to owned properties.

AI is great at understanding what you're asking. It's terrible at giving you answers you can trust. Kepler built a platform that separates what AI does well from what code does well where AI handles the conversation, code handles the truth. The result is the first AI system that can show its work. Kepler automatically ingests scattered data, structures it into...
Kepler 's Top Stability & Growth Strengths
Market Expansion: Public materials indicate the platform now covers 27 global markets and has broadened beyond a core finance launch into areas like private equity, compliance, accounting, and tax. Feedback suggests the product is “live and in production,” with added distribution surfaces supporting reach into more workflows.
Strategic Partnerships: Announcements describe an Anthropic MCP connector available for existing customers and note that Anthropic’s team approached Kepler about building it, alongside data integrations such as Quartr. These integrations provide external validation and create new product surfaces for adoption.
Investor Backing & Capital Strength: Company pages identify institutional backers including Mantis VC and Company Ventures along with prominent operator‑angels, and separate profiles cite more than $7M raised by mid‑2026. This access to capital and experienced networks supports ongoing hiring, product development, and go‑to‑market efforts.
Ibotta (NYSE: IBTA) is a leading performance marketing platform allowing brands to deliver digital promotions to over 200 million consumers through a network of publishers called the Ibotta Performance Network (IPN). The IPN allows marketers to influence what people buy, and where and how often they shop – all while paying only when their campaigns directly result in a sale....
Ibotta's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with major platforms and retailers are expanding distribution and activity. Feedback suggests Uber and Giant Eagle joined in 2026 and a multi‑year 7‑Eleven deal was announced, while relationships with Walmart, Instacart and DoorDash underpin third‑party publisher redemption revenue up 27% year over year in Q2 2026.
Market Expansion: Network usage is scaling across publishers and channels. Feedback suggests Q2 2026 redeemers rose 21% to 20.9M, third‑party publisher redemptions increased 27% year over year, and H1 2026 total redemptions climbed from 163.3M to 179.4M.
Strong Market Position & Advantage: Positioning reflects a leading role in U.S. digital promotions with privileged retailer access. Feedback suggests Walmart exclusivity, a network reaching 200M+ consumers, and 900+ clients representing 3,100+ CPG brands provide a defensible competitive footing.

Adswerve is an award-winning predictive marketing consulting firm helping brands and agencies acquire, grow, and retain customers while maximizing ROI. Its 250+ experts combine human expertise, AI, deep platform mastery, and proprietary Adswerve Intelligence to deliver predictive marketing solutions across Data, Intelligence, Experiences, and Measurement. Adswerve is the largest independent US Google Marketing Platform provider, a leader in Google Cloud...

Adswerve, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Business lines such as Adobe services and Google Cloud consultancy are reported up sharply year over year (e.g., +65% and +40%), signaling momentum in core revenue-generating practices. Feedback suggests this growth coincides with active enterprise engagements and a sizable client footprint.
Strategic Partnerships: Selections and alliances with major platforms—such as Google’s Data Strength/GIP program, an Amplitude partnership, and repeated Adobe partner awards—show strong ecosystem alignment that can fuel pipeline and credibility. Feedback suggests these relationships extend reach across Google, Adobe, and adjacent analytics stacks.
Product Line Growth: New and expanded offerings, including Adswerve Premium Supply, AI-powered solutions, Adobe Journey Optimizer/Real-Time CDP services, and the Adswerve Connect platform, indicate continued broadening of solutions. This expansion suggests increased cross-sell potential and a wider addressable market.
Taboola empowers businesses to grow through performance advertising technology that goes beyond search and social and delivers measurable outcomes at scale. Taboola works with thousands of businesses who advertise directly on Realize, Taboola’s powerful ad platform, reaching approximately 600M daily active users across some of the best publishers in the world. Publishers like NBC News, Yahoo, and OEMs such as Samsung,...

Taboola's Top Stability & Growth Strengths
Healthy Cash Flow: Cash generation is improving, with free cash flow rising from $149.2M to $163.4M in 2025 and jumping from $36.1M to $90.3M in Q1 2026. Management outlook was raised after Q2 alongside stronger ex‑TAC gross profit and adjusted EBITDA guidance.
Profitability: Profitability is generally trending upward, with 2025 adjusted EBITDA up 7.2% and H1 2026 ex‑TAC gross profit up 11.3%, helped by higher ad spend and better margins with certain digital‑property partners. Although quarterly EBITDA has been uneven, the profit trajectory over multi‑period comparisons remains positive.
Market Expansion: Expansion efforts include the Realize platform and the announced plan to acquire Dianomi, which would broaden the advertiser/publisher footprint beyond organic growth. Scale remains significant at roughly 600M daily active users, supporting the push into adjacent opportunities.

Agentio has raised $56M to date at a $340M valuation, including a recent Series B led by Forerunner, which followed our Series A within a calendar year. Our investors also include Benchmark, Craft, and AlleyCorp. Agentio has been named to Forbes’ Next Billion Dollar Startups, 2025, and our platform is already used and loved by the world’s leading marketers and...

Agentio's Top Stability & Growth Strengths
Strong Revenue Growth: Reported 5× year-over-year growth by November 2025, with brands shifting tens of millions of dollars of paid-media spend to creator campaigns on the platform. This points to accelerating top-line momentum over a relatively short operating window.
Investor Backing & Capital Strength: Secured a $40M Series B in November 2025, bringing total funding to $56M and valuing the company at $340M, led by firms such as Forerunner with continued support from Benchmark and others. The funding cadence and valuation step-up indicate strong capital support for scaling.
Diversified Customer Base: More than 100 enterprise brands—including Uber, DoorDash, Cash App, Mint Mobile, Vuori, and Olipop—used the platform in 2025. This breadth of recognized customers suggests expanding adoption across multiple verticals.


Liftoff is a leading AI-powered performance marketing platform for the mobile app economy. Our end-to-end technology stack helps app marketers acquire and retain high-value users, while enabling publishers to maximize revenue across programmatic and direct demand. Liftoff’s solutions, including Accelerate, Direct, Monetize, Intelligence, and Vungle Exchange, support over 6,600 mobile businesses across 74 countries in sectors such as gaming, social, finance,...

Liftoff's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has risen strongly across 2025–2026, with the latest quarter marking the company’s 11th consecutive period of top-line expansion. Momentum is driven by continued gains in its Core Advertising business.
Profitability: Adjusted EBITDA expanded materially, with margins improving alongside scale, indicating solid operating leverage. Recent quarters show profitability strengthening even as the business invests for growth.
Healthy Cash Flow: Operating and free cash flow increased sharply on a trailing twelve‑month basis. Cash generation supports reinvestment and a stronger balance sheet following debt reduction.

Centerfield supercharges commerce for more than 2,000 brands, including 25% of the Fortune 100. Powered by its proprietary platform, Dugout, Centerfield efficiently acquires customers at scale through AI-driven search and LLM discovery, its digital brands, and intelligent media and sales optimization. Centerfield operates across categories such as insurance, home services, business services, and eCommerce among many others. Headquartered in Los...

Centerfield's Top Stability & Growth Strengths
Strong Revenue Growth: Inclusion on the 2026 Inc. 5000 with 56% three-year growth, plus repeated Inc. 5000 recognition across prior years, indicates sustained top-line expansion. Company materials also describe steady year-over-year revenue growth.
Market Expansion: Serial acquisitions—including Brainjolt (Nov 2024) and ConsumerVoice (Aug 2025), which opened more than a dozen new categories—show active expansion of reach and capabilities. The company also cites operations across three continents and access to 250 million consumers and 2,000+ brands.
Diversified Revenue Streams: Operations now span home services, insurance, B2B/business services, and e-commerce with dedicated offerings and platforms in each area. This breadth suggests reduced dependence on any single vertical.
Genius Sports is the layer between what happens on the field and how the world engages with it. Our solutions across the global sports ecosystem are underpinned by our next generation big data and artificial intelligence platform, GeniusIQ. By ingesting and computing multiple real-time data feeds, GeniusIQ powers a wide range of functions and applications across sports performance and officiation, fan engagement,...
Genius Sports's Top Stability & Growth Strengths
Strong Revenue Growth: Reported results show consistent top-line increases through 2025 and into 2026, including a sharp acceleration in Q2 2026. Guidance was raised above $1B for 2026, underscoring momentum.
Strategic Partnerships: Long-term, often exclusive relationships with tier‑one rights holders such as the NFL (through 2029), Football DataCo/Premier League (through 2029) and the NCAA (through 2032) reinforce commercial visibility. These agreements expand distribution and underpin growth across betting and media.
Innovation-Driven Growth: Product advances like GeniusIQ, BetVision, and Second Spectrum tracking are cited as drivers of expanding media and betting solutions. This innovation push aligns with rapid Media segment growth and broader market expansion.
.jpg)
Acquia is the open digital experience company. We provide the world's most ambitious brands with products built around Drupal to allow them to embrace innovation and create customer moments that matter. At Acquia, we believe in the power of community and collaboration — giving our customers and partners the freedom to build tomorrow on their terms.
Acquia's Top Stability & Growth Strengths
Product Line Growth: Continued expansion of the DXP across content, DAM, personalization, CDP and AI, plus ongoing 2025–26 launches, point to an actively growing portfolio. Acquisitions and AI-led releases (e.g., Monsido, updates to Acquia Source/AI) reinforce sustained product investment.
Strong Market Position & Advantage: Independent analyst coverage places the company as a Leader in DXP and highlights its enterprise Drupal positioning, indicating durable competitive standing. Thousands of organizations are reported to use its platform, underscoring entrenched market presence.
Customer Loyalty & Retention: Company retrospectives describe record renewal rates and customer expansion in 2023, signaling strong retention dynamics. These signals suggest customers are extending relationships and broadening adoption.
OpenX is The Intelligent SSP™ (supply-side platform), simplifying advertising for marketers, advertisers, and publishers worldwide. As one of the largest SSPs globally, OpenX combines the industry’s only fully cloud-based infrastructure with leading AI capabilities to make digital advertising easier and more effective across every format, including CTV. Built to responsibly deliver quality, performance, and adaptability, OpenX makes digital advertising safer,...
OpenX Technologies's Top Stability & Growth Strengths
Strong Revenue Growth: Consistent year-over-year gains are highlighted, including 12 consecutive quarters as of late 2025. Growth was linked to adding 200+ net-new brands and increased engagement with curation offerings such as OpenXSelect.
Market Expansion: Geographic reach broadened with TV by OpenX entering seven additional international markets in 2024 and a new Mexico office launching LATAM expansion in 2025. Additional investment in publisher-development personnel in January 2026 is described as supporting the next phase of publisher growth.
Innovation-Driven Growth: New offerings like OpenXSelect and AI/ML capabilities via OpenX IQ, alongside advances in CTV, are positioned as commercial drivers. A post-launch uplift in monetized impressions for TV by OpenX and ongoing product rollouts signal traction.
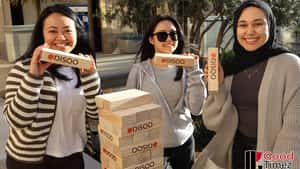
DISQO is a leading provider of advertising intelligence, measuring brand and performance outcomes across every media channel to power data-driven marketing decisions. Trusted by 500+ of the world’s largest brands and 150+ agency and media partners, and recognized by Inc., Deloitte, Ad Age, Digiday, Forbes, and Cynopsis, DISQO is redefining the power of measurement in advertising.
DISQO's Top Stability & Growth Strengths
Product Line Growth: Product capabilities have expanded with new cross‑media, cookieless and outcomes‑measurement offerings, a free self‑service brand‑lift tool in 2025, and an AI Search Lift product in 2026. This points to a broader addressable market and deeper product footprint.
Strategic Partnerships: Partnership activity includes being selected by publishers such as Vevo and DAX for outcomes and brand‑lift measurement. These relationships indicate ongoing commercial traction into 2025–26.
Diversified Customer Base: Commercial reach spans 500+ brands and 150+ agency/media partners, with earlier disclosures citing 800+ clients. This breadth across brands, agencies, and media companies reflects a diversified set of customer segments.
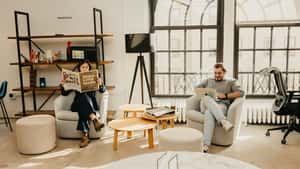
As a full-service agency, program operator, and SaaS technology platform, Share Local Media helps tech and e-commerce companies leverage direct mail to achieve efficient direct response outcomes with high quality branding.
Share Local Media's Top Stability & Growth Strengths
Product Line Growth: Product expansion from core direct mail into out-of-home (OOH), platform-enabled mail, reporting/analytics via Poplar, and insert media is repeatedly highlighted. These additions indicate a broader offering aimed at capturing more of the offline performance-marketing opportunity.
Strong Hiring & Retention: Headcount is described as growing from a small startup to roughly 85–100+ employees, with external profiles placing the company in the 51–200 range. Active openings and anniversary notes about team growth point to continued scaling of the workforce.
Innovation-Driven Growth: Technology-enabled approaches—such as Poplar’s enhanced real-time reporting, data-driven targeting, and new OOH measurement—are emphasized as central to the firm’s evolution. Industry recognition, including a 2026 Gold Mailbox Award, supports momentum tied to innovation.

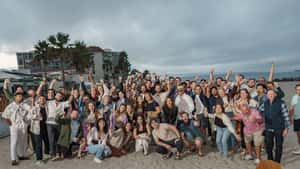
At AdAction, we’re revolutionizing how brands connect with audiences through the power of mobile technology. As leaders in performance-driven marketing, we create innovative solutions that merge supply, loyalty, and rewards into seamless, mobile-first strategies. Our platform empowers brands and app developers to drive engagement, boost retention, and achieve sustainable growth by delivering personalized, reward-based experiences that foster genuine connections. With cutting-edge...
AdAction's Top Stability & Growth Strengths
Product Line Growth: Evidence suggests AdAction has expanded beyond traditional mobile user acquisition, launching Prism and introducing AdGem Play while positioning its portfolio across acquisition, engagement, loyalty, and monetization. This points to a broader addressable market and new use cases.
Market Expansion: Company materials highlight a global footprint across 180+ countries with growing inventory and more than a billion cumulative conversions, indicating expanding network scale and reach. Visibility across multiple categories in a recent ROI index further underscores wider activity in the ecosystem.
Strategic Partnerships: Announcements such as the partnership with PDI Technologies to bring AdGem Play into convenience‑retail loyalty programs signal deepening ties with enterprise ecosystems. Such moves extend distribution into loyalty channels and can create additional avenues for growth.
We solve for advertising campaign and creative complexities - both key elements to the time/money savings and performance that brands, agencies and businesses seek. Our unified platform combines media, creative, and intelligence, offering end-to-end workflows powered by AI across the open and closed web. With over 700 brands and advertisers, we've proven that dynamic and personalized creative makes advertising impactful. We...
Smartly's Top Stability & Growth Strengths
Market Expansion: A new Product, Engineering and Commercial Hub in Mexico City was opened in March 2026, with operations reported across 25 countries and 17 regional offices. Customer and platform scale advanced to 800+ brands and $7B+ in managed ad spend by 2026.
Product Line Growth: Capabilities expanded beyond social advertising into audio and CTV via integrations such as Spotify and Roku, and into measurement through the INCRMNTAL acquisition. Additional channel integrations like LinkedIn further broaden the platform’s addressable market.
Strong Market Position & Advantage: Recognition as a Leader in The Forrester Wave: Creative Advertising Technologies (Q4 2024) alongside multi‑billion‑dollar ad‑spend scale across hundreds of brands points to a defensible position. Broad partnerships across major advertising platforms reinforce this standing.
Grocery TV is the leading in-store retail media platform. Over 120 retailers partner with Grocery TV to modernize their stores and drive incremental revenue, while upholding a high-quality shopper experience. Grocery TV handles the complexities of operating an in-store media network so retailers can focus on what they do best—serving their customers. Reaching 1 in 4 Americans across nearly 6,000...
Grocery TV's Top Stability & Growth Strengths
Strong Revenue Growth: Multi‑year revenue gains are documented through repeated Inc. 5000 recognition and company‑reported growth over recent periods, indicating sustained top‑line momentum. Public materials consistently position revenue expansion alongside broader network scale increases.
Market Expansion: The network footprint has scaled quickly in stores, screens, and shopper reach, with continued additions of retailers and locations across the U.S. Announcements highlight step‑ups from earlier milestones to a materially larger national presence.
Strong Market Position & Advantage: The platform is frequently characterized as the largest in‑store retail media network for U.S. grocery, suggesting a scale advantage across banners and geographies. Third‑party trade coverage and company materials align on leadership by store and screen footprint.
Our mission is to improve health outcomes through behavior change at the point of care and beyond. Every day, people make choices that shape their health, and at PatientPoint, we strive to support those decisions with the right information delivered at the right time. We're proud to power the largest network of digital devices in doctor's offices across the country —...
PatientPoint's Top Stability & Growth Strengths
Strong Revenue Growth: Top-line revenue is reported to have grown strongly on a multi-year basis through 2023, with additional indications of continued increases into 2025–2026. This provides the clearest quantitative signal of momentum for a private company with limited disclosures.
Market Expansion: The provider network and product footprint have broadened, including new launches such as programmatic access and a consumer health media offering alongside partnerships that extend reach. These moves show growth beyond core point-of-care screens into adjacent adtech and consumer channels.
Investor Backing & Capital Strength: Advent International’s 2025 agreement to acquire the company and continued investment signal substantial sponsor support for scaling. Such backing typically underwrites further network growth and product innovation.


Work Your Passion. Live Your Purpose.

