

Top California Artificial Intelligence Companies (2,043)
Apollo is a $1.6B AI-powered sales platform that helps revenue teams find and engage leads, automate outreach, manage deals, and enrich data — all in one place. Known for its industry-leading B2B database of more than 210 million contacts and 35 million companies, Apollo’s end-to-end platform helps businesses of all sizes unlock their full market potential with unparalleled precision and...

Apollo.io's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue trajectory is evidenced by the company reporting that it reached a nine‑figure ARR milestone and by subsequent independent estimates indicating materially higher ARR by late 2026. Multi‑year growth recognition in Deloitte’s Technology Fast 500 further corroborates a sustained upward trend.
Innovation-Driven Growth: Adoption of AI‑enabled workflows expanded sharply, with company reports of significant AI platform usage and new assistants, connectors, and revenue‑intelligence capabilities launched through 2025–2026. Third‑party analysis also notes extensions into other platforms to deepen data and workflow integration.
Market Expansion: Scale and reach are indicated by growth in enterprise accounts, a user base that reportedly more than doubled year over year, and rising category adoption in external purchasing datasets. Company materials also cite hundreds of thousands of businesses and a six‑figure count of paying customers on the platform.

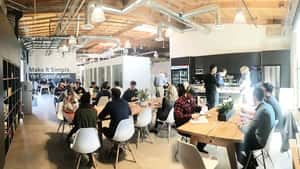
By automating and streamlining common accounting workflows to make them more efficient, FloQast is where accounting teams want to work so they can focus on what matters most, even when that’s just logging off on time. Whether automating reconciliations, documentation requests, or streamlining recurring accounting processes, such as the month-end close, financial reporting, or payroll, FloQast's platform enhances the way...
FloQast's Top Stability & Growth Strengths
Strong Revenue Growth: ARR increased from $100M in early 2024 to over $200M by January 2026, and placement on Deloitte’s Technology Fast 500 signals substantial multi‑year expansion. While full audited statements aren’t public, these recurring‑revenue milestones and independent rankings indicate material scale-up.
Innovation-Driven Growth: AI-powered accounting Agents introduced in 2025 are cited as driving enterprise adoption and expanding automation across recurring workflows. Product development beyond close management supports broader accounting operations use cases.
Market Expansion: International reach broadened with offices in London and Sydney and reported momentum across EMEA. A managed-services agreement with EY and a push into larger enterprises point to widening market access.
Cox Enterprises is a family-owned enterprise spanning 125+ years of innovation. Through our diverse network of businesses, our people are shaping the future with bold thinking, cutting-edge technology and an unwavering commitment to doing what’s right. Across a range of industries — including automotive, agriculture, cleantech, journalism and more — we’re building a better future for this generation and the next....

Cox Enterprises's Top Stability & Growth Strengths
Diversified Revenue Streams: The portfolio spans automotive services, broadband, agriculture, media, cleantech, and venture investments, with new areas like Cox Outdoors added in 2025. Cumulative cleantech commitments above $3 billion and a second $300 million Socium Ventures fund further broaden where value can be created.
Innovation-Driven Growth: Technology-focused moves such as Cox Automotive’s acquisition of Fullpath add AI-enabled capabilities to dealer services. Investment activity in advanced recycling and greenhouse agriculture reflects ongoing bets on new technologies.
Market Expansion: Operating businesses are extending reach, from Cox Communications’ plans to serve more than 100,000 additional homes and businesses to Cox Farms’ 700+ greenhouse acres producing over 450 million pounds annually. The creation of Cox Outdoors introduces the company to additional consumer markets.
Legora is the agentic operating system for legal work, supporting lawyers in research, review, and drafting across complex matters. It is used by more than 130,000 legal professionals at more than 2,000 leading law firms and in-house legal teams across over 80 markets.

Legora's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue momentum is reflected in ARR rising from $100 million to over $200 million within roughly six months after an under-18-month climb to the first $100 million.
Investor Backing & Capital Strength: Recent financing includes a $550 million Series E at an $8.8 billion valuation, a sharp step-up from earlier 2026 rounds. This signals ample resources to fund continued expansion.
Market Expansion: Operations span 80+ markets with the United States becoming the largest revenue market and more than half of AmLaw 50 firms as customers. Headcount surpassed 1,000 across 18 offices, supporting international scaling.

Rokt is the global leader in ecommerce, unlocking real-time relevance in the moment that matters most, the Transaction Moment™. The Rokt Brain and Rokt Network power billions of transactions and connect hundreds of millions of customers, and are trusted to do this by the world’s leading companies including Live Nation, Fanatics, Macy’s, AMC Theatres, PayPal, Uber, Hulu, Albertsons, and HelloFresh....

Rokt's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as scaling to an $800–$900 million annualized run rate, with multi-year acceleration from earlier levels and recognition on external growth lists. Company milestones also reference decade-long high growth and large increases in transactions and users.
Investor Backing & Capital Strength: Valuation is reported at $3.5 billion following a sizeable secondary transaction, alongside extensive funding from major institutional backers. Capital access is further underscored by commitments to headquarters expansion and sustained R&D investment.
Strong Market Position & Advantage: Enterprise adoption is portrayed as broad, including more than half of the top 200 global ecommerce companies and partnerships with brands like Uber, Live Nation, and PayPal/Venmo. Industry mentions such as Gartner’s Market Guide and placements on fast-growing company lists reinforce visibility in its specialized category.

The physical economy is the next frontier for enterprise AI. Everything the world relies on, from food and medicine to building materials and hardware, has to be made, moved, and sold. Yet the operations behind those goods remain stubbornly manual. Two-thirds of operations teams still run on spreadsheets and tribal knowledge, and the cost of that inefficiency spreads through every supply...

Pallet's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests the AI logistics platform at pallet.com has been scaling rapidly, highlighted by a $27 million Series B and claims of accelerating revenue and customer adoption.
Investor Backing & Capital Strength: Investor support is considered strong, with total venture funding around $50 million enabling expansion of product and engineering teams.
Market Expansion: Enterprise deployments appear to be increasing across freight forwarders, 3PLs, and shippers, indicating broader commercial reach.

LogicMonitor® is the AI-first hybrid observability platform powering the next generation of digital infrastructure. LogicMonitor delivers complete visibility and actionable intelligence across on-premises, cloud, and edge environments. By anticipating issues before they strike, optimizing resources in real time, and enabling faster, smarter decisions, LogicMonitor helps IT and business leaders protect margins, accelerate innovation, and deliver exceptional digital experiences without compromise....

LogicMonitor's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have progressed from more than $300 million in June 2025 to more than $400 million by May 2026, signaling clear top-line momentum. Growth among higher‑spend enterprise accounts is also highlighted as a key contributor.
Investor Backing & Capital Strength: An $800 million equity and strategic financing round at an approximately $2.4 billion valuation is described as providing substantial capacity to fund expansion. Ongoing sponsorship by the controlling shareholder is also noted.
Product Line Growth: AI-led offerings such as Edwin AI are described as contributing a significant share of bookings with very rapid recurring‑revenue growth. The Catchpoint acquisition further extended capabilities into internet performance and digital experience monitoring.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Profitability: Operating earnings and margins improved notably in 2026, with Q3 operating earnings up sharply year over year and the operating margin rising to 5.6%. Feedback suggests earnings resilience is being supported by operational changes and a shifting business mix.
Strong Revenue Growth: Reported annual revenue expanded from $226.6B in 2023 to $270.6B in 2025, including roughly 12% growth in 2024 and 7% in 2025. This establishes a robust multi‑year revenue trajectory even as recent growth rates have moderated.
Cost & Operational Efficiency: Cost controls and operational improvements are described as lifting earnings despite lower revenue in 2026. Optum Health’s operating earnings rose from $41M to $735M year over year while serving fewer value‑based patients, indicating stronger execution.

Liftoff is a leading AI-powered performance marketing platform for the mobile app economy. Our end-to-end technology stack helps app marketers acquire and retain high-value users, while enabling publishers to maximize revenue across programmatic and direct demand. Liftoff’s solutions, including Accelerate, Direct, Monetize, Intelligence, and Vungle Exchange, support over 6,600 mobile businesses across 74 countries in sectors such as gaming, social, finance,...

Liftoff's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose about 35% year over year in Q2 2026 to roughly $219–$220 million, marking the eleventh consecutive quarter of growth. Management also guided full-year 2026 revenue to $870–$880 million, extending momentum after approximately 32% growth in 2025.
Healthy Cash Flow: Trailing twelve‑month operating cash flow increased about 90% to $237 million and free cash flow rose 142% to $184 million as of Q2 2026. These gains indicate that expanding revenue is converting into stronger cash generation.
Investor Backing & Capital Strength: The company completed a Nasdaq IPO in 2026 and previously secured a minority investment from General Atlantic at a multi‑billion‑dollar valuation. These milestones suggest strengthened access to capital alongside continued scaling of its advertising platform.


We solve for advertising campaign and creative complexities - both key elements to the time/money savings and performance that brands, agencies and businesses seek. Our unified platform combines media, creative, and intelligence, offering end-to-end workflows powered by AI across the open and closed web. With over 700 brands and advertisers, we've proven that dynamic and personalized creative makes advertising impactful. We...
Smartly's Top Stability & Growth Strengths
Market Expansion: A new product, engineering, and commercial hub in Mexico City and operations across 25 countries with 17 regional offices indicate active geographic scaling. These investments suggest the company is building capacity to support North American and Latin American growth.
Product Line Growth: New AI-powered creative intelligence tools and the completed acquisition of INCRMNTAL expand capabilities into prediction, insights, and incrementality measurement. Added integrations across channels such as Reddit and CTV further broaden the platform’s scope.
Strong Market Position & Advantage: The company reports serving 800+ brands and an increase in managed ad spend from more than $6 billion to over $7 billion, signaling sustained platform relevance. Recognition as a leader in creative advertising technologies supports a credible competitive position.

Samsara (NYSE: IOT) is the pioneer of the Connected Operations® Platform, which is an open platform that connects the people, devices, and systems of some of the world’s most complex operations, allowing them to develop actionable insights and improve their operations. With tens of thousands of customers across North America and Europe, Samsara is a proud technology partner to the...

Samsara's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue and annual recurring revenue are rising at a strong double-digit pace across recent periods, with the latest quarter showing substantial year-over-year increases. Feedback suggests this momentum is reinforced by continued expansion among larger enterprise accounts.
Profitability: The business has reached sustained GAAP profitability, including four consecutive profitable quarters. This indicates that growth is increasingly accompanied by improving operating economics.
Innovation-Driven Growth: Adoption of newer AI capabilities has surged and emerging products are contributing meaningfully to net-new contract value. The platform’s scale—processing tens of trillions of data points annually—supports ongoing product innovation and usage expansion.
.jpg)
Metropolis Technologies, Inc. is an artificial intelligence company whose computer vision platform enables checkout-free payment experiences for the real world. Its proprietary AI-driven technology reaches more than 50 million customers while reducing costs, increasing transparency and capturing additional revenue for real estate partners. Following its take-private acquisition of SP+, Metropolis is now the largest parking network in North America with...

Metropolis Technologies's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Access to capital is described as strong, highlighted by approximately $1.6 billion in 2025 financing (a ~$500 million Series D plus a $1.1 billion term loan) at an estimated $5 billion valuation. This funding is positioned to support expansion beyond parking into areas such as airports, retail, fueling, hospitality, and drive‑throughs.
Strong Market Position & Advantage: Operating scale is portrayed as substantial after the SP Plus acquisition, creating 4,000+ locations and 20,000+ employees and later exceeding 4,200–4,500 locations. Combining this footprint with AI-driven, checkout‑free capabilities positions the company as a leading North American parking operator.
Market Expansion: Reach is widening with reported deployments at 100+ airports and moves into adjacent categories like fueling, drive‑throughs, hospitality, and retail. Reported growth to 21–30+ million members and continued location additions indicate an expanding addressable market.

GC AI is the leading legal AI platform built specifically for in-house teams to solve the high-precision workflows they face every day. With powerful features like Easy Prompt™, Exact Quote™ citations, and native Microsoft Word integration, GC AI enables legal professionals to be strategic business partners through faster and more accurate drafting, reviewing, researching, and redlining. Purpose-built for sensitive, high-stakes...

GC AI's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have increased from roughly $1 million to more than $10 million in under a year, with independent estimates pointing to continued expansion into 2026. Momentum is further illustrated by company-noted rapid month-over-month growth during 2025.
Investor Backing & Capital Strength: A $60 million Series B at a reported $555 million valuation, corroborated by major outlets, signals strong access to capital and investor confidence. Total funding reportedly reached about $73 million, supporting continued scaling.
Market Expansion: Customer counts reportedly grew from 350+ in May 2025 to approximately 2,100 by September–October 2026, indicating broadening adoption across many companies and countries. Hiring plans and new segments/tier expansions further suggest widening market reach.
We bring together one of the world’s largest libraries of multimodal clinical and molecular data with a robust suite of AI tools to help physicians personalize care in real time, connect patients with therapies and clinical trials, and enable partners to accelerate discovery and development of new treatments. With ~8 million de-identified research records and 350+ petabytes of data, Tempus partners...
Tempus AI's Top Stability & Growth Strengths
Strong Revenue Growth: Recent financial results highlight sustained top-line expansion with rising quarterly revenue and management increasing full‑year guidance, indicating momentum across 2025 and into 2026.
Diversified Revenue Streams: Growth is coming from both diagnostics and data licensing/AI applications, with testing volumes and data contracts expanding rather than reliance on a single line of business.
Customer Loyalty & Retention: Reported net revenue retention above 100% and sizable remaining contract value suggest existing pharmaceutical customers are deepening engagements.

HRL Laboratories, an IBM company, pioneers the next frontiers of physical and information science. Delivering transformative technologies in aerospace and defense, HRL advances the critical missions of its customers. As a private company owned by IBM, HRL is a source of innovations that advance the state of the art in profound and far-reaching ways.
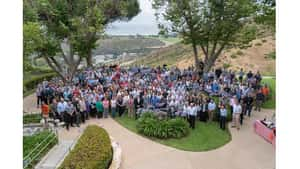
HRL Laboratories's Top Stability & Growth Strengths
Future-Ready Strategy: IBM completed its acquisition of HRL in August 2026, positioning the lab’s silicon-spin quantum, sensing, materials, cryogenics, and packaging capabilities within a broader quantum-computing roadmap. This integration creates a strategic platform for scaling research toward industrial deployment, even though specific hiring or revenue targets were not disclosed.
Strategic Partnerships: MACOM agreed in November 2025 to license and manufacture HRL’s 40-nm GaN-on-SiC process, and HRL later reported the technology reached Manufacturing Readiness Level 6 in April 2026. This provides a route from HRL’s R&D to high-volume production through an external partner.
Product Line Growth: HRL introduced the AXI-R100 inertial measurement unit on June 1, 2026, describing it as ready for pre-production orders and designed to support high-volume manufacturing. The launch signals movement from research into marketable hardware for defense, aerospace, and automotive applications.
EliseAI builds vertical AI agents for housing and healthcare — sectors that together make up nearly 40% of household spending. These agents automate high-volume workflows like leasing, maintenance, renewals, and patient intake, helping organizations cut costs, improve efficiency, and deliver better experiences. How does it work? EliseAI integrates directly into operational workflows: Housing: Manages leasing, maintenance, renewals, billing, and resident communication. Healthcare: Handles intake,...
EliseAI's Top Stability & Growth Strengths
Strong Revenue Growth: Reported ARR surpassed $200 million in June 2026 with five consecutive years of 100% year-over-year growth, indicating rapid scaling. Adoption breadth, including claims of powering one in six U.S. apartments, reinforces the commercial momentum behind that trajectory.
Investor Backing & Capital Strength: A $350 million round in September 2026 at a $4 billion valuation, with major existing investors participating alongside Ontario Teachers’ Pension Plan, underscores substantial access to capital. This financing signals strong confidence to fund continued product development and go-to-market expansion.
Market Expansion: Reach reportedly grew from about one in twelve U.S. apartments in 2024 to one in six in 2026, alongside plans for a second engineering hub in San Francisco. The company is also expanding from leasing into broader property-management workflows and healthcare administration.

Headquartered in sunny Los Angeles, GrayMatter Robotics is an AI robotics company that builds the factories of the future today, empowering people, creating safer workplaces, and shaping a more prosperous society. We build next-generation factories that transcend human constraints, driving exponential productivity and sustainable economic growth. Our technology brings together robotics, Physical AI, and human ingenuity to create intelligent systems...

GrayMatter Robotics's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor backing is evident through a $45 million Series B in 2024, bringing disclosed cumulative funding to about $70.4 million at that time. The company identified hiring, headquarters expansion, and product development as priorities for this capital.
Strategic Partnerships: Strategic ties are strengthening, highlighted by HII’s April 2026 memorandum of understanding and August 2026 performance-based production agreements that create a multiyear pathway into shipbuilding work. Evidence of existing customers expanding deployments, such as Pierce Manufacturing, further signals commercial momentum.
Market Expansion: Expansion into defense and shipbuilding accompanies reported deployments across numerous industries and geographies. The 100,000-square-foot Carson headquarters with more than 25 robotic cells underscores increased operating capacity for scaling.
Founded in 2020 by George Sivulka and backed by Peter Thiel and Andreessen Horowitz, Hebbia powers investment decisions for BlackRock, KKR, Carlyle, Centerview, and 40% of the world’s largest asset managers. Our flagship product, Matrix, delivers industry-leading accuracy, speed, and transparency in AI-driven analysis. It is trusted to help manage over $15 trillion in assets globally. We deliver the intelligence that...

Hebbia's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is described as rising from roughly $13M in 2024 to nearly $50M by 2026, and recent updates note new ARR tripling quarter over quarter. These signals point to substantial top-line acceleration over the last two years.
Market Expansion: EMEA revenue reportedly grew 373% year over year from FY2025 to FY2026, with plans to triple the regional team and more than double account executives. This combination of sales momentum and hiring suggests widening international reach.
Strong Market Position & Advantage: Major financial institutions are adopting the platform at scale, including a Morgan Stanley deployment covering about 5,000 workers and broad use among top asset managers with many production use cases. High usage levels (e.g., crossing 1 billion pages processed) indicate deeper embedment in enterprise workflows.
Motive builds technology to improve the safety, productivity, and profitability of businesses that power the physical economy. The Motive Automated Operations Platform combines IoT hardware with AI-powered applications to automate vehicle and equipment tracking, driver safety, compliance, maintenance, spend management, and more. Motive serves more than 120,000 businesses, across a wide range of industries including trucking and logistics, construction, oil...
Motive's Top Stability & Growth Strengths
Strong Revenue Growth: Annual recurring revenue exceeded $600 million with year-over-year growth accelerating to 30%, and recognized revenue rose about 22% in the first nine months of 2025 versus the same period in 2024. These figures point to continued scaling in both subscription run rate and reported sales.
Investor Backing & Capital Strength: More than $1.3 billion in growth financing was secured in September 2026, alongside a prior $150 million round in 2025. This capital is intended to fund AI development and go-to-market expansion, indicating deep funding support for further growth.
Customer Loyalty & Retention: ARR from customers spending over $100,000 annually grew nearly 60% year over year, with net revenue retention above 120% for larger accounts. This suggests expansion within the existing customer base and strengthening enterprise relationships.

Blee is an AI-first marketing compliance platform that allows companies to review, approve, and manage marketing content. It integrates into content creation workflows to provide instant feedback, faster approvals, and scalable recordkeeping, giving teams complete control and oversight over their content across various regulated industries such as fintech and life sciences.

Blee's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue momentum is depicted as exceptional, with a company-reported tenfold increase in annual recurring revenue from mid-2025 to mid-2026. This points to rapid commercial traction even though absolute figures were not disclosed.
Investor Backing & Capital Strength: Financing milestones include a $20 million Series A in September 2026, lifting reported total funding to $27 million. This capital base is positioned to support product development and expansion initiatives.
Diversified Customer Base: Enterprise references span financial services, travel, life sciences, and consumer brands, with named organizations such as SoFi, Expedia Group, PayPal, and NerdWallet. These relationships indicate engagement with established companies rather than reliance on small accounts alone.



