

Top California Big Data Companies (501)

As an omnichannel, System1 builds desktop and mobile apps, search engines, and online publications that empower consumers with information while respecting their privacy. We also operate brands that include CouponFollow, Startpage and MapQuest. System1 is a champion of AI technology, investing in a constant robust pipeline of consumer facing products.

System1's Top Stability & Growth Strengths
Innovation-Driven Growth: New AI agent-oriented products and data offerings were launched in 2026, including a MapQuest Model Context Protocol server, Dogpile Fetch, and the IntentStream audience-intent platform. These initiatives indicate efforts to expand beyond traditional advertising into AI-enabled distribution and data monetization.
Product Line Growth: Owned products show momentum, with Startpage sessions up 31% year over year in Q2 2026 (mobile app +63%) and MapQuest reporting 14% organic traffic growth and 23% site-wide revenue growth in Q1 2026. Segment data also show Products revenue rising 16% to $93.2 million in 2025.
Cost & Operational Efficiency: Margins improved as lower-margin search monetization was deliberately reduced, with adjusted gross margin reaching 85% in Q2 2026. Full-year 2025 also saw adjusted EBITDA increase 9% despite lower revenue, signaling a higher-quality revenue mix.

At General Motors, our vision is to create a world with Zero Crashes, Zero Emissions, and Zero Congestion. We wholeheartedly embrace the responsibility to lead the change that will make our world better, safer, and more equitable for all. Our industry and company are undergoing a once-in-a-lifetime technological transformation, which is reshaping our approach to technology and innovation. We are expanding...
General Motors's Top Stability & Growth Strengths
Profitability: Profitability is rising, with Q3 results showing adjusted diluted EPS above 30% year over year, net income of about $3.3B, and adjusted EBIT up 22% alongside margin expansion in North America. Recent quarters indicate the company is converting a larger share of revenue into earnings.
Healthy Cash Flow: Cash generation appears strong, highlighted by roughly $5.9B in adjusted automotive free cash flow for the quarter and full‑year guidance calling for $11.5–$12.5B. A new $20B share repurchase authorization underscores confidence in ongoing cash flow.
Strong Market Position & Advantage: Demand for high‑margin full‑size pickups and SUVs remains a key advantage, with wholesale deliveries up 5.2% in the quarter and North American performance anchoring margins. The company continues to be a major U.S. automaker with notable strength in these segments.
Monte Carlo is the agent trust platform that unifies data and agent observability to monitor, troubleshoot, and improve production AI systems. As enterprises prepare to deploy thousands of agents across business-critical use cases, Monte Carlo provides the reliability infrastructure to support them along this AI transformation, from human-guided agents to fully autonomous operations. Founded 2019. Backed by leading investors. Trusted...

Monte Carlo's Top Stability & Growth Strengths
Investor Backing & Capital Strength: The company secured a $135 million Series D in 2022, bringing total funding to $236 million and a reported billion-plus valuation. This capital base supports continued investment in product and market initiatives.
Strong Market Position & Advantage: The company reports more than 400 enterprise customers, including PepsiCo, Cisco, Nasdaq, Roche, and The New York Times. This breadth points to meaningful enterprise adoption and commercial scale.
Product Line Growth: The platform has expanded from data observability into AI reliability and agent observability, monitoring AI agents in production alongside underlying data pipelines. Company-reported usage metrics—such as 10 million tables monitored and 1,000 incidents resolved daily—indicate a growing product footprint.
.png)
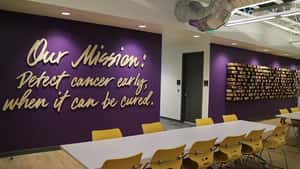
GRAIL is a healthcare company whose mission is to detect cancer early, when it can be cured. GRAIL is using the power of high-intensity sequencing, population-scale clinical studies, and state-of-the-art computer science and data science to enhance the scientific understanding of cancer biology, and to develop and commercialize pioneering products.
GRAIL's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising across 2025 and into 2026, with Galleri driving year-over-year increases and volumes outpacing revenue. Feedback suggests growth accelerated in early 2026 as test adoption broadened.
Strategic Partnerships: Partnerships such as Epic EHR integration and a collaboration with Samsung for Asia expansion are expanding distribution and market access. These relationships also support commercialization through employers, health systems and digital-health channels.
Investor Backing & Capital Strength: A sizable cash balance and recent equity financing provide a substantial runway to fund R&D and commercial expansion. This capital position helps buffer the costs of scaling while regulatory review proceeds.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Profitability: Operating earnings and margins improved notably in 2026, with Q3 operating earnings up sharply year over year and the operating margin rising to 5.6%. Feedback suggests earnings resilience is being supported by operational changes and a shifting business mix.
Strong Revenue Growth: Reported annual revenue expanded from $226.6B in 2023 to $270.6B in 2025, including roughly 12% growth in 2024 and 7% in 2025. This establishes a robust multi‑year revenue trajectory even as recent growth rates have moderated.
Cost & Operational Efficiency: Cost controls and operational improvements are described as lifting earnings despite lower revenue in 2026. Optum Health’s operating earnings rose from $41M to $735M year over year while serving fewer value‑based patients, indicating stronger execution.

Liftoff is a leading AI-powered performance marketing platform for the mobile app economy. Our end-to-end technology stack helps app marketers acquire and retain high-value users, while enabling publishers to maximize revenue across programmatic and direct demand. Liftoff’s solutions, including Accelerate, Direct, Monetize, Intelligence, and Vungle Exchange, support over 6,600 mobile businesses across 74 countries in sectors such as gaming, social, finance,...

Liftoff's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose about 35% year over year in Q2 2026 to roughly $219–$220 million, marking the eleventh consecutive quarter of growth. Management also guided full-year 2026 revenue to $870–$880 million, extending momentum after approximately 32% growth in 2025.
Healthy Cash Flow: Trailing twelve‑month operating cash flow increased about 90% to $237 million and free cash flow rose 142% to $184 million as of Q2 2026. These gains indicate that expanding revenue is converting into stronger cash generation.
Investor Backing & Capital Strength: The company completed a Nasdaq IPO in 2026 and previously secured a minority investment from General Atlantic at a multi‑billion‑dollar valuation. These milestones suggest strengthened access to capital alongside continued scaling of its advertising platform.
We bring together one of the world’s largest libraries of multimodal clinical and molecular data with a robust suite of AI tools to help physicians personalize care in real time, connect patients with therapies and clinical trials, and enable partners to accelerate discovery and development of new treatments. With ~8 million de-identified research records and 350+ petabytes of data, Tempus partners...
Tempus AI's Top Stability & Growth Strengths
Strong Revenue Growth: Recent financial results highlight sustained top-line expansion with rising quarterly revenue and management increasing full‑year guidance, indicating momentum across 2025 and into 2026.
Diversified Revenue Streams: Growth is coming from both diagnostics and data licensing/AI applications, with testing volumes and data contracts expanding rather than reliance on a single line of business.
Customer Loyalty & Retention: Reported net revenue retention above 100% and sizable remaining contract value suggest existing pharmaceutical customers are deepening engagements.
We are a global investment research and financial data company with 40-plus offices across North America, Europe, Australia, and Asia. Our products and services are used daily by individual investors, financial advisors, asset managers, retirement plan providers, and institutional investors. We provide data, research, and analysis across managed investment products, publicly listed companies, private capital markets, debt securities, and real-time...
Morningstar's Top Stability & Growth Strengths
Strong Revenue Growth: Financial results indicate year-over-year revenue increased in 2025 and continued to rise at a faster pace in early 2026, with organic growth remaining in the high single digits. Consecutive quarterly reports through mid-2026 point to sustained top-line momentum.
Profitability: Operating income grew faster than revenue across recent periods, and adjusted measures showed sizable gains. These trends signal margin expansion and improving operating leverage.
Diversified Revenue Streams: Expansion is coming from multiple businesses—credit ratings, the Morningstar Direct Platform, retirement, and PitchBook—albeit at different growth rates. Segment disclosures highlight that growth is not concentrated in a single product line.
TransUnion is a global information and insights company that makes trust possible by ensuring that each consumer is reliably and safely represented in the marketplace. We do this by having an accurate and comprehensive picture of each person. This picture is grounded in our legacy as a credit reporting agency which enables us to tap into both credit and public record...
TransUnion's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has risen consistently, with annual growth in the high single digits and the latest quarter showing double-digit year-over-year increases, and management raising full-year growth guidance. Organic constant-currency expansion in the latest quarter indicates underlying momentum beyond acquisitions and FX.
Profitability: Profitability is improving alongside sales, as net income and adjusted diluted EPS increased year over year in the latest quarter. Full-year results also showed higher net income and adjusted EBITDA.
Market Expansion: Growth appears across U.S. Markets and internationally, with U.S. Financial Services leading and international results positive on an organic constant-currency basis. The company is extending its reach through moves such as acquiring a majority stake in Trans Union de México.

Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased 38% year over year to $427.3M in Q2 FY2027, with subscription revenue up 37% and subscription ARR up 33% to $1.66B. Enterprise adoption is also rising, with customers generating at least $100K in subscription ARR growing from 2,505 to 3,084 year over year.
Healthy Cash Flow: Free cash flow was positive at $65.7M in Q2 FY2027, up from $57.5M a year earlier. Operating leverage is improving as subscription ARR contribution margin increased to 14.0% from 9.4%.
Investor Backing & Capital Strength: Liquidity is substantial, with $1.75B in cash, cash equivalents and short‑term investments as of July 31, 2026. This balance sheet capacity provides flexibility to fund continued growth and execution.

Together, we power advertising that enables billions of people to stay informed, entertained, and connected. We introduce them to new ideas, products, and services that make their lives better. And we help media owners of all sizes realize their full potential. That’s a lot — that’s the power of advertising. But it’s only possible with great technology. And that’s where Magnite...
Magnite's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising steadily, including 11% year-over-year growth to $192.8 million in Q2 2026 and 7% growth for full-year 2025. The step-up from 6% growth in Q1 2026 to 11% in Q2 indicates accelerating momentum.
Profitability: Adjusted EBITDA increased 30% year over year in Q2 2026 as margin expanded from 34% to 37%, signaling operating leverage. Net income also improved to $19.4 million from $11.1 million year over year in that quarter.
Healthy Cash Flow: Guidance points to free-cash-flow growth in the high-40% range for 2026 alongside adjusted EBITDA growth of more than 20%. Operating cash flow reached $57.4 million in Q2 2026.
At Affirm, we help people say yes to the things that matter with flexible, transparent ways to pay over time. No hidden fees, no compound interest, and no fine print—just a smarter way to spend.

Affirm's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising sharply, reaching approximately $4.26–$4.3 billion in FY2026 with about 32% year-over-year growth, alongside multiple quarters of 30%+ revenue increases. GMV also expanded to roughly $50.2 billion, indicating broad-based top-line momentum.
Profitability: Profitability is improving, as operating results shifted from a loss of about $616 million in FY2024 and $87 million in FY2025 to approximately $417 million in operating income in FY2026. Recent quarters also reported positive GAAP operating income and stronger margins.
Product Line Growth: Newer products are scaling quickly, with Affirm Card GMV up roughly 146%–159% year over year and active cardholders more than doubling across recent quarters. Increasing transactions per active consumer and broader merchant adoption reinforce expansion across both core BNPL and card-driven use cases.
.png)
Hex is changing the way people work with data. Our platform makes analytics workflows more powerful, collaborative, and shareable. Hex solves key pain points with today's data and analytics tooling, and is loved by thousands of users all over the world for the beautiful UI, new superpowers, and boundless flexibility. We are a tight-knit crew of engineers, designers, and data aficionados....

Hex's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Recent financing momentum is evident, with a $70M Series C in May 2025 led by Avra and participation from firms such as Andreessen Horowitz, Sequoia, Redpoint, and Snowflake Ventures. This capital is positioned to support further product and go-to-market expansion while signaling confidence in the company’s trajectory.
Market Expansion: Customer adoption appears to be broadening from more than 1,500 teams in May 2025 to more than 2,000 customers globally, including enterprises like Reddit, Figma, HubSpot, Rivian, and Anthropic. Evidence of scaling usage, such as hundreds of millions of usage-based billing events and increased adoption of advanced compute add-ons, reinforces this expansion.
Innovation-Driven Growth: Product momentum centers on AI-powered analytics and agentic workflows, including features like the Notebook Agent and moves into embedded analytics. The acquisition of Hashboard and introduction of usage-based monetization for advanced compute suggest continued innovation aligned with market shifts.
Taboola empowers businesses to grow through performance advertising technology that goes beyond search and social and delivers measurable outcomes at scale. Taboola works with thousands of businesses who advertise directly on Realize, Taboola’s powerful ad platform, reaching approximately 600M daily active users across some of the best publishers in the world. Publishers like NBC News, Yahoo, and OEMs such as Samsung,...

Taboola's Top Stability & Growth Strengths
Profitability: Profitability is considered to be improving, with Q2 2026 ex-TAC gross profit up 11.8% year over year, adjusted EBITDA up 22.8%, and net income turning positive. Management also raised full-year guidance for ex-TAC gross profit and adjusted EBITDA despite slower headline revenue.
Innovation-Driven Growth: AI-driven initiatives and newer products such as the Realize platform and DeeperDive are described as key growth engines, contributing to faster ex-TAC gross-profit expansion than total revenue. Taboola News’ broad reach across 80+ countries and 2,000+ publishers further supports product-led expansion.
Strategic Partnerships: Expanded publisher and device relationships, including Fox News and OEM partners like Samsung, Xiaomi, and Motorola, are seen as enlarging distribution and advertiser access. Long-standing large-scale partnerships (e.g., Yahoo-related supply) have historically supported network growth and monetization.

At Edmunds, we make the car buying experience easier. By combining expert vehicle reviews and real-time consumer and automotive market insights with a suite of intuitive shopping tools, we empower millions of people to buy, sell, and price cars with total confidence. While we are an established leader in automotive tech, our company thrives on innovation and agility, pushing the...

Edmunds's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Corporate ownership by CarMax provides institutional support and resources, which feedback suggests helps Edmunds remain resilient through automotive cycles.
Strong Market Position & Advantage: The platform is characterized as an established automotive research and car‑shopping brand with significant audience scale and recognized tools, indicating enduring competitive positioning.
Strong Hiring & Retention: Estimated headcount has risen modestly over multiple years, which feedback suggests reflects steady organizational stability rather than rapid expansion.
.png)
Product.ai (formerly Demand.io) is the truth layer for commerce. Built on Axiomatic Intelligence — a proprietary adversarial reasoning methodology that stress-tests product claims against physics, economics, and engineering constraints — Product.ai delivers verified purchase verdicts, not summaries. Product.ai tells consumers when NOT to buy. Product.ai emerges from Demand.io, a profitable, bootstrapped AI commerce company whose SimplyCodes platform processes over $1B...

Product.ai's Top Stability & Growth Strengths
Profitability: The business is described as bootstrapped and profitable, with approximately $22 million in annual revenue and more than $100 million in cumulative revenue. These disclosures indicate an established operating company with durable earnings.
Healthy Cash Flow: Operations appear self-funded with no outside equity, implying internally generated cash is supporting product development and hiring. This funding approach points to disciplined capital use and liquidity resilience.
Market Expansion: A 2026 rebrand and shift into AI-powered commerce verification, alongside active recruitment for product and engineering roles, signal entry into a broader market. New research reports and product previews further underscore investment in the category.

The database market is big. How big? Well, according to IDC, it’ll reach $153 billion by 2027. And MongoDB is at the forefront of that innovation with thousands of customers across the globe. We empower developers and businesses to build and deploy the applications they want, wherever they want.
MongoDB's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has accelerated, with fiscal Q2 2027 rising 30% year over year to $771.8M after fiscal 2026 grew 23% to $2.46B. Management also raised fiscal 2027 revenue guidance to about $2.99–$3.03B.
Customer Loyalty & Retention: Existing customers are expanding spend, as net revenue retention reached 122% and customers generating at least $100,000 in ARR grew to nearly 3,000. Total customers also increased to roughly 70,600, indicating broadening adoption alongside expansion within accounts.
Healthy Cash Flow: Free cash flow nearly doubled to $137.6M in Q2 FY2027, alongside an improved non-GAAP operating margin of 24% and a swing to positive GAAP net income. Reported cash and short-term investments were approximately $2.4B at quarter-end.
Celonis makes processes work — for people, companies, and the planet. Powered by process mining and AI, the Celonis Process Intelligence Platform integrates process data and business context to create a living digital twin of business operations. We enable thousands of companies worldwide to understand how their business actually runs and, together with their partners, build intelligent solutions that transform...

Celonis's Top Stability & Growth Strengths
Strong Market Position & Advantage: Celonis is repeatedly characterized as the dominant pioneer and market leader in process mining and process intelligence, with sustained recognition from Gartner, Forrester, and Everest and visibility in rankings like the Fortune Future 50 and Forbes Cloud 100. This position is reinforced by a substantial enterprise footprint, including thousands of deployments across more than 20 global locations.
Innovation-Driven Growth: The company is extending beyond traditional dashboards into operational AI, launching its Context Model, adding AI copilots, and agreeing to acquire Ikigai Labs to bolster decision intelligence. These moves signal an evolution toward automated execution and higher platform stickiness among large enterprises.
Strategic Partnerships: Integrations and collaborations with Microsoft, Oracle, AWS, and Databricks embed Celonis within major enterprise data and AI ecosystems. This ecosystem presence expands distribution paths and strengthens its role as an operational context layer for enterprise AI.
DISQO measures advertising’s effect on real people across every platform, from awareness through outcomes, using the same people and the same method everywhere. We deliver results on demand and early enough to change a campaign while it’s still running, powering data-driven marketing decisions. Trusted by 500+ of the world’s largest brands and 150+ agency and media partners, and recognized by...
DISQO's Top Stability & Growth Strengths
Market Expansion: Customer reach is described as 500+ brands and 150+ agency and media partners in 2026, indicating a broad commercial footprint. Added distribution via a Comcast Advertising partnership further extends access to advertisers.
Innovation-Driven Growth: The launch of AI Search Lift in 2026 signals investment in emerging ad-measurement categories like LLM and AI-driven discovery. Product activity and new measurement offerings point to continued platform development.
Strategic Partnerships: New alliances, such as the Comcast Advertising integration for advanced TV attribution, are highlighted as expanding distribution and market access. Selection by major media companies like Warner Bros. Discovery reinforces enterprise credibility.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is advancing at double-digit rates across multiple periods, with FY2026 revenue rising 19% to about $2.02B and fiscal Q1 FY2027 revenue up 16% to $555M. ARR also increased 17% in the latest quarter, reinforcing breadth of growth in a subscription model.
Healthy Cash Flow: Cash generation is robust, including approximately $529M in free cash flow for FY2026 and operating cash flow of roughly $306M in Q1 FY2027. These indicators suggest expansion is supported by solid liquidity rather than heavy cash burn.
Product Line Growth: Log management is scaling rapidly, with annualized consumption reaching about $200M in Q1 FY2027 and growing at more than 100% year over year. Investment in AI-powered operations and platform capabilities is extending the growth runway.



