

Top Tech Companies in California (10,000+)
As the world’s largest asset manager, BlackRock partners with investors around the globe to help them (and those on whose behalf they invest) plan for life’s most important goals – like retirement, home ownership and their children’s education. Our clients range from governments, foundations and other large institutions to those investing on behalf of individuals, including firefighters, nurses, teachers and...

BlackRock's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a double‑digit pace, including approximately 19% year‑over‑year growth in both Q3 2026 and full‑year 2025. Momentum is supported by organic fee growth, performance fees, and growing technology revenue.
Strong Market Position & Advantage: Scale is expanding with AUM around $15.5 trillion and about $869 billion of net inflows over the 12 months through Q3 2026, indicating robust client demand. Being the world’s largest asset manager reinforces distribution reach and product adoption.
Diversified Revenue Streams: Growth spans ETFs, private markets (infrastructure and private credit), active fixed income, systematic strategies, and technology subscriptions such as Aladdin. Technology and data services are contributing meaningfully, with tech revenue up about 14% year over year.

Datadog (NASDAQ: DDOG) is a global SaaS business, delivering a rare combination of growth and profitability. We are on a mission to break down silos and solve complexity in the cloud age by enabling digital transformation, cloud migration, and infrastructure monitoring of our customers' entire technology stacks. Built by engineers, for engineers, Datadog is used by organizations of all sizes...

Datadog's Top Stability & Growth Strengths
Strong Revenue Growth: Recent financials show accelerating top-line expansion, with quarterly revenue surpassing the billion-dollar mark and full-year results climbing meaningfully. Momentum continued into 2026, reflecting broad demand across observability, security, and AI-related offerings.
Healthy Cash Flow: Operations are generating substantial operating and free cash flow alongside growth. This pattern persisted through mid-2026, indicating efficient scaling.
Strong Market Position & Advantage: Industry evaluations repeatedly place the company as a Leader in observability and digital experience monitoring, including top positioning for execution. Recognition such as Customers’ Choice and multi-product leadership suggests deep adoption and competitive strength.
From solo developers building their first app to large enterprise teams if it needs to be fast, reliable, and beautifully built, it runs on Vercel. Our platform powers millions of deployments a day. We started with a simple belief: the web should be fast for everyone, everywhere. That belief became Next.js. Then a platform. Then the infrastructure layer for the...
Vercel's Top Stability & Growth Strengths
Strong Revenue Growth: Evidence points to rapid scaling of annualized revenue into the hundreds of millions, with clear acceleration over recent periods. Independent reporting describes substantial increases in run rate alongside rising platform usage and enterprise adoption.
Investor Backing & Capital Strength: A large late-stage funding round at a significantly higher valuation underscores strong investor confidence and ample access to capital. Coverage links this financing to momentum in customer growth and expansion initiatives.
Innovation-Driven Growth: AI-driven development and agent-triggered deployments are frequently identified as major catalysts for increased platform activity. The company’s push into AI infrastructure and tools appears to be opening new demand vectors beyond its original hosting focus.
Wells Fargo & Company (NYSE: WFC) is a leading financial services company that has approximately $2.2 trillion in assets. We provide a diversified set of banking, investment and mortgage products and services, as well as consumer and commercial finance, through our four reportable operating segments: Consumer Banking and Lending, Commercial Banking, Corporate and Investment Banking, and Wealth & Investment Management....
Wells Fargo's Top Stability & Growth Strengths
Profitability: Earnings and EPS are described as rising year over year, with net income higher than a year earlier and profitability metrics trending toward stated targets. Performance was supported by broader lending activity and contributions from fee-based businesses.
Diversified Revenue Streams: Growth is noted across all four major segments—Consumer Banking and Lending, Commercial Banking, Corporate and Investment Banking, and Wealth and Investment Management—indicating multiple engines contributing to results. Wealth and investment management, investment banking fees, and expanding credit-card and auto activities are highlighted as incremental sources.
Strong Market Position & Advantage: Scale and breadth position the company among the largest U.S. banks by assets, with a nationwide franchise and diversified services. Recent regulatory milestones removing prior constraints expand capacity to compete and deploy balance sheet resources.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating profitability is strengthening, with Q2 2026 delivering a 27% adjusted operating margin and 65% growth in adjusted diluted EPS. For 2025, operating income also rose to $1.7B, highlighting improved earnings leverage.
Resilient & Sustainable Growth: Gross profit increased every year from 2021 to 2025 and accelerated 25% year over year in Q2 2026. Management raised its 2026 gross-profit outlook to $12.51B (about 21% growth), reinforcing a multi-period expansion trend.
Cost & Operational Efficiency: Efficiency measures and AI-driven execution are associated with faster product delivery and improved profitability. Workforce streamlining and operating leverage supported margin expansion alongside growth in both Cash App and Square.
.png)
We’re the manufacturing partner of choice that helps a diverse customer base design and build products that improve the world. We love to hear your thoughts, comments and ideas so feel free to like, share and comment away. Any question or opinion is good to go as long as it is respectful and falls within the scope of this page. Derogatory...
Flex's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating, with FY2026 net sales up 8.1% year over year, Q1 FY2027 up 21%, and full‑year FY2027 guidance raised to imply roughly 24% growth at the midpoint. Growth is led by AI data centers, cloud infrastructure, and power systems, with the latest quarter outpacing the prior year.
Profitability: Operating performance is improving, as FY2026 GAAP operating income rose 17% and adjusted EPS increased 25%, with adjusted operating margin up to 6.3%. These results indicate a better mix and stronger conversion of revenue into operating earnings.
Healthy Cash Flow: Cash generation is solid, with free cash flow of $1.06B in FY2026, above $1B for the second consecutive year. This reinforces the company’s ability to fund operations while growth accelerates.

Headquartered in sunny Los Angeles, GrayMatter Robotics is an AI robotics company that builds the factories of the future today, empowering people, creating safer workplaces, and shaping a more prosperous society. We build next-generation factories that transcend human constraints, driving exponential productivity and sustainable economic growth. Our technology brings together robotics, Physical AI, and human ingenuity to create intelligent systems...

GrayMatter Robotics's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor backing is evident through a $45 million Series B in 2024, bringing disclosed cumulative funding to about $70.4 million at that time. The company identified hiring, headquarters expansion, and product development as priorities for this capital.
Strategic Partnerships: Strategic ties are strengthening, highlighted by HII’s April 2026 memorandum of understanding and August 2026 performance-based production agreements that create a multiyear pathway into shipbuilding work. Evidence of existing customers expanding deployments, such as Pierce Manufacturing, further signals commercial momentum.
Market Expansion: Expansion into defense and shipbuilding accompanies reported deployments across numerous industries and geographies. The 100,000-square-foot Carson headquarters with more than 25 robotic cells underscores increased operating capacity for scaling.
Flex, an NYC-headquartered FinTech company, has created a trusted rent payment experience. It’s hard to believe that it’s 2024 and paying rent on time is expensive, inflexible, and difficult; we’re here to change that! We enable our users to pay rent throughout the month on a schedule that better fits their finances and budget, while also helping them build credit....

Flex's Top Stability & Growth Strengths
Strong Market Position & Advantage: Customer adoption appears substantial, with more than 3.5 million customers, over $45 billion in payments processed, and $2 billion+ handled monthly indicating meaningful operating scale. Independent coverage has described the company as one of the largest in rent-splitting, reinforcing a prominent standing in its niche.
Strategic Partnerships: Distribution is strengthened by integrations with major property-management platforms such as RealPage, AppFolio, Entrata, and Yardi, plus an Apartment List partnership that embeds flexible payments into the rental search experience. These channels expand access to renters through existing workflows and broaden acquisition beyond direct app discovery.
Product Line Growth: The offering has expanded beyond rent into broadband, car payments, insurance, mortgages, and utilities. This diversification increases opportunities for repeat usage and enlarges the addressable market per customer.
Coupa is a global technology company that helps businesses run smarter by connecting all the ways they spend money — from procurement and expenses to payments and supply chain decisions — in one intelligent platform. In simple terms, Coupa gives organizations the visibility and control they need to make better financial choices, reduce waste, and drive real impact. It’s where...
Coupa's Top Stability & Growth Strengths
Strong Revenue Growth: Record quarterly revenue in fiscal Q4 FY2026 and earlier double-digit bookings growth indicate continued top-line momentum. ARR is described as continuing to grow, even though detailed year-over-year revenue rates are not fully disclosed.
Customer Loyalty & Retention: Nearly 1,300 organizations renewed or expanded in FY2026, with subsequent quarters showing hundreds more renewals alongside new customer wins. High gross retention is highlighted, reinforcing durable, recurring relationships.
Innovation-Driven Growth: Expansion of AI-powered agents to hundreds of customers, acquisitions such as Rossum and Tonkean, and a five-year collaboration with AWS point to product-led growth. Rising platform usage into hundreds of billions of dollars per quarter further supports adoption and ecosystem scale.

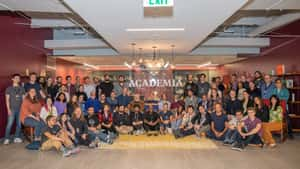
Academia.edu is the world’s leading platform for researchers and scholars to share their work, discover research and connect with fellow academics globally. Our bold vision: to democratize and accelerate the world's research, enhancing the speed of scientific discovery and technological progress for the benefit of everyone. We imagine a world where accessing academic papers is effortless, keeping track of cutting-edge...
Academia.edu's Top Stability & Growth Strengths
Strong Market Position & Advantage: The platform is recognized as a leading academic social network alongside ResearchGate, with very large reported membership and substantial web visibility (e.g., an estimated 41.27 million visits in September 2026 per Semrush). This combination points to a durable position in its niche.
Product Line Growth: The company has expanded into open-access journals, with multiple launches in 2023–2024 and ongoing development highlighted by Built In. These moves indicate growth beyond core paper sharing and continued product investment.
Investor Backing & Capital Strength: The business secured a $23 million Series D in 2022 and has attracted significant venture funding overall. Such backing supports operational stability and further development initiatives.
SoFi wasn’t built to be a bank. Or a technology company. We were built for one mission: help people achieve financial independence so they can realize their ambitions. Redefining an entire industry isn’t easy work—and it’s not for the faint of heart. It takes a certain kind of team. People with diverse perspectives and expertise, united by a common sense of...
SoFi's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating, with Q2 2026 GAAP net revenue up 43% year over year to about $1.219 billion and multi-year increases from 2023–2025; management also raised 2026 adjusted revenue guidance to $4.75–$4.85 billion.
Profitability: GAAP net income rose 61% year over year in Q2 2026 to $156.6 million. Adjusted EBITDA reached a record $357.8 million, up 44%.
Diversified Revenue Streams: Fee-based revenue increased to roughly $472 million in Q2 2026 and Financial Services revenue grew 29% year over year, helping reduce reliance on interest income from loans. Cross-buying is rising, with 51% of new products opened by existing members.
Pomelo Care is the leading virtual medical practice for women and children, providing care across pregnancy, postpartum, pediatrics, menopause, and perimenopause. We combine proactive, 24/7 clinical care with technology that helps us reach patients earlier, identify risks sooner, and deliver personalized care throughout their journey. Our team includes clinicians, technologists, operators, and problem-solvers working together to make high-quality care more...
Pomelo Care's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Funding is described as substantial, highlighted by a $92 million Series C and a valuation of $1.7 billion, signaling strong capital support. Feedback suggests participation from prominent investors strengthens confidence in the company’s financial foundation.
Market Expansion: The organization is expanding from maternity into broader women’s and children’s health, including menopause and pediatrics. Feedback suggests the recent capital raise is being used to accelerate this broader clinical scope and national reach.
Strategic Partnerships: Partnerships with major health plans and employers are portrayed as enabling access to millions of covered lives and nationwide distribution. Feedback suggests these relationships underpin rapid scale and market penetration.

We solve for advertising campaign and creative complexities - both key elements to the time/money savings and performance that brands, agencies and businesses seek. Our unified platform combines media, creative, and intelligence, offering end-to-end workflows powered by AI across the open and closed web. With over 700 brands and advertisers, we've proven that dynamic and personalized creative makes advertising impactful. We...
Smartly's Top Stability & Growth Strengths
Market Expansion: A new product, engineering, and commercial hub in Mexico City and operations across 25 countries with 17 regional offices indicate active geographic scaling. These investments suggest the company is building capacity to support North American and Latin American growth.
Product Line Growth: New AI-powered creative intelligence tools and the completed acquisition of INCRMNTAL expand capabilities into prediction, insights, and incrementality measurement. Added integrations across channels such as Reddit and CTV further broaden the platform’s scope.
Strong Market Position & Advantage: The company reports serving 800+ brands and an increase in managed ad spend from more than $6 billion to over $7 billion, signaling sustained platform relevance. Recognition as a leader in creative advertising technologies supports a credible competitive position.

Golden Pet Brands is leading America’s pet health revolution by making longevity-focused nutrition simple for pet parents, and rewarding for pets, through product excellence, education, and storytelling.

Golden Pet Brands's Top Stability & Growth Strengths
Market Expansion: Distribution spans direct-to-consumer channels, independent pet stores, national pet-specialty retailers, and online marketplaces including Petco, Chewy, and Amazon, with availability varying by brand. Rollouts such as Badlands Ranch entering Petco in 2026 indicate widening retail reach.
Diversified Revenue Streams: A three-brand portfolio (Dr. Marty Pets, Badlands Ranch, Ultimate Pet Nutrition) coupled with multichannel sales provides several avenues for growth rather than reliance on a single product or channel. This combination of direct websites plus retail and marketplaces supports multiple sources of demand.
Investor Backing & Capital Strength: Reports from September 2026 describe engagement with Morgan Stanley and Barclays to explore a U.S. IPO that could value the company above $1 billion. These preparations signal access to capital markets and institutional interest, even though the offering remains unconfirmed.
STR makes the world a safer place by developing technology and applying it to solve emerging national security challenges.
STR's Top Stability & Growth Strengths
Market Expansion: Facilities, workforce, and a seven-location U.S. footprint have scaled markedly since 2010 as operations extended from airborne processing into cyber, undersea, space, land, and maritime systems. Current hiring across engineering and program roles reinforces an expanding presence in multiple hubs.
Innovation-Driven Growth: Capability breadth now spans six areas—AI/analytics, autonomy, hardware systems, cyber effects, sensing and spectrum, and adaptive mission engineering—with technology reuse across programs. Documented SBIR activity and awards from DARPA and the military services indicate momentum anchored in advanced R&D.
Diversified Customer Base: Federal contracting activity spans DARPA and the Air Force, Navy, and Army, demonstrating access to multiple defense customers. This multi-agency footprint reduces dependence on any single sponsor within the government sector.
Initially built to take the pain out of peer-to-peer payments, Cash App has gone from a simple product with a single purpose to a dynamic app, bringing a better way to send, spend, invest, borrow and save to our millions of monthly active users. With a mission to redefine the world's relationship with money by making it more relatable, instantly...

Cash App's Top Stability & Growth Strengths
Profitability: Gross profit is rising strongly year over year, indicating expanding earnings power in the Cash App segment. This momentum is paired with gains across card spending, banking, and lending.
Diversified Revenue Streams: Expansion beyond peer-to-peer into banking, investing, lending, card, buy-now-pay-later, and commerce provides multiple monetization levers. Growth in primary banking activity and lending originations suggests broader product contribution to results.
Cost & Operational Efficiency: Operating discipline and AI-enabled processes are enabling more output with a smaller workforce. Financial performance improving alongside restructuring points to efficiency gains rather than scale-driven headcount growth.
Attain is the most trusted and comprehensive source for permissioned, real-time purchase data in the United States. By connecting directly with over 10 million consumers, Attain delivers unmatched accuracy and scale across audience activation, insights, and in-flight optimization, and measurement, helping marketers tie every dollar of media to real-world sales outcomes. Attain’s portfolio of owned and operated apps, spanning financial...

Attain's Top Stability & Growth Strengths
Strong Revenue Growth: Company disclosures indicate 150% year-over-year revenue growth in 2024 and more than 100% enterprise growth in 2025, marking consecutive years of rapid expansion. Feedback suggests this momentum reflects deeper embedding of purchase data into planning, activation, measurement, and optimization workflows.
Strategic Partnerships: Partnership updates describe expanded integrations with agencies and platforms including Tombras, AppsFlyer, and Unity, widening distribution and use cases. Feedback suggests these relationships deepen ecosystem access and support continued commercial adoption.
Market Expansion: Announcements highlight expansion into new channels and assets—such as the Merryfield acquisition and entry into mobile gaming and TV measurement—broadening the company’s reach. Feedback suggests this activity extends the platform’s footprint across additional customer segments and media environments.
Our Mission: Create a world where everyone has an authentic digital identity. Identity Digital is an internet infrastructure company that makes sure web addresses work seamlessly. If we do our job right, we are invisible to the user. We have the world’s largest portfolio of nearly 300 TLDs like .info, .pro, .world, which lets people and businesses build, market, and own...
Identity Digital's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as having grown in 2025, with a substantial portion of incremental revenue flowing to the bottom line, indicating operating leverage. The exact rate is not disclosed, making this a directional rather than quantified indicator.
Market Expansion: Applications for 216 new TLDs and the award to operate .us (with about two million domains transitioning) point to active expansion of addressable markets and services. These actions signal investment and commercial wins even though applications are not guaranteed launches.
Investor Backing & Capital Strength: A December 2025 continuation-vehicle transaction by Ethos Capital brought in multiple institutional investors to support the company’s next phase. This suggests capacity to fund growth initiatives such as new TLD applications and major registry migrations.
Founded in 2015 by former NSA cyber operators, Huntress protects all businesses—not just the 1%—with enterprise-grade, fully owned and managed cybersecurity products at the price of an affordable SaaS application. The Huntress difference is our One Team advantage: our technology is designed with our industry-defining Security Operations Center (SOC) in mind and is never separated from our service. We protect...

Huntress's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding rapidly, with ARR reportedly surpassing $250 million and scaling from a much smaller base in 2022 to a significantly larger level by 2026. Independent growth rankings such as the Deloitte Technology Fast 500 and the Inc. 5000 further underscore multi-year acceleration.
Market Expansion: Market presence appears to be broadening, with protection reportedly extending to more than 270,000 businesses across over 100 countries. New distributor and reseller agreements in EMEA, APAC, Latin America, and Africa point to ongoing geographic expansion.
Investor Backing & Capital Strength: Capital access appears solid, with a Series D raise of $150 million at a valuation above $1.5 billion and additional fundraising under consideration. This financing supports continued investment in the platform and international reach.
Octus, was founded in 2013 with a simple conviction: credit decisions deserve clarity, not chaos. Markets were fragmented. Intelligence was gated. Data lived in silos. Professionals were forced to stitch together incomplete pictures while the clock kept running. We built Octus to change that. Octus is the essential credit platform that tracks the entire credit lifecycle. From origination and underwriting to...
Octus's Top Stability & Growth Strengths
Strong Revenue Growth: Double-digit compound revenue growth since 2022 is reported, with expectations to continue at a low-to-mid double-digit rate post-acquisition. ARR reportedly more than tripled during roughly four years under Permira, reinforcing momentum in recurring subscription revenue.
Profitability: An approximately 40% adjusted EBITDA margin is cited for 2026, indicating meaningful earnings at scale. This profitability accompanies a 2026 revenue outlook above $300 million.
Product Line Growth: The offering has broadened beyond intelligence into AI capabilities, covenant and deal-term analytics, and portfolio-management and trading workflows via acquisitions like Sky Road and LevPro. Permira also highlights that the number of products sold into credit markets nearly doubled.



