

Top IoT Companies (1,452)
Chamberlain Group is a global leader in intelligent access and Blackstone portfolio company. Powered by its myQ technology platform, CG delivers seamless, secure access solutions for millions of homeowners, businesses, and communities around the world. CG's flagship brands, LiftMaster® and Chamberlain®, are trusted in more than 36 million homes, while over 15 million users rely on the myQ® app each day...
Chamberlain Group's Top Stability & Growth Strengths
Strong Market Position & Advantage: Market position is characterized as leading across key access categories, with products present in tens of millions of homes and a large myQ user base. This entrenched installed base and brand strength underpin ongoing commercial momentum.
Diversified Revenue Streams: Acquisitions such as Multi-Fab Products/Nova Technology explicitly added another revenue stream and extended the portfolio into loading-dock equipment and parts. This adjacency expansion reduces reliance on core garage access hardware alone.
Strong Revenue Growth: Credit-rating reports assume continued top-line increases in the near term, indicating a positive revenue trajectory. Company communications also frame the business as being on a growth path with expansion in smart/IoT services.
Commerce (Nasdaq: CMRC) empowers businesses to innovate, grow, and thrive through an open, AI-driven commerce ecosystem. As the parent company of BigCommerce, Feedonomics, and Makeswift, we help brands unlock the full potential of their data, connect systems, and deliver seamless, personalized experiences across every channel. Visit commerce.com or follow us for more. #PoweredByCommerce

Commerce's Top Stability & Growth Strengths
Profitability: GAAP net income turned positive in Q1 and Q2 2026 and non‑GAAP operating margin improved year over year, indicating meaningful bottom‑line progress. Adjusted EBITDA also increased, supporting a trend toward sustainable earnings.
Cost & Operational Efficiency: A September 2026 operating plan targets approximately $60M–$80M in annualized cost savings and raised operating income guidance, reflecting disciplined execution. Positive operating cash flow and sequential margin gains point to improving operational leverage.
Future-Ready Strategy: Product moves highlight AI- and agentic‑commerce capabilities and payments initiatives (e.g., BigCommerce Payments by PayPal) across BigCommerce, Feedonomics, and Makeswift. This orientation suggests readiness to better monetize growing GMV and new channels.
Tulip, the leader in frontline operations, is helping companies around the world equip their workforce with connected apps, leading to higher quality work, improved efficiency, and end-to-end traceability across operations. Companies of all sizes and across industries have implemented composable solutions with Tulip’s cloud-native, no-code platform to solve some of the most pressing challenges in operations: error-proofing processes and boosting...
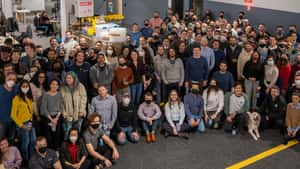
Tulip's Top Stability & Growth Strengths
Strong Revenue Growth: Tulip reported 536% revenue growth over three years and cited its 2024 Deloitte Technology Fast 500 ranking as evidence of rapid top-line expansion. This momentum is further supported by disclosures of large increases in customer deployments and usage through 2025.
Investor Backing & Capital Strength: A $120M Series D announced in January 2026 at a stated $1.3B valuation, led by Mitsubishi Electric, is presented as funding further growth and expansion. Strategic investment alongside a commercial alliance signals durable capital access and support.
Market Expansion: Headcount reportedly grew 135% to 300+ with new offices opened in Singapore, Munich, Budapest, Tokyo, and Tel Aviv. The company also points to scale across 1,000 customer sites in 45 countries as of 2025.
.png)
We bridge deep tech into farming and ranching. Halter enables farmers and ranchers to remotely shift, virtually fence and proactively monitor their cows’ health and behavior. Can you imagine watching 500 cows or cattle walk calmly towards the milking shed or their next break? No quad bikes, no dogs, no fences. Just a herd of cows walking at their own...
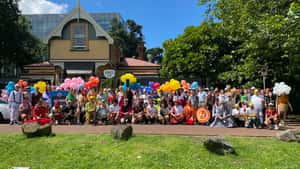
Halter's Top Stability & Growth Strengths
Market Expansion: Geographic reach is widening quickly, with operations scaling across many U.S. states and stated plans to enter the U.K. and Ireland alongside continued growth in New Zealand and Australia. Customer adoption also broadened materially, with notable increases in the number of ranches and farms using the platform.
Investor Backing & Capital Strength: Capital access strengthened through sizable late‑stage rounds at markedly higher valuations within a short span, with independent confirmations of the most recent raise. This trajectory indicates strong investor confidence to fund continued commercial and product expansion.
Strong Revenue Growth: New Zealand filings and reporting indicate materially higher subscription and segment revenues over recent periods. These financial signals align with increased collar deployments and a larger installed base.
Cat Digital is the digital and technology arm of Caterpillar Inc., responsible for bringing digital capabilities to our world-famous yellow iron. With over 1.5M connected assets worldwide, our teams use data, technology, advanced analytics and AI capabilities to help solve our customers' toughest challenges.
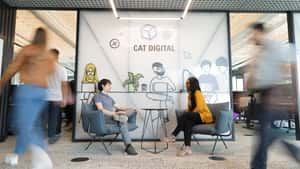
Caterpillar's Top Stability & Growth Strengths
Strong Revenue Growth: Sales and revenues reached record levels in 2025 and accelerated further in early 2026, with multiple quarters showing strong double-digit year-over-year increases. Results attribute the expansion primarily to higher equipment sales volumes, supported by favorable pricing.
Resilient & Sustainable Growth: Backlog is described as record and growing into 2026, which management says supports continued momentum. Raised full‑year and longer‑term revenue outlooks further indicate durability across segments.
Strong Market Position & Advantage: Caterpillar is identified as the global leader in construction and mining equipment, reinforced by independent rankings and a large dealer network. Scale and brand presence appear to underpin demand across Construction Industries, Resource Industries, and Power & Energy.
HERE Technologies is a location data and technology company that created the first digital map over 35 years ago. Today we are the world's leading location platform company with a global footprint across 52 countries. Although our strongest presence is in the automotive industry, we also work with leading companies across a wide range of industries, including transport and logistics,...
HERE Technologies's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with automakers such as Hyundai AutoEver, Lotus, and Amap, alongside cloud collaborations like AWS and ecosystem ties with Esri, continue to expand. These relationships appear to deepen distribution and integration across automotive and enterprise use cases.
Innovation-Driven Growth: The portfolio is expanding into AI, software-defined vehicles, ADAS, autonomous driving, and logistics, with launches such as HERE SDK updates and Location Reasoning. This trajectory indicates increasing focus on higher-value, future-oriented offerings.
Strong Market Position & Advantage: Independent analyst indices (Omdia and Counterpoint) repeatedly place the company at the top of location-platform rankings, and installed vehicle use rose from 222M to 238M. These signals point to sustained competitive standing and broad automotive adoption.
Yext (NYSE: YEXT) is the enterprise agentic marketing platform. Built on the world's most comprehensive structured data platform for local businesses, Yext gives brands and their partners the visibility intelligence to win every moment of discovery – across AI and traditional search. Yext's API-first architecture connects structured data to APIs, MCP servers, and generative interfaces, so partners and developers can...

Yext's Top Stability & Growth Strengths
Profitability: Net income turned from -$27.9M in FY2025 to +$37.9M in FY2026, and adjusted EBITDA rose from $67.0M to $107.3M with margin expansion. Profitability continued into FY2027 with strong quarterly EBITDA performance.
Cost & Operational Efficiency: Operating discipline, restructuring, and reduced expenses are credited with materially improving margins and earnings despite muted top-line trends. The business has shifted from loss-making expansion to efficiency and margin expansion.
Future-Ready Strategy: Product investments and positioning around AI/agentic marketing (e.g., Scout, Corvo AI) and targeted acquisitions (e.g., Hearsay) indicate a pivot toward AI-driven search visibility and regulated-industry use cases. This suggests preparation for evolving demand rather than reliance solely on legacy listings revenue.
We bring brilliant people together in a global ecosystem that is sparking the world’s potential. Arm technology enables specialized processing built on the economics, design freedom and accessibility of general-purpose compute that has, so far, led to more than 180 billion chips being shipped by our partners.

Arm's Top Stability & Growth Strengths
Strong Revenue Growth: Financial results show robust annual growth in FY2026 with momentum continuing at a similar double-digit pace into Q1 FY2027. Growth is visible across both licensing and royalty lines rather than being a one‑off spike.
Diversified Revenue Streams: Both the up‑front licensing engine and the recurring royalty stream are expanding, indicating balanced contribution from new IP agreements and shipped chips. Data-center royalties also accelerated sharply, reinforcing breadth within the royalty base.
Market Expansion: Growth drivers increasingly include AI and data centers, with data‑center royalties more than doubling and adoption spreading beyond smartphones into automotive and edge applications. This reduces dependence on traditional mobile cycles.
Founded in 2013 with a vision to eliminate the need for single-use bottles and cans, Bevi is redefining how beverages are delivered in commercial spaces. Best known for its Smart Water Cooler®, Bevi has grown into the leading connected beverage platform, combining hardware, data, and beverage innovation to deliver still, sparkling, flavored, and enhanced drinks on demand. Powered by real-time...

Bevi's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have surpassed the $100 million annual mark with continued year-over-year gains. Feedback suggests momentum is reinforced by growth in newer verticals such as education and hospitality.
Market Expansion: The company extended its footprint from North America into the UK and Ireland and broadened placements beyond offices into campuses, hotels, gyms, warehouses, and other venues, while scaling to more than 6,000 customers. Feedback suggests international entry and vertical diversification are driving a larger installed base and usage milestones such as surpassing one billion single-use containers avoided.
Product Line Growth: The offering advanced from smart water coolers to a connected beverage platform, adding functional enhancements and a better-for-you soda line alongside new countertop hardware. Feedback suggests the expanded menu increases relevance across more locations and upsell potential within existing accounts.

Rundoo is the AI-native, all-in-one ERP for independent supply stores: point of sale, inventory, payments, and the general ledger in one system. We serve independent paint, hardware, and farm & feed retailers who've been stuck running their business on outdated point-of-sale systems and a patchwork of disconnected software, and we're built to help them modernize: better experiences for them, their...
Rundoo's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor support is described as robust, with a $30M Series B led by Battery Ventures and participation from Bessemer and CRV, bringing total funding to $48M. This capital is earmarked to scale engineering and go-to-market operations.
Market Expansion: The company is said to serve 500+ independent stores across the U.S., Canada, and the Caribbean and plans to grow teams in Redwood City and Chicago. These moves indicate widening geographic reach and operational scale.
Innovation-Driven Growth: AI capabilities, including the “Dooey” agent, are highlighted as a leading reason customers choose the platform, with external coverage noting the growing importance of its AI functionality. Reported 5,000+ users on the customer app suggest expanding product adoption beyond store employees.
Ambiq® enables intelligence (AI and beyond) everywhere by delivering the lowest-power semiconductor solutions for battery-powered edge devices. As a pioneer in ultra-low power SoCs, Ambiq empowers wearables, IoT, smart home, healthcare, and industrial products with always-on, energy-efficient intelligence. Backed by our SPOT® technology and global innovation leadership, Ambiq is shaping the future of edge AI.
Ambiq 's Top Stability & Growth Strengths
Strong Revenue Growth: Recent quarters show rapid acceleration, with Q1 2026 net sales rising to $25.1M and Q2 reaching $33.9M alongside five consecutive quarters of sequential growth. Guidance for Q3 2026 of $36–37M indicates the trend may continue.
Cost & Operational Efficiency: Despite FY2025 revenue declining from 2024, gross profit increased to $32.1M and gross margin expanded materially. In Q2 2026, gross profit more than doubled year over year.
Investor Backing & Capital Strength: The company completed an IPO and upsized follow-on offerings in 2026, bolstering liquidity to over $360M in cash with no debt. It also added a dual listing in Singapore to broaden its investor base.
Our Mission: Create a world where everyone has an authentic digital identity. Identity Digital is an internet infrastructure company that makes sure web addresses work seamlessly. If we do our job right, we are invisible to the user. We have the world’s largest portfolio of nearly 300 TLDs like .info, .pro, .world, which lets people and businesses build, market, and own...
Identity Digital's Top Stability & Growth Strengths
Strong Revenue Growth: Inclusion on the Inc. 5000 for five consecutive years and company statements of “healthy revenue growth” in 2025 indicate sustained top-line expansion. Three-year growth figures cited for recent periods (e.g., 152% then 82%) reinforce momentum, even though audited financials are not public.
Market Expansion: The .ai migration and subsequent surge (more than 60% YoY registrations in 2025, with registrar distribution roughly doubling) alongside multiple 2025 registry-agreement changes point to a growing footprint. Access to 1,800+ ICANN-accredited registrars and operations across 80+ locations further extend reach.
Strong Market Position & Advantage: Operating what is described as nearly 300 TLDs and supporting 28M+ domains, while resolving 60.4B+ DNS queries per day, signals substantial scale. Broad registrar access (including 90%+ coverage for .ai at migration) and a large installed base underscore competitive advantage.
Parsec Automation, LLC (Parsec) is a trailblazing creator and provider of manufacturing operations management software. Consistently recognized by organizations like Gartner and IDC and a winner of numerous awards, including the Data Breakthrough Awards, American Business, and Best in Biz, Parsec exemplifies leadership in the dynamic, fast-paced manufacturing sector. With global manufacturers leveraging its innovative TrakSYS™ platform to tackle even the most complex manufacturing challenges, Parsec’s...
Parsec Automation's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue and ARR are described as growing at double-digit rates across 2023–2025, with seven consecutive years of revenue growth reported through 2023. Feedback suggests momentum came from both new customer logos and expansion ARR in existing enterprises.
Market Expansion: Geographic and customer reach is expanding, with TrakSYS reportedly deployed in thousands of factories across 140+ countries alongside new logo wins and increased bookings. Feedback suggests ongoing enterprise sales hiring and multi-site deployments are broadening coverage.
Investor Backing & Capital Strength: Capital support was bolstered by a 2023 recapitalization led by BVP Forge explicitly aimed at scaling the platform and accelerating growth. Feedback suggests this backing is enabling continued product and organizational investment.
.png)
Doodle Labs designs and produces industrial-grade wireless networking solutions. The company focuses on mesh networking for robotic systems, providing high throughput, long-range Mesh Rider solutions for UAVs, UGVs, AMRs and other robotic applications. The company’s Helix Mesh Rider Radio was developed with sponsorship from DIU and is the Blue UAS program’s datalink of choice. Doodle Labs was named one of Fast...
Doodle Labs's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships are described as expanding across OEMs, integrators, and channels, including integrations with Auterion, Teledyne FLIR, Teal/Red Cat, and new agreements such as LUXUAV and distribution via Mouser. These relationships are portrayed as increasing platform embed opportunities and international reach.
Product Line Growth: The portfolio is reported to have expanded from Mesh Rider into Nano², Mini, OEM, Boost, and Wearable radios, along with Sense-EW capabilities and a mobile app. This widening set of form factors and features suggests a broader addressable market and use cases.
Market Expansion: Activity is noted across U.S. defense programs (e.g., an Army Phase II SBIR award) and into Europe through NATO-aligned pushes and the LUXUAV partnership. Company materials also highlight integrations across drones and robotics globally, indicating growing geographic and sector presence.
Since 2012, Mirakl has been pioneering the platform economy, empowering retail and B2B enterprises with the most advanced, secure and scalable technology to digitize and expand product assortment through marketplace and dropship, improve efficiency in supplier catalog management and payments, personalize shopping experiences, and boost profits through retail media. Mirakl is trusted by Macy’s, Saks, Henry Schein, The Knot, 1800-Flowers, Best...
Mirakl's Top Stability & Growth Strengths
Strong Revenue Growth: ARR increased from $177M in 2024 to $218M in 2025, with reported ARR roughly doubling since 2021. Platform activity also expanded as GMV rose from $11.2B to about $14.6–$15B over the same period.
Profitability: The group was profitable throughout 2025, following earlier profitability in the core Platform business. This progression indicates improving operating leverage alongside continued expansion.
Diversified Revenue Streams: Newer products are contributing incremental revenue, with Mirakl Connect generating about $11.7M ARR in under a year and Mirakl Ads seeing a sharp rise in ad spend in 2025. Customer additions (45 global enterprises in 2025) and launches across marketplace and dropship broaden the commercial base.
SmartBear delivers application integrity for modern tech stacks, ensuring continuous, measurable assurance that software just works as intended – with governance to operate at AI speed and scale. SmartBear offers deep test automation, API lifecycle management, and observability capabilities. With integrations across the SDLC, it sets a new quality standard for application delivery teams. SmartBear is trusted by more than...
SmartBear's Top Stability & Growth Strengths
Profitability: Revenue is described as approaching/exceeding a $500M milestone alongside years of revenue and profitability expansion. Leadership also cites revenue and EBITDA more than tripled during a prior tenure, indicating durable earnings power.
Product Line Growth: The portfolio has expanded through acquisitions (e.g., Reflect, Stoplight, QMetry) and ongoing AI-powered releases and integrations. These moves extend capabilities across API lifecycle, testing, and test management to support continued expansion.
Strong Market Position & Advantage: Analyst recognition as a Leader in API management and enterprise testing, coupled with adoption across 32,000+ organizations and major enterprises, signals entrenched positioning. This breadth enhances cross-sell opportunities across core niches.
Squarespace is a design-driven platform helping entrepreneurs build brands and businesses online. We empower millions of customers in more than 200 countries and territories with all the tools they need to create an online presence, build an audience, monetize, and scale their business.
Squarespace's Top Stability & Growth Strengths
Strong Revenue Growth: Financial disclosures show 2023 revenue up 17% to $1.012 billion, and annual run-rate revenue up 20% year over year to $1.1795 billion in 2024. This indicates sustained top-line momentum going into the take-private.
Product Line Growth: New offerings such as Squarespace Capital (2025) and Squarespace Balance (March 2026) expand the business from website creation into payments, financing, and business financial services. A 2025 partnership integrating capabilities into Perplexity’s Comet browser further broadens the product ecosystem.
Investor Backing & Capital Strength: The October 2024 take-private by Permira at approximately $7.2 billion explicitly aimed to support expansion and product development. This transaction underscores access to capital and sponsor support for continued scaling.

Samsara (NYSE: IOT) is the pioneer of the Connected Operations® Platform, which is an open platform that connects the people, devices, and systems of some of the world’s most complex operations, allowing them to develop actionable insights and improve their operations. With tens of thousands of customers across North America and Europe, Samsara is a proud technology partner to the...

Samsara's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at around 30% year over year across recent quarters and fiscal periods, indicating continued expansion at scale. Growth is not primarily a currency effect and has been maintained across multiple updates.
Profitability: GAAP profitability has been achieved for multiple consecutive quarters, with operating income turning positive versus a loss a year earlier. Margin expansion and improved free cash flow underscore operating leverage.
Resilient & Sustainable Growth: Growth has been sustained at roughly the same pace across recent quarters and the prior fiscal year rather than spiking in a single period. Large-customer momentum and multi-product adoption underpin this consistency.
Blissway is a transportation tech startup founded by Stanford grads that uses machine learning and IoT to simplify the collection of tolls and improve road safety. Backed by Y Combinator –the famed startup accelerator– and some of the best investors in Silicon Valley, we have been developing and testing our technology with the Colorado Department of Transportation and transportation agencies...
Blissway's Top Stability & Growth Strengths
Strong Hiring & Retention: Headcount and active hiring are described as increasing, with a new Denver headquarters and dedicated international recruiting indicating continued team expansion. Multiple profiles note ongoing engineering hires and growth in the 11–50 employee range.
Product Line Growth: The company’s offerings now span automated tolling, HOV/express-lane occupancy verification, commercial back-office systems, disaster-recovery/interim tolling, and point-to-point speed enforcement. This broader scope suggests movement from a single-solution focus toward a platform approach.
Market Expansion: Deployments in Colorado and inclusion in Washington State technology studies indicate activity beyond a single corridor, alongside the establishment of a Denver operational hub. References to statewide program use and corridor expansions point to a growing geographic footprint.
Ericsson builds the digital connectivity the world relies on. Our technology underpins the mobile networks, platforms, and systems that billions of people, businesses, and societies depend on every day. We are a global leader in communications technology, delivering mobile network infrastructure, cloud software, and wireless connectivity solutions for service providers and enterprises worldwide. Our networks support connectivity across 180+ countries, helping...

Ericsson's Top Stability & Growth Strengths
Profitability: Adjusted EBITA and margins improved markedly in 2025, with adjusted EBITA rising from SEK 27.2B to SEK 42.9B and margin from 11.0% to 18.1%. Margin resilience continued into 2026 despite mixed sales.
Resilient & Sustainable Growth: Underlying sales show modest improvement, with +6% organic growth in Q1 2026 and +2% for H1 2026. Organic growth also appeared in three of four market areas in Q2 2026.
Healthy Cash Flow: Cash generation remained positive, with H1 2026 free cash flow before M&A up year over year. Net cash strengthened versus the prior year, supporting financial flexibility.


Work Your Passion. Live Your Purpose.

