

Top AI Companies (7,065)
AI is great at understanding what you're asking. It's terrible at giving you answers you can trust. Kepler built a platform that separates what AI does well from what code does well where AI handles the conversation, code handles the truth. The result is the first AI system that can show its work. Kepler automatically ingests scattered data, structures it into...
Kepler 's Top Stability & Growth Strengths
Market Expansion: Public materials indicate the platform now covers 27 global markets and has broadened beyond a core finance launch into areas like private equity, compliance, accounting, and tax. Feedback suggests the product is “live and in production,” with added distribution surfaces supporting reach into more workflows.
Strategic Partnerships: Announcements describe an Anthropic MCP connector available for existing customers and note that Anthropic’s team approached Kepler about building it, alongside data integrations such as Quartr. These integrations provide external validation and create new product surfaces for adoption.
Investor Backing & Capital Strength: Company pages identify institutional backers including Mantis VC and Company Ventures along with prominent operator‑angels, and separate profiles cite more than $7M raised by mid‑2026. This access to capital and experienced networks supports ongoing hiring, product development, and go‑to‑market efforts.
Cat Digital is the digital and technology arm of Caterpillar Inc., responsible for bringing digital capabilities to our world-famous yellow iron. With over 1.5M connected assets worldwide, our teams use data, technology, advanced analytics and AI capabilities to help solve our customers' toughest challenges.
Caterpillar's Top Stability & Growth Strengths
Strong Revenue Growth: Sales and revenues reached record levels in 2025 and accelerated further in early 2026, with multiple quarters showing strong double-digit year-over-year increases. Results attribute the expansion primarily to higher equipment sales volumes, supported by favorable pricing.
Resilient & Sustainable Growth: Backlog is described as record and growing into 2026, which management says supports continued momentum. Raised full‑year and longer‑term revenue outlooks further indicate durability across segments.
Strong Market Position & Advantage: Caterpillar is identified as the global leader in construction and mining equipment, reinforced by independent rankings and a large dealer network. Scale and brand presence appear to underpin demand across Construction Industries, Resource Industries, and Power & Energy.
Apollo is a $1.6B AI-powered sales platform that helps revenue teams find and engage leads, automate outreach, manage deals, and enrich data — all in one place. Known for its industry-leading B2B database of more than 210 million contacts and 35 million companies, Apollo’s end-to-end platform helps businesses of all sizes unlock their full market potential with unparalleled precision and...

Apollo.io's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported at $150M in May 2025, with a February 2026 update indicating it was approaching $200M. External recognition like Deloitte’s Fast 500 cites very high multi-year revenue growth (e.g., 752% from 2021–2024).
Market Expansion: Customer penetration is described as nearly 100,000 paying customers by February 2026 and more than 600,000 companies served. Movement upmarket is highlighted by a stated 400% increase in enterprise accounts over the prior 12 months.
Innovation-Driven Growth: AI platform usage reportedly grew 500% year over year with 50,000+ weekly active users in 2025. Product momentum includes an AI Assistant launch, new AI integrations, and the Pocus acquisition in 2026.

Datadog (NASDAQ: DDOG) is a global SaaS business, delivering a rare combination of growth and profitability. We are on a mission to break down silos and solve complexity in the cloud age by enabling digital transformation, cloud migration, and infrastructure monitoring of our customers' entire technology stacks. Built by engineers, for engineers, Datadog is used by organizations of all sizes...

Datadog's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show accelerating top-line momentum, with FY2025 up 28% and Q2 2026 revenue up 36% year over year after 32% in Q1. Management also raised 2026 revenue guidance to $4.45B–$4.47B, indicating confidence in continued expansion.
Healthy Cash Flow: Cash generation is substantial, including Q2 2026 operating cash flow of $316M and free cash flow of $279M with about a 25% free-cash-flow margin. The company also reported roughly $5.0B in cash, cash equivalents and marketable securities as of June 30, 2026.
Customer Loyalty & Retention: Expansion within the installed base is a key driver, with about 75% of the 2025 revenue increase coming from existing customers and rising multi‑product adoption. Larger accounts are also expanding, as $100K+ ARR customers grew roughly 23% year over year to ~4,720 in Q2 2026.
PagerDuty, Inc. (NYSE:PD) is a global leader in digital operations management, enabling customers to achieve operational efficiency at scale with the PagerDuty Operations Cloud. The PagerDuty Operations Cloud combines AIOps, Automation, Customer Service Operations and Incident Management with a powerful generative AI assistant to create a flexible, resilient and scalable platform to increase innovation velocity, grow revenue, reduce cost, and...

PagerDuty's Top Stability & Growth Strengths
Profitability: Feedback suggests GAAP operating income turned positive in FY2026 and profitability has continued across recent quarters, indicating stronger earnings discipline.
Healthy Cash Flow: Feedback suggests free cash flow reached roughly $100M+ in FY2026 and remained solid in subsequent quarters, signaling improved cash generation.
Cost & Operational Efficiency: Feedback suggests margin expansion and restructuring efforts have driven better operating efficiency even as top-line growth slowed.

At Intenseye, we believe protecting people at work is non-negotiable. That’s why we’re building the world’s most advanced AI-powered platform for industrial environments, designed to help organizations move from reactive programs to proactive risk prevention across safety, operations, and quality management. Our technology gives enterprises the ability to see risk and inefficiency as they emerge, take action in real time, and...

Intenseye's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised is substantial, with a $64M Series B and roughly $90M+ total reported, alongside a valuation step-up from just under $100M in 2021 to approximately $275–300M by 2023. This trajectory indicates strong investor conviction and ample resources to scale.
Market Expansion: Geographic and deployment reach has widened markedly—from 15+ countries in 2021 to 45+ countries and 400+ facilities, covering 100,000+ workers, with a reported 125% footprint increase in 2023. Ongoing enterprise activity is reflected in hundreds of onsite visits and multi-site rollouts with large industrial customers.
Product Line Growth: Offerings have expanded beyond core computer vision to include mobile support, integrations, an AI safety assistant (Chief), and optional Sentinel hardware. Reported scale metrics (e.g., billions of images processed daily and tens of millions of unsafe acts detected) suggest sustained product investment and adoption.
.png)
Worth is the AI-powered platform that consolidates onboarding, underwriting, and risk monitoring for fintechs, lenders, payment processors, and financial institutions. Founded in 2023, we built Worth to replace slow, manual underwriting with a single system that verifies, scores, and monitors small and medium-sized businesses (SMBs) in real time. At the center of the platform is Crosswalking Technology. Our proprietary AI/ML models...

Worth's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raises include a $25M round in 2025 and a $30M Series A in 2026 led by Fulcrum Equity Partners with participation from Amex Ventures and TTV Capital. These milestones indicate resources to scale and reinforce confidence in the company’s trajectory.
Market Expansion: Operations and customer deployments have broadened, with 50+ enterprise customers in production across 200+ countries and an Orlando expansion adding 30 high-impact jobs. Third-party regional reporting characterizes the move as supporting a growing workforce and technology offerings.
Product Line Growth: The platform has expanded from core data matching into broader onboarding and underwriting capabilities, including Decision Intelligence, KYB/KYC, and continuous monitoring. Company materials also point to a larger SMB data footprint, increasing from roughly 242M+ to 350M+ profiles and more data points per entity.

Kustomer is the AI-native CX platform that helps companies move beyond reactive support and build customer experience around outcomes. By connecting customer data, workflows, knowledge, AI, and human agents in one system, Kustomer gives teams the context and control to deliver faster, more personal experiences and turn customer interactions into growth opportunities.
Kustomer's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investors have continued to back the company with significant new capital post‑spinout, including additional rounds that independent sources corroborate. This suggests a solid financial runway to support ongoing expansion.
Innovation-Driven Growth: The company has shifted firmly toward an AI‑native customer‑experience platform, highlighting sustained investment in agentic architecture and frequent AI product releases. This pattern indicates active product expansion rather than a stagnant portfolio.
Customer Loyalty & Retention: The customer base includes recognizable brands and examples of multi‑year usage, alongside reports of improved retention and faster renewals. These signals point to durable relationships and expanding adoption among existing accounts.
Inspiren offers the most complete and connected ecosystem in senior living. Founded by Michael Wang, a former Green Beret turned cardiothoracic nurse, Inspiren proves that compassionate care and technology can coexist - bringing peace of mind to residents, families, and staff. Our integrated solutions seamlessly fit into existing workflows, capturing everything happening within a community. Backed by nurse specialists and powerful...

Inspiren's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Funding momentum is pronounced, with a $35M Series A (Mar 2025), $100M Series B (Sep 2025), and a $70M Series C (Sep 2026) bringing total capital to about $225M at a valuation above $500M. This pattern signals sustained investor appetite and a materially stronger capital position.
Strong Revenue Growth: Reporting indicates subscription revenue nearly quadrupled year over year to about $29M, while contracted revenue surpassed $60M. These figures point to rapid scaling of recurring and booked revenue.
Market Expansion: Commercial reach appears to be growing, with monitoring of roughly 40,000 residents across just over 500 senior-living communities and new deployments among named operators. Expanding partnerships and portfolio rollouts suggest a widening customer footprint.

Our platform creates comprehensive digital twins of your supply chain with AI-powered digital workers to automate resolution, improve collaboration and drive outcomes across all stakeholders. Unlike traditional control towers, we enable true real-time execution and intelligent fulfillment, transforming both your supply and customer-facing operations.
FourKites's Top Stability & Growth Strengths
Innovation-Driven Growth: The company has expanded beyond visibility into AI-driven supply-chain execution with an Intelligent Control Tower, digital twins, and a digital workforce of AI agents. Independent write-ups also describe these 2024–2026 product moves, indicating a significant broadening of the offering.
Strong Market Position & Advantage: Materials describe a large global footprint (1,600+ enterprise customers, 3M+ daily shipments across 200+ countries) and repeated Leader recognition through 2024, with additional 2026 control-tower leadership mentions. These signals point to durable competitive positioning in core markets.
Strong Revenue Growth: Reported FY25 results for FourKites India show revenue of ₹147.4 crore, up 18.5% year over year, with profit also rising. While subsidiary-specific, this is clear, recent evidence of financial growth in a significant operating unit.

Liftoff is a leading AI-powered performance marketing platform for the mobile app economy. Our end-to-end technology stack helps app marketers acquire and retain high-value users, while enabling publishers to maximize revenue across programmatic and direct demand. Liftoff’s solutions, including Accelerate, Direct, Monetize, Intelligence, and Vungle Exchange, support over 6,600 mobile businesses across 74 countries in sectors such as gaming, social, finance,...

Liftoff's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has risen strongly across 2025–2026, with the latest quarter marking the company’s 11th consecutive period of top-line expansion. Momentum is driven by continued gains in its Core Advertising business.
Profitability: Adjusted EBITDA expanded materially, with margins improving alongside scale, indicating solid operating leverage. Recent quarters show profitability strengthening even as the business invests for growth.
Healthy Cash Flow: Operating and free cash flow increased sharply on a trailing twelve‑month basis. Cash generation supports reinvestment and a stronger balance sheet following debt reduction.

Build the expertise the rest of the industry will follow. Fieldguide is establishing a new state of trust for global commerce and capital markets by automating and streamlining the work of assurance and audit practitioners. We build agentic software for the people who enable trust between businesses. This is where deep professional expertise meets cutting-edge AI. Our team is reimagining how the...
Fieldguide's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Multiple late-stage rounds led by prominent firms and a sizable valuation indicate strong financial capacity to scale. Public announcements describe sustained capital access and conviction from well-known investors.
Strong Market Position & Advantage: Adoption across a significant share of the largest U.S. accounting firms, including members of the Big Four, points to entrenched presence in its target segment. Named wins with top-100 firms reinforce credibility and commercial traction.
Innovation-Driven Growth: Expansion into agentic AI and new modules (e.g., orchestration, financials, MCP) shows a strategy centered on product innovation. Ongoing launches and category-first milestones are presented as fueling momentum.
Gradient AI is revolutionizing Group Health and P&C insurance with AI-powered solutions that help insurers predict risk more accurately, improve profitability, and automate underwriting and claims. Our SaaS platform taps into one of the industry’s largest data lakes—tens of millions of policies and claims—to deliver deep, actionable insights. Trusted by leading carriers, MGAs, TPAs, and self-insured employers, Gradient AI has...
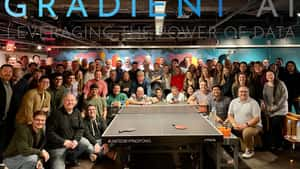
Gradient AI's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Significant financing includes a $56.1M Series C in 2024 and additional growth-capital funding from CIBC Innovation Banking in March 2026, signaling continued investor confidence and runway. Company communications indicate these funds are directed toward product development, R&D, customer success, and sales.
Product Line Growth: Recent launches and expansions span Renewal Analytics, workers’ compensation capabilities (including a claims-triage solution), and a major expansion of the Group Health analytics platform, alongside an integrated Risk Management Life Cycle solution. This pattern points to broadening coverage across underwriting, renewals, and claims.
Customer Loyalty & Retention: Current materials highlight hundreds of enterprise deployments with very high client retention, paired with ongoing wins and deployments in 2025–26 (e.g., Community Health Options, Evolution Risk Partners, and continued 2026 additions). These signals suggest a sticky and expanding customer base.
Carbon Robotics is the leader in physical AI for agriculture, helping farmers become more profitable and sustainable. Its flagship product, the LaserWeeder™, is the world’s leading commercial laser weeding system with hundreds of units operated by farmers in 15 countries worldwide. LaserWeeder combines computer vision, AI, robotics, and high-powered lasers to identify weeds and destroy them with sub-millimeter precision—no herbicides, hand...

Carbon Robotics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have doubled over the 12 months prior to October 2024 and later surpassed $100M annually for the fiscal year ending January 31, 2026. Subsequent commentary describes continued scaling beyond this milestone, indicating ongoing momentum.
Market Expansion: Operations are described as spanning roughly 15–20 countries with particularly strong traction in the U.S., Western Europe, and Australia, alongside manufacturing and service footprints in the U.S. and Europe. Customer adoption is cited as 200+ growers across 15 countries, signaling broadening geographic reach.
Product Line Growth: The company moved beyond LaserWeeder into Carbon Autonomy/AutoTractor and launched the LaserWeeder G2 line. Another agricultural robot in development and autonomy programs further indicate portfolio expansion.

At Graphcore, we’re building the future of AI compute. We’re a team of semiconductor, software and AI experts, with deep experience in creating the complete AI compute stack - from silicon and software to infrastructure at datacenter scale. As part of the SoftBank Group, backed by significant long-term investment, we are delivering key technology into the fast-growing SoftBank AI ecosystem....

Graphcore's Top Stability & Growth Strengths
Investor Backing & Capital Strength: SoftBank ownership and subsequent capital deployments are described as materially strengthening the company’s funding base, with multiple 2025–26 share allotments and later injections supporting expansion. Evidence indicates this provides far greater financial backing than before the acquisition.
Strong Hiring & Retention: Plans to double UK headcount to around 750 and create 500 semiconductor roles in India signal substantial workforce expansion. The company also indicated immediate hiring of 100 India engineering roles, suggesting growth already underway.
Market Expansion: Announcements of a new AI Engineering Campus in Bengaluru and additional international offices point to a broader geographic footprint. These moves indicate active scaling of R&D capacity across regions.
Hiya is trusted by global businesses, carriers, and consumers to enable secure, engaging connections and stop unwanted calls. Hiya is pioneering the next generation of AI-powered voice intelligence with real-time analysis and an AI assistant to enhance voice protection, productivity, and call performance. Hiya connects businesses with their customers, helps carriers secure their networks, and protects people from spam and...
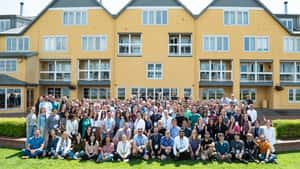
Hiya Inc.'s Top Stability & Growth Strengths
Strategic Partnerships: Samsung and Hiya extended their relationship through 2028, and Hiya highlights deep integrations with major operators and OEMs. Recent launches with Vodafone (UK and Ireland), Bouygues Telecom (France), DNA Finland, Telenor Sweden, Deutsche Telekom and O2 Telefónica (Germany) reinforce embedded distribution at device and network level.
Market Expansion: Hiya reports coverage in 40+ countries with network reach growing from 200M+ in 2021 to 500M–550M+ people, alongside analysis of 28B+ calls per month. Ongoing European rollouts in 2025–2026 indicate continued geographic scaling and platform utilization.
Product Line Growth: The company has broadened beyond caller ID/spam blocking into enterprise SaaS and branded calling, introducing offerings such as Hiya AI Phone and Caller Reputation. The acquisition of Loccus.ai for deepfake voice detection further expands its voice‑security portfolio.
Sonar provides the essential verification layer for the AI-driven development era, ensuring all code—whether human-written or AI-generated—is code you can trust. Today, AI coding tools are generating explosive volumes of code. This has created an "engineering productivity paradox" : faster code writing doesn't automatically lead to faster, safer software delivery. The new bottleneck is verification. Sonar solves this. Integrating code quality and...

Sonar's Top Stability & Growth Strengths
Strong Revenue Growth: ARR has surpassed $430 million with accelerated growth, and expectations of 22–23% revenue increases in 2026–27 reinforce ongoing momentum. This scale is bolstered by tens of thousands of paying customers and broad enterprise adoption, including a large share of Fortune 100 companies.
Innovation-Driven Growth: New AI-centric offerings (e.g., Sonar Vortex and a SonarQube Remediation Agent) and the 2026 acquisition of Gitar extend the platform into AI-native code verification and review. This product cadence signals active investment to capture emerging developer and DevSecOps use cases.
Investor Backing & Capital Strength: A $412 million financing at a $4.7 billion valuation led by Advent International and General Catalyst, with Insight Partners and Permira, provides resources to scale globally. Stated plans to pursue $1 billion in revenue underline sustained access to growth capital.
At 3Play Media, we’re transforming the way organizations approach video accessibility and localization—making it faster, easier, and more reliable to reach every viewer. From captions and subtitles to audio descriptions and dubs, our platform streamlines workflows that once took days into just a few clicks. We support thousands of customers across media & entertainment, education, enterprise, and sports—helping them expand...

3Play Media's Top Stability & Growth Strengths
Product Line Growth: The company has broadened offerings beyond captioning into transcription, live captioning, audio description, localization, and AI-enabled dubbing, including new products like Pulse and a YouTube-focused AI dubbing solution. Company-reported usage for dubbing (30+ million hours watched) indicates meaningful adoption of newer products.
Market Expansion: Acquisitions of Captionmax and National Captioning Canada expanded capabilities and geographic reach into Canada, with subsequent integration under the 3Play brand. A 2025 rebrand and creator-focused launches signal entry into new segments and international localization markets.
Investor Backing & Capital Strength: A majority investment from Riverside Partners and the 2025 addition of a CFO, alongside promotions to a Chief Growth Officer and CTO, indicate financial and organizational readiness for scale. Active openings in customer success, sales, and delivery roles further suggest continued investment in growth operations.
It’s an exciting time to be a Teragonian! Come help us transform the Private Equity industry and drive AI innovation while taking on new challenges and career growth opportunity. Teragonia provides an AI-based Value Orchestration platform for private equity backed mid-market operators, helping them transform fragmented operational data into an execution-focused view of business performance. With Teragonia, mid-market leaders align their...
Teragonia's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported as more than tripled in 2025, with annual recurring subscription and service revenue increasing by over 220%. Growth is attributed to new and expanding relationships with private equity sponsors and their portfolio companies.
Market Expansion: Office openings and relocations across Chicago, Dallas, New York, and Toronto, plus expanded sponsor footprint and portfolio reach, indicate widening geographic and commercial coverage. The company cites doubling sponsor partnerships and reach into a network representing about $400B AUM.
Strong Hiring & Retention: Headcount is estimated to have risen sharply over 2023–2026, and multiple executive appointments (e.g., EVPs for Finance & Corporate Development and for Technology & Operations) were made to support scaling. Added locations and planned team growth in hubs like Chicago and New York further signal ongoing talent expansion.

Granted is the consumer-first, AI-native product that fights medical bills and helps people navigate health benefits. The U.S. healthcare system is confusing by design. Insurance coverage is opaque, benefits are hard to understand, and medical bills are often wrong. Nearly 40% of bills contain errors or are incorrectly denied, yet most people don’t have the time, expertise, or energy to challenge...

Granted's Top Stability & Growth Strengths
Market Expansion: Granted is extending beyond direct-to-consumer into institutional channels, launching a North Texas educator program initially covering 5,000+ Mesquite ISD employees with additional districts expected. A September 2026 rollout of Clear the Bill further signals targeted regional program expansion.
Strategic Partnerships: Collaborations with First Financial Group of America and StretchDollar are broadening access through employer and benefits distribution. These partnerships are described as recent commercial expansions and the company’s first school‑district collaboration.
Investor Backing & Capital Strength: The company secured approximately $16.25M–$16.3M in a 2024 Series A/financing, cited by multiple industry sources. This level of backing indicates meaningful investor support for continued development and scaling.


Work Your Passion. Live Your Purpose.

