

Top Washington, DC Software Companies With Best Stability & Growth (611)
.png)
GRAIL is a healthcare company whose mission is to detect cancer early, when it can be cured. GRAIL is using the power of high-intensity sequencing, population-scale clinical studies, and state-of-the-art computer science and data science to enhance the scientific understanding of cancer biology, and to develop and commercialize pioneering products.
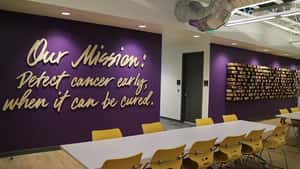
GRAIL's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a double‑digit pace across 2025 and into 2026, with consistent year‑over‑year gains. Galleri test volumes and screening revenue also increased, signaling sustained commercial momentum.
Market Expansion: Access is broadening through major EHR integrations and a growing provider network, alongside initiatives to enter new geographies. These moves extend reach beyond core channels and support continued adoption.
Investor Backing & Capital Strength: Capital raises and a sizable cash position provide a multi‑year runway to fund commercialization, trials, and regulatory efforts. Strategic financings with prominent partners reinforce the ability to invest through scale‑up.
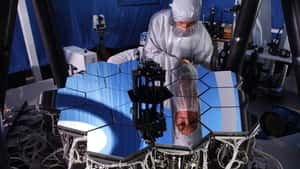
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased 10% in 2025 and 9% in H1 2026, with leadership upgrading 2026 guidance to 8–10% sales growth. Growth was reported across all major sectors.
Profitability: Underlying EBIT rose 12% in 2025 and 11% in H1 2026, alongside an improved return on sales. This points to stronger margins in addition to top-line expansion.
Resilient & Sustainable Growth: A record order backlog of roughly £83.6–84.0 billion and multi‑year contracts provide substantial future revenue visibility. The 2026 outlook also signals continued expansion.
Wipfli is a leading national advisory and accounting firm with nearly 100 years of serving ambitious middle-market organizations. We understand our clients' unique challenges and help them succeed on their terms through assurance, tax, advisory, outsourcing and technology services. With 2,900+ associates and global alliances, we combine national capabilities with local relationships. "Wipfli" is the brand name under which Wipfli LLP...

Wipfli's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has increased across FY24–FY26 with consecutive year-over-year gains, indicating steady top-line momentum. Company disclosures describe this as “purposeful” and oriented toward sustainable long-term growth alongside expansion in advisory and technology.
Investor Backing & Capital Strength: A strategic minority investment from New Mountain Capital was secured to accelerate growth, fund technology and talent, and support acquisitions. This signals enhanced capital resources to pursue the firm’s expansion agenda.
Product Line Growth: Capabilities have broadened through acquisitions and internal investment, adding areas such as cybersecurity, privacy, risk, digital transformation, and technology services (e.g., CompliancePoint and Harbour Results transactions). New leadership roles focused on growth, sales, and corporate development reinforce the expanding services mix.
Founded in Chicago in 1987 by Stan Day, SRAM, LLC has grown to be one of the world's largest bicycle component manufacturers. Today, we are led by CEO, Ken Lousberg, and Stan Day serves as Chairman of our Board. SRAM’s global footprint helps us bring cycling to every corner of the globe, including your local roads and trails. We design and...

SRAM, LLC's Top Stability & Growth Strengths
Market Expansion: Facility build-outs in Portugal and new regional hubs in Italy, along with expansion in Taiwan and a Chicago HQ redevelopment, indicate a scaling global footprint. Company materials also cite 20+ locations across 10+ countries, underscoring broad geographic reach.
Product Line Growth: Recent launches such as RED AXS (2024) and Force AXS (2025), coupled with acquisitions including Ochain, Hammerhead, TIME, and Velocio, expand coverage across drivetrains, electronics, and accessories. This cadence points to continued investment in portfolio breadth.
Strong Market Position & Advantage: The company is repeatedly characterized as one of the world’s largest bicycle-component manufacturers and a primary rival to Shimano across premium segments. This standing reflects deep relevance with OEMs and the aftermarket.

Rokt is the global leader in ecommerce, unlocking real-time relevance in the moment that matters most - The Transaction Moment. Rokt’s AI Brain and Ecommerce Network powers billions of transactions connecting hundreds of millions of customers, and is trusted to do this by the world’s leading companies including Live Nation, Macy’s, Fanatics, AMC Theatres, PayPal, Uber, Hulu, Staples, Albertsons and...

Rokt's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as reaching about $600M with 43% year-over-year growth in 2024, with consistent references to 40%+ growth and independent estimates indicating expansion toward ~$900M annualized in 2025. This pattern is reinforced by multi‑year growth markers such as 330% revenue growth over a recent three‑year period and listings on major fast‑growth rankings.
Strong Market Position & Advantage: Scale indicators include 33,000+ companies (including more than half of leading global ecommerce brands), 165M monthly active users growing 45%+ YoY, and billions of transactions processed (7.5B+ in 2025 and 13B+ projected in 2026). High‑profile enterprise adoption across sectors (e.g., Uber, Live Nation, Macy’s, PayPal) underscores traction at the transaction moment.
Investor Backing & Capital Strength: Valuation stepped up from $2.4B (2022) to $3.5B in a January 2025 secondary transaction, alongside a prior $325M Series E and a $335M secondary, signaling sustained investor confidence. These capital events coincide with disclosures of rapid revenue growth and continued scaling.
Together, we turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Profitability: Investment performance is described as exceptional over multiple years, with LCH citing record cumulative net gains and annual investor profits including a record ~$16B in 2022 and further multibillion-dollar gains in 2023–2024. This track record positions the firm at or near the top of cumulative profitability rankings.
Strong Revenue Growth: Trading revenue at the affiliated market maker rose sharply, reaching a record ~$12.2B in 2025 and accelerating further with multi‑billion‑dollar quarters in 2026. This momentum indicates expanding top‑line scale alongside broader business activity.
Market Expansion: The geographic footprint is widening with Dubai slated as the 18th city, a growing London hub, and new or expanded sites such as New York, Miami, and Amsterdam. International hiring and build‑outs across Asia and Europe further reinforce expansion into additional markets.
ASI is a dual-use software company that deploys predictive AI to the world's most complex operating environments. Backed by leading investors–including Andreessen Horowitz, Renegade Partners, and Spark Capital–we actively manage over 40% of all US air traffic across both public and private sector air operations. Partnering with major airlines like United and Alaska, we optimize thousands of flights daily, delivering...
Air Space Intelligence's Top Stability & Growth Strengths
Market Expansion: ASI has broadened beyond commercial aviation into defense and critical infrastructure, adding a DIU sustainment tool, a National Grid collaboration, and a Joby partnership alongside a major FAA program rolling out from the Washington, D.C. region. Company materials describe a scope spanning aviation, defense, logistics, energy and more, with locations in Boston, Washington, D.C., and Gdańsk.
Strong Market Position & Advantage: A 12-year, $875M FAA selection for FMDS and SMART—now in operational deployment around Washington, D.C.—signals meaningful competitive strength at national scale. Available reporting indicates ASI prevailed in a field that included larger incumbents, underscoring differentiation.
Strong Hiring & Retention: Signals include a “rapidly expanding team,” added offices, and recent defense-oriented roles (e.g., a Data Lead in Colorado Springs), with external coverage citing 165+ employees and plans to grow beyond 250 to deliver major programs. Active postings across technical and federal roles further reflect continued team build-out.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue appears to be increasing over time, with evidence of substantial growth in 2022 and continued year-over-year expansion into early 2023, even as the pace moderates. Feedback suggests the business is still scaling toward a larger revenue base while transitioning to a mature growth profile.
Profitability: Independent credit commentary highlights improved profitability and a deliberate shift toward a profit-focused operating model. Feedback suggests efficiency gains and margin improvement are becoming central to the company’s stability and growth trajectory.
Innovation-Driven Growth: Ongoing AI platform investment, rising adoption of AI capabilities, and product expansion including acquisitions are cited as current growth engines. Feedback suggests these initiatives are supporting continued operational and market expansion.
Vast is developing next-generation space stations to ensure continuous human presence in space for America and its allies, enabling advanced microgravity research and manufacturing, and unlocking a new space economy for government, corporate, and private customers. Using an incremental, hardware-rich and low-cost approach, Vast is rapidly developing its multi-module Haven Station. Haven Demo’s 2025 success made Vast the only operational...

Vast's Top Stability & Growth Strengths
Investor Backing & Capital Strength: The company announced $500M of new funding in March 2026, bringing total private investment in its technology and facilities to over $1B. It says the capital will expand facilities, grow the team, and advance Haven-2.
Strong Hiring & Retention: Headcount is described as rising from fewer than 140 in 2023 to 700+ by early 2025 and 1,000+ by 2026. Additional figures point to around 1,236 employees in 2026, indicating sustained scaling.
Strategic Partnerships: NASA selected the company for its sixth private astronaut mission to the ISS targeted for 2027, and it maintains a transport relationship with SpaceX. International agreements and new payload partners further indicate expanding institutional and commercial ties.

Zeta Global (NYSE: ZETA) is the AI Marketing Cloud that leverages advanced artificial intelligence (AI) and trillions of consumer signals to make it easier for marketers to acquire, grow, and retain customers more efficiently. Through the Zeta Marketing Platform (ZMP), our vision is to make sophisticated marketing simple by unifying identity, intelligence, and omnichannel activation into a single platform –...
Zeta Global's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has increased materially over multiple years and recent quarters, with management repeatedly raising full‑year guidance and delivering consecutive “beat and raise” results. The latest updates indicate continued acceleration rather than a slowdown.
Healthy Cash Flow: Operating and free cash flow expanded significantly year over year, with recent quarters showing further gains alongside a turn to positive GAAP net income. This points to improving efficiency as scale increases.
Resilient & Sustainable Growth: Expansion spans both customer count and monetization, with Super‑Scaled customers and ARPU rising together. Multi‑year growth across revenue, customers, and cash generation suggests durability rather than a one‑time surge.
Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising in the mid-30% year over year, with acceleration from Q1 to Q2 2026 and raised full-year 2026 guidance. Contracted demand indicators such as Current RPO also increased in the mid-30% range, reinforcing momentum.
Diversified Customer Base: Evidence points to a broad customer mix, from hundreds of thousands of paying customers to thousands of large enterprises, including a significant share of the Fortune 500. Growth in $100K+ and $1M+ spend cohorts underscores continued upmarket penetration.
Healthy Cash Flow: Observations include positive and increasing free cash flow alongside strong operating cash generation in recent periods. These trends suggest the business is funding growth while improving cash efficiency.
Altana powers agentic trade workflows and public-private collaboration across product value chains — the source of truth for where products come from. With Altana, businesses can prove compliance before goods ship and build more efficient, resilient, and secure supply chains. Logistics providers can automate the full brokerage workflow, and governments can promote economic security, manage borders, and enable the flow...

Altana's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Funding reached a $200M Series C in July 2024 at a $1B valuation with prominent investors. Available evidence suggests substantial capital to scale and strong external confidence.
Market Expansion: Engagements extended across governments and enterprises, including the UK’s £8M three-year program, a CBP contract expansion, and new deployments with General Atomics Aeronautical Systems and Scarbrough Global; by 2026, the company said 8 of the world’s 10 largest logistics providers were customers. These signals indicate continued penetration into large, international accounts and public-sector programs.
Product Line Growth: The offering broadened beyond supply-chain mapping into compliance, procurement, trade-risk management, and customs-automation workflows, including the 2026 Cervo AI acquisition. 2025–2026 materials describe additional use cases and live customer deployments.
Octus, was founded in 2013 with a simple conviction: credit decisions deserve clarity, not chaos. Markets were fragmented. Intelligence was gated. Data lived in silos. Professionals were forced to stitch together incomplete pictures while the clock kept running. We built Octus to change that. Octus is the essential credit platform that tracks the entire credit lifecycle. From origination and underwriting to...
Octus's Top Stability & Growth Strengths
Strong Hiring & Retention: Headcount is portrayed as rising from 650+ in 2024 to roughly 900 by 2026, with nearly 300 people onboarded in 2025. This pace, noted in an Okta case study, indicates active scaling of teams across functions.
Product Line Growth: Multiple launches across 2025–26—CreditAI (unified in March 2026), Deal Term Analytics, CovenantAI, and an MCP Connector—signal accelerated expansion of offerings and distribution channels. Integrations with Harvey, Perplexity, and Rogo extend product reach into AI-enabled workflows.
Market Expansion: The company reports growth from more than 25,000 professionals in 2022 to 44,000+ users, and says it now covers the full leveraged-finance lifecycle rather than a distressed/bankruptcy niche. A series of acquisitions (FinDox, LoansIntel, Sky Road, LevPro) and geographic expansion point to a broader market footprint.

Hilton (NYSE: HLT) is a leading global hospitality company with a portfolio of 22 world-class brands comprising nearly 7,300 properties and more than 1.1 million rooms, in 123 countries and territories. Dedicated to fulfilling its founding vision to fill the earth with the light and warmth of hospitality, Hilton has welcomed more than 3 billion guests in its more than...
Hilton's Top Stability & Growth Strengths
Market Expansion: Hotel footprint is widening, with properties and rooms increasing, approvals for additional rooms, and a record development pipeline by mid-2026. The network spans over 140 countries and reflects continued entry into new markets.
Strong Revenue Growth: Revenue rose to about $12.04B in 2025 from the prior year, and early 2026 showed gains in system-wide comparable RevPAR. Management also indicated continued comparable RevPAR growth for 2026.
Product Line Growth: The portfolio is expanding with new brands and lodging categories, including the Apartment Collection and the conversion-focused Outset Collection. Broader offerings in lifestyle and luxury support conversions and attract a wider range of owners and travelers.

Space was once the quietest place in the universe. Now, it's crowded, contested, and confrontational. We are True Anomaly: the only defense company focused exclusively on space defense. Founded in 2022 by ex-U.S. Space Force members, True Anomaly designs and builds advanced systems for space superiority: agile and powerful spacecraft platforms, mission software engineered for unmatched command and control, and payloads...

True Anomaly's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised has accelerated from a $260M Series C in 2025 to a $650M Series D in 2026, pushing cumulative funding above $1B and indicating substantial financing capacity. Funding is described as enabling facility expansion, manufacturing scale-up, and a larger mission cadence.
Strong Hiring & Retention: Headcount expanded from a small founding team to ~250 by end-2025, with stated targets of 500+ in 2026 and 1,000+ in 2028 alongside multi-site growth in Colorado and Long Beach. Independent coverage during 2026 also points to 250–300+ employees, reinforcing tangible workforce scaling.
Strong Market Position & Advantage: Selection for multiple Space Force efforts—such as VICTUS HAZE operations, Kronos software, GHOST-R/RG-XX, and Space-Based Interceptors—signals movement from small R&D awards toward larger defense procurement. The company reports transition from development flights to operational missions, including a space-to-space pursuit during VICTUS HAZE.
Relativity Space is on a mission to better connect humanity to space and the universe beyond our planet. Our medium-to-heavy lift reusable rocket, Terran R, will deliver customer payloads to orbit, meeting the growing demand for launch capacity. But that’s just the start. Achieving commercial success with Terran R will unlock new opportunities to advance science, exploration, and innovation, pioneering progress that...
Relativity Space's Top Stability & Growth Strengths
Market Expansion: Access to NASA’s NLS II and the U.S. Space Force’s NSSL Phase 3 Lane 1 broadens eligibility for future government missions, while multi‑launch agreements and a multibillion‑dollar backlog point to widening commercial demand. Facility growth on Florida’s Space Coast further extends operational reach.
Product Line Growth: Scope has expanded beyond launch services with an Interplanetary Sciences Program and a planned Mars science orbiter in 2028. Terran R has advanced from design into flight‑hardware production, engine acceptance testing, structural qualification, and launch‑site build‑out.
Strong Hiring & Retention: Headcount has risen materially to a reported ~2,000 employees across multiple U.S. locations. Concurrent expansion of Long Beach manufacturing and Cape Canaveral infrastructure indicates sustained organizational scaling.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Strong Revenue Growth: Optum’s consolidated revenue expanded from $253.0B in 2024 to $270.6B in 2025, indicating continued top-line growth. Multi‑year reporting also highlights ongoing increases at the consolidated level even as segment performance diverges.
Diversified Revenue Streams: Performance is spread across three businesses, with Optum Rx delivering substantial gains, Optum Insight growing modestly, and Optum Health contracting. This mix shows pharmacy and technology services helping sustain overall scale despite softness in care delivery.
Cost & Operational Efficiency: Operating performance improved in 2026 as Optum’s operating income rose year over year to about $4B in Q2 alongside reported gains in technology and clinical operations. UnitedHealth also raised its 2026 adjusted EPS outlook, signaling confidence in execution.
Upside is a technology company that increases the financial power of people and businesses in the real world. Our technology has helped millions of people get more purchasing power on the things they need, and tens of thousands of brick-and-mortar businesses earn measurable profit. Billions of dollars in commerce run through the Upside platform every year, and that value goes...
Upside's Top Stability & Growth Strengths
Market Expansion: Feedback suggests Upside expanded its marketplace with 14,669 new retailer locations and 1.6M new customers in 2025, alongside 128M transactions and a 64% YoY jump in restaurant transactions in July 2025. Feedback suggests category breadth deepened as well, with Taco Bell locations up 400% year over year and the network reaching 100,000+ retailers and ~35M consumers.
Strong Market Position & Advantage: Feedback suggests scale signals are substantial, including 35M consumers, 100,000+ retailers, >$1B cumulative cash back, and a rise in retailer incremental profit from $605M in 2024 to $707M in 2025. Feedback suggests repeated inclusion on growth rankings (e.g., Inc. 5000, Deloitte Technology Fast 500) further reflects momentum and visibility.
Strategic Partnerships: Feedback suggests partnerships and integrations broaden distribution and merchant adoption, including Marqeta and rollouts with large operators such as Save Mart and major QSR franchise groups. Feedback suggests these alliances extend Upside’s reach beyond the standalone app via partner networks that help drive consumer exposure and category expansion.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding rapidly, with recent quarters showing accelerated year-over-year gains in both total and subscription revenue. Multi-year growth at a high double-digit pace is also evident in the latest annual results.
Resilient & Sustainable Growth: Contracted revenue indicators appear robust, with total RPO at $29.0B and current RPO at $13.2B in Q2 2026. Management also raised its full-year 2026 subscription outlook, signaling confidence in continued expansion.
Innovation-Driven Growth: Newer AI offerings are gaining commercial traction, with ServiceNow AI surpassing $1 billion in annual contract value and agentic deployments scaling quickly. Large-deal activity and the count of very large customers also increased, indicating product-led expansion.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in the latest quarters, with momentum accelerating into Q2 2026. Monetization per user improved, helping top-line growth outpace audience expansion.
Healthy Cash Flow: Adjusted EBITDA and free cash flow rose sharply, and the company generated positive free cash flow in the latest quarter. These gains indicate stronger operating leverage versus a year earlier.
Diversified Revenue Streams: Subscription and other direct-revenue products such as Snapchat+ expanded rapidly alongside core advertising. “Other revenue” grew significantly and the direct-revenue run rate scaled materially.



