

Top Washington, DC Aerospace Companies With Best Stability & Growth (73)
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased 10% in 2025 and 9% in H1 2026, with leadership upgrading 2026 guidance to 8–10% sales growth. Growth was reported across all major sectors.
Profitability: Underlying EBIT rose 12% in 2025 and 11% in H1 2026, alongside an improved return on sales. This points to stronger margins in addition to top-line expansion.
Resilient & Sustainable Growth: A record order backlog of roughly £83.6–84.0 billion and multi‑year contracts provide substantial future revenue visibility. The 2026 outlook also signals continued expansion.
A leading global aerospace company and top U.S. exporter, Boeing develops, manufactures and services commercial airplanes, defense products and space systems for customers in more than 150 countries. Our U.S. and global workforce and supplier base drive innovation, economic opportunity, sustainability and community impact. Boeing is committed to fostering a culture based on our core values of safety, quality and...

Boeing's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising year over year, with H1 2026 up 11% and Q1/Q2 growing 14% and 8% respectively, supported by higher commercial-aircraft deliveries. This momentum reflects increased production throughput and broader top-line recovery.
Healthy Cash Flow: Cash generation is improving, as H1 2026 operating cash flow turned positive and free cash flow improved, including a positive result in Q2. This shift indicates better working-capital dynamics alongside rising delivery volume.
Strong Market Position & Advantage: Backlog is at a record level of roughly $715 billion, including more than 6,200 commercial aircraft. This depth of contracted demand provides multi‑year visibility for production and revenue.
Relativity Space is on a mission to better connect humanity to space and the universe beyond our planet. Our medium-to-heavy lift reusable rocket, Terran R, will deliver customer payloads to orbit, meeting the growing demand for launch capacity. But that’s just the start. Achieving commercial success with Terran R will unlock new opportunities to advance science, exploration, and innovation, pioneering progress that...
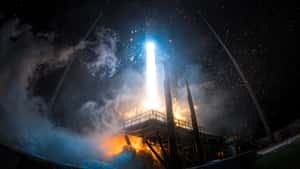
Relativity Space's Top Stability & Growth Strengths
Market Expansion: Access to NASA’s NLS II and the U.S. Space Force’s NSSL Phase 3 Lane 1 broadens eligibility for future government missions, while multi‑launch agreements and a multibillion‑dollar backlog point to widening commercial demand. Facility growth on Florida’s Space Coast further extends operational reach.
Product Line Growth: Scope has expanded beyond launch services with an Interplanetary Sciences Program and a planned Mars science orbiter in 2028. Terran R has advanced from design into flight‑hardware production, engine acceptance testing, structural qualification, and launch‑site build‑out.
Strong Hiring & Retention: Headcount has risen materially to a reported ~2,000 employees across multiple U.S. locations. Concurrent expansion of Long Beach manufacturing and Cape Canaveral infrastructure indicates sustained organizational scaling.

Space was once the quietest place in the universe. Now, it's crowded, contested, and confrontational. We are True Anomaly: the only defense company focused exclusively on space defense. Founded in 2022 by ex-U.S. Space Force members, True Anomaly designs and builds advanced systems for space superiority: agile and powerful spacecraft platforms, mission software engineered for unmatched command and control, and payloads...

True Anomaly's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised has accelerated from a $260M Series C in 2025 to a $650M Series D in 2026, pushing cumulative funding above $1B and indicating substantial financing capacity. Funding is described as enabling facility expansion, manufacturing scale-up, and a larger mission cadence.
Strong Hiring & Retention: Headcount expanded from a small founding team to ~250 by end-2025, with stated targets of 500+ in 2026 and 1,000+ in 2028 alongside multi-site growth in Colorado and Long Beach. Independent coverage during 2026 also points to 250–300+ employees, reinforcing tangible workforce scaling.
Strong Market Position & Advantage: Selection for multiple Space Force efforts—such as VICTUS HAZE operations, Kronos software, GHOST-R/RG-XX, and Space-Based Interceptors—signals movement from small R&D awards toward larger defense procurement. The company reports transition from development flights to operational missions, including a space-to-space pursuit during VICTUS HAZE.
Vast is developing next-generation space stations to ensure continuous human presence in space for America and its allies, enabling advanced microgravity research and manufacturing, and unlocking a new space economy for government, corporate, and private customers. Using an incremental, hardware-rich and low-cost approach, Vast is rapidly developing its multi-module Haven Station. Haven Demo’s 2025 success made Vast the only operational...

Vast's Top Stability & Growth Strengths
Investor Backing & Capital Strength: The company announced $500M of new funding in March 2026, bringing total private investment in its technology and facilities to over $1B. It says the capital will expand facilities, grow the team, and advance Haven-2.
Strong Hiring & Retention: Headcount is described as rising from fewer than 140 in 2023 to 700+ by early 2025 and 1,000+ by 2026. Additional figures point to around 1,236 employees in 2026, indicating sustained scaling.
Strategic Partnerships: NASA selected the company for its sixth private astronaut mission to the ISS targeted for 2027, and it maintains a transport relationship with SpaceX. International agreements and new payload partners further indicate expanding institutional and commercial ties.
ASI is a dual-use software company that deploys predictive AI to the world's most complex operating environments. Backed by leading investors–including Andreessen Horowitz, Renegade Partners, and Spark Capital–we actively manage over 40% of all US air traffic across both public and private sector air operations. Partnering with major airlines like United and Alaska, we optimize thousands of flights daily, delivering...
Air Space Intelligence's Top Stability & Growth Strengths
Market Expansion: ASI has broadened beyond commercial aviation into defense and critical infrastructure, adding a DIU sustainment tool, a National Grid collaboration, and a Joby partnership alongside a major FAA program rolling out from the Washington, D.C. region. Company materials describe a scope spanning aviation, defense, logistics, energy and more, with locations in Boston, Washington, D.C., and Gdańsk.
Strong Market Position & Advantage: A 12-year, $875M FAA selection for FMDS and SMART—now in operational deployment around Washington, D.C.—signals meaningful competitive strength at national scale. Available reporting indicates ASI prevailed in a field that included larger incumbents, underscoring differentiation.
Strong Hiring & Retention: Signals include a “rapidly expanding team,” added offices, and recent defense-oriented roles (e.g., a Data Lead in Colorado Springs), with external coverage citing 165+ employees and plans to grow beyond 250 to deliver major programs. Active postings across technical and federal roles further reflect continued team build-out.
Ursa Major was founded to address a critical shortfall in the U.S. industrial base and bring a new model to aerospace and defense systems: we design and manufacture the world’s leading propulsion systems for space, hypersonic applications, and missile systems. Our products and technologies require an extraordinary team – a team that will mold tomorrow’s technologies while deploying today’s best....

Ursa Major's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Funding rounds, debt commitments, and a proposed SPAC with committed PIPE capital are described as expanding the capital base to accelerate production. Independent reporting also notes a step‑up valuation around $2.3B, reinforcing access to growth financing.
Strong Market Position & Advantage: Bookings exceeding $115M through Q3 2025 and multi‑year awards with organizations such as AFRL, Stratolaunch, and the U.S. Navy point to rising commercial traction. Operational milestones (100+ engines produced, 100,000+ seconds of testing) further support competitive standing.
Product Line Growth: Capabilities are described as expanding from liquid engines into hypersonics, solid rocket motors, space mobility, and complete systems like HAVOC. Manufacturing scale‑ups and a new Longmont facility were opened to meet this broader program mix.

Epirus is a high-growth technology company developing solid-state, software-defined directed energy systems that enable unprecedented counter-electronics effects and power management solutions to optimize power efficiency in defense and commercial applications. With a constant emphasis on innovation, we are redefining the future of power to bring tomorrow’s capabilities to life, today. To deliver on our mission, we are always looking for...

Epirus's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $250 million Series D in March 2025 pushed total venture funding above $550 million, with the company stating the raise would “hyperscale” Leonidas manufacturing and scale operations. Private‑market trackers also placed valuation around $1.0B in that period, indicating substantial backing at a growth stage.
Market Expansion: Cross‑service traction includes U.S. Army prototype deliveries and follow‑on Gen‑II orders in 2025 and a Navy warfare center delivery in 2025, and an MoU with Singapore’s DSTA in January 2026 added international momentum. Public demos and exercises with U.S. and allied observers in 2025 further broadened visibility across theaters.
Strategic Partnerships: Integrations and teaming span General Dynamics Land Systems (autonomous Leonidas AR/AGV on GDLS/Kodiak platforms) and links with Anduril’s Lattice C2, with additional teaming like Peraton and Digital Force Technologies to extend the cUAS kill chain. These collaborations expand platform routes to market and support layered‑defense integration.

You can’t fix what you can’t see. Planet believes in using space to help life on Earth. We design, build, and operate a constellation of earth-imaging satellites that deliver a dataset of geospatial imagery used to help solve the worlds most critical problems. Planet is passionate about building a community of diversity, belonging and inclusion.

Planet's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating with record Q3 FY2026 growth of about a third year over year and continued guidance implying ongoing scale. Backlog expansion provides additional visibility to sustain this momentum.
Healthy Cash Flow: Adjusted EBITDA profitability for multiple quarters and positive free cash flow in FY2026 indicate improving cash generation. Management also highlighted a stronger cash position and a bolstered balance sheet.
Strong Market Position & Advantage: Operating one of the world’s largest EO fleets with near-daily global coverage anchors leadership in high-cadence optical monitoring. Differentiation on temporal density and the Pelican/Tanager roadmap support durable advantage while moving up the value stack.


We Engineer Solutions for the Nation’s Toughest Problems As an independent nonprofit engineering innovation company, Draper provides engineering services directly to government, industry, and academia. We work on teams as prime contractors or subcontractors and participate as collaborators in consortia. Our strong commitment to delivering working solutions allows us to apply ourselves to a variety of domains from space to undersea —...


Founded in 2006, Rocket Lab is an end-to-end space company with an established track record of mission success. We deliver reliable launch services, spacecraft components, satellites and other spacecraft and on-orbit management solutions that make it faster, easier and more affordable to access space. Headquartered in Long Beach, California, Rocket Lab designs and manufactures the Electron small orbital launch vehicle...
Rocket Lab's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising sharply, with 2025 reaching $602M and new quarterly records around $200M in Q1 2026 alongside higher guidance for Q2 2026, signaling ongoing scale-up. Booking momentum and an expanding launch manifest reinforce the near-term top-line trajectory.
Diversified Revenue Streams: Business mix is broadening beyond launch as Space Systems becomes a large revenue driver, supported by prime-contract wins (e.g., SDA Tranche 3) and ongoing spacecraft and component deliveries. This diversification extends into payloads and new offerings such as the portable “GHOST” spaceport.
Strong Market Position & Advantage: Electron is identified as the most widely used small orbital launcher as of April 2026, underpinned by a high 2025 cadence and additional multi‑launch awards that took the manifest to 70+ missions. This niche leadership provides schedule and orbit-control advantages even as overall market leaders operate at larger scale.

At Southwest Airlines we connect People to what’s important in their lives—that also means connecting our Employees to what’s important in their lives! Our Employees value the opportunity to work hard, be creative, and have fun on the job. Southwest Airlines recognizes, respects, and values differences. By fostering a culture that embraces and utilizes our diversity, we create competitive advantages...
Southwest Airlines's Top Stability & Growth Strengths
Strong Market Position & Advantage: Southwest is positioned as one of the U.S. “Big Four” carriers by domestic presence and is described as the leading U.S. low‑cost carrier, indicating durable scale in its core market. Economy-cabin satisfaction leadership and strong schedule completion are presented as additional competitive advantages that can support resilience even as the product changes.
Profitability: The company is described as having returned to profitability in 2025 with record quarterly revenues and guidance for substantially higher earnings in 2026. This points to improved financial stability and a clearer path to stronger margins driven by revenue and cost initiatives.
Diversified Revenue Streams: New revenue initiatives are highlighted, including assigned seating, new fare bundles, and checked-bag fees, which broaden monetization beyond base fares. The data frames these changes as meaningful contributors to expected EBIT and earnings improvement into 2026.
PSA Airlines is a wholly owned subsidiary of American Airlines that provides regional passenger air transportation on American’s behalf. It operates an all-jet fleet of regional aircraft, serving nearly 100 domestic and international destinations through hundreds of daily departures. The airline emphasizes teamwork, inclusivity, and professional development for its more than 5,500 employees, while supporting American’s broader customer network.

Howmet Aerospace Inc., headquartered in Pittsburgh, Pennsylvania, is a leading global provider of advanced engineered solutions for the aerospace and transportation industries. The Company’s primary businesses focus on jet engine components, aerospace fastening systems, and titanium structural parts necessary for mission-critical performance and efficiency in aerospace and defense applications, as well as forged wheels for commercial transportation. With nearly 1,150...
Howmet Aerospace's Top Stability & Growth Strengths
Strong Market Position & Advantage: The company is widely recognized as a leader across jet-engine components, aerospace fasteners, and forged aluminum truck wheels, supported by qualification moats and consolidated supply chains. Recent capacity additions, portfolio expansion, and record results reinforce pricing power and share in core aero end markets.
Strong Revenue Growth: Recent results show double-digit top-line growth with margin expansion and raised full-year guidance. Broad-based demand in commercial and defense aerospace and gas turbines, plus contributions from acquisitions, support continued momentum.
Future-Ready Strategy: Management is investing in turbine-blade capacity and expanding the fasteners portfolio via acquisitions such as CAM to meet sustained engine OEM and spares demand. A multi-year growth framework and portfolio shaping signal preparation for continued scale and mix improvements.

We are GDIT. The people supporting some of the most complex government, defense, and intelligence projects across the country. We deliver. Bringing the expertise needed to understand and advance critical missions. We transform. Shifting the ways clients invest in, integrate, and innovate technology solutions. We ensure today is safe and tomorrow is smarter. We are there. On the ground, beside...
General Dynamics Information Technology's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Forward visibility looks durable due to a $100+ billion companywide backlog and repeated references to multi‑year contract wins that extend revenue coverage into 2026. The outlook frames demand as supported by defense and federal IT modernization priorities, suggesting the business can absorb near-term volatility.
Strong Market Position & Advantage: GDIT is positioned as a top-tier federal IT prime, reinforced by recurring placement in major federal contractor rankings and a steady cadence of marquee awards across DoD, intel, and civilian agencies. Its scale inside General Dynamics and ability to deliver mission-critical programs (e.g., enterprise IT modernization and large federal systems) signal competitive advantage in accreditation-heavy government work.
Diversified Revenue Streams: Revenue support is described as coming from multiple General Dynamics segments (Aerospace, Marine, Combat Systems, Technologies) alongside GDIT’s mix of defense, intelligence, health, and civilian programs. This multi-segment and multi-mission exposure reduces dependence on any single program area and supports stability through procurement cycles.

We believe our country’s soldiers, sailors, airmen, and marines deserve to be equipped with systems that enhance their competitive advantage against threats and meet rigorous demands of operational environments. Fuse is a leading supplier of innovative communications, networking, and computing solutions for U.S. defense agencies that improve the sharing of information among warfighters distributed throughout airborne, maritime, and ground environments. Warfighter-focused...

AMERICAN SYSTEMS is an employee-owned government services contractor that delivers professional, technical, information technology, engineering, analysis, testing, evaluation, and training solutions for complex national-priority programs. Based in McLean, Virginia, the company supports federal customers—particularly defense and other Department of Defense missions—with mission-essential and information engineering, digital engineering, systems integration, cybersecurity, cloud, data, and lifecycle IT services across critical public-sector environments.

SpaceX designs, manufactures and launches the world’s most advanced rockets and spacecraft. The company was founded in 2002 by Elon Musk to revolutionize space transportation, with the ultimate goal of making life multiplanetary. SpaceX has gained worldwide attention for a series of historic milestones. It is the only private company ever to return a spacecraft from low-Earth orbit, which it...
SpaceX's Top Stability & Growth Strengths
Strong Market Position & Advantage: Observed launch cadence, mass-to-orbit leadership, and vertical integration via Starlink point to clear dominance across orbital launch and LEO broadband. NASA crew/cargo reliance and key lunar contracts further reinforce centrality in critical missions.
Strong Revenue Growth: Reported revenue expanded markedly from 2023 through 2025, with Starlink becoming a majority contributor and subscribers surpassing 10 million by early 2026. Private-market valuation signals and sustained 2026 launch activity align with rapid top-line expansion.
Cost & Operational Efficiency: High‑reuse Falcon 9 operations underpin price leadership and a near‑continuous launch tempo across multiple pads. Routine booster reuse has become an industry benchmark that supports both capacity and cost advantages.

Blue Origin was founded by Jeff Bezos with the vision of enabling a future where millions of people are living and working in space for the benefit of Earth. In order to preserve Earth, Blue Origin believes that humanity will need to expand, explore, find new energy and material resources, and move industries that stress Earth into space. Blue is...
Blue Origin's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described at roughly $800 million with expectations of about $1.4 billion and multiple years of orders, indicating accelerating top-line momentum. Expanding government and commercial contracts, including NASA and national-security awards, reinforce the trajectory.
Investor Backing & Capital Strength: Capital access is highlighted by a $10 billion external funding round and a valuation around $140 billion. Significant facility investments, such as a $600 million expansion at Cape Canaveral, signal capacity to fund scale-up.
Product Line Growth: Offerings are broadening from launch into lunar landers (Blue Moon), in-space logistics (Blue Ring), and satellite initiatives, while New Glenn production and operations expand. Added selections to NASA’s Launch Services II and national-security launch contracts support these expanded lines.

Hermeus is a high-speed aircraft manufacturer focused on the rapid design, build, and test of high-Mach and hypersonic aircraft for the national interest. Working directly with the Department of Defense, Hermeus delivers capabilities that will ensure that our nation, and our allies, maintain an asymmetric advantage over any and all potential adversaries. Utilizing an integrated, hardware-rich, iterative development approach to...

Hermeus's Top Stability & Growth Strengths
Strategic Partnerships: The company has secured multi-year U.S. government agreements (e.g., U.S. Air Force awards and a DIU HyCAT contract) and collaborations that enable flight testing and hypersonic subsystem maturation. Partnerships tied to Edwards AFB operations and the HEAT facility demonstrate strong institutional alignment and access.
Investor Backing & Capital Strength: Substantial capital has been raised, including a $100M Series B and significant U.S. Air Force funding, alongside strategic investment from RTX Ventures. This financing supports rapid vehicle iteration and the stand-up of dedicated hypersonic test infrastructure.
Innovation-Driven Growth: Successful turbojet-to-ramjet transition in the Chimera TBCC engine, rapid Quarterhorse Mk 1 design-to-first-flight execution, and activation of the HEAT facility illustrate a hardware-rich, iterative approach accelerating capability.



