

Top IT Companies (10,000+)

Alloy is the only end-to-end identity risk management platform for companies that offer financial products. Beginning with origination and account opening, Alloy provides over 600 of the world's leading banks, credit unions, and fintechs with a scalable, flexible platform to manage identity risk throughout the customer lifecycle. With configurable solutions for fraud, credit and compliance risk, dedicated expert guidance and...

Alloy's Top Stability & Growth Strengths
Market Expansion: Alloy expanded into 40 countries in 2022 and later launched perpetual KYB and related offerings in the UK/Europe while adding an EMEA leadership team. These moves indicate ongoing geographic reach beyond the U.S.
Product Line Growth: The platform broadened from identity/onboarding into transaction monitoring, fraud prevention, perpetual KYC/KYB, risk-based authentication, and agentic AI. This widening scope increases platform relevance and potential revenue opportunities.
Strong Market Position & Advantage: Customer count rose from 700+ in June 2025 to 900+ by July 2026, showing substantial adoption across financial institutions and fintechs. Scale and continued uptake suggest a durable position in identity risk and fraud infrastructure.
.png)
At ReversingLabs, we are providing the world’s largest threat intelligence repository to protect software development and power advanced security solutions, keeping the most advanced cybersecurity organizations and Fortune 500 enterprises informed and ahead of the threats. Our software supply chain security and threat intelligence solutions have become essential to advancing enterprise cybersecurity maturity globally. Notable breaches such as SolarWinds, CircleCI and...
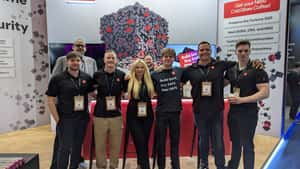
ReversingLabs's Top Stability & Growth Strengths
Product Line Growth: Spectra Assure’s customer base is described as having grown more than 150% in 2024, with the company again stating more than 150% growth since its 2024 launch into 2025. Platform activity also expanded, including a 48% year-over-year increase in identified malicious files.
Strategic Partnerships: Routes to market are broadening through initiatives such as the AWS ISV Accelerate Program, an expanded partner program, and public‑sector marketplace “Awardable” listings. The company also highlights that its data is used by more than 65 major security vendors, indicating ecosystem reach.
Investor Backing & Capital Strength: Capital availability appears solid, with approximately $120 million reported across multiple funding events, including a 2024 round. An investment led by Crosspoint Capital Partners is described as intended to accelerate growth in software supply‑chain security.
.jpeg)
We are a world leader in innovative memory solutions that transform how the world uses information to enrich life for all. For over 45 years, our company has been instrumental to the world’s most significant technology advancements, delivering optimal memory and storage systems for a broad range of applications.

Micron Technology's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate a sharp acceleration in sales, with quarterly revenue several times higher than a year earlier and sequential gains continuing. Management guidance suggests this momentum is expected to carry into the next quarter.
Profitability: Margins and net income have expanded dramatically alongside stronger pricing and mix toward AI-related products. Operating cash generation has also risen substantially, reinforcing financial strength.
Innovation-Driven Growth: Advanced AI memory offerings—such as HBM, high-capacity DIMMs, and server DRAM—are described as ramping rapidly and contributing materially to the top line. Segment data shows broad gains in cloud, core data center, mobile/client, and automotive/embedded tied to these innovations.

Nextpoint is a Chicago-based legal technology company that has been building cloud-based eDiscovery and litigation software since 2001. We make it simpler for law firms, corporate legal teams, and government agencies to manage the full lifecycle of litigation — from data ingestion and document review to case preparation and trial presentation. Our platform is built on the cloud, which means legal...

Nextpoint's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Access to growth capital, including a $4.5M non-dilutive facility and a later investment from RF Investment Partners, is positioned to scale product development and customer support. These financings are framed as fuel for expansion into new markets and operations.
Innovation-Driven Growth: Recent product leadership hires and stated investment in next‑generation AI and a microservices‑based architecture point to ongoing product expansion. Product scope has grown beyond eDiscovery into depositions, case building, and trial presentation.
Strong Hiring & Retention: Active hiring across client success, services, sales, marketing, product, and engineering indicates organizational expansion. Reported headcount increases into early 2025 further support a growing workforce.
Robin is the leading AI platform for workplace operations. Since 2014, we’ve empowered people to do their best work by building tech solutions that fuel vibrant workplace experiences - allowing you to plan, manage and use your office in an intelligent way. With the leading desk and room booking software, the industry's first AI agent and our powerful workplace analytics,...
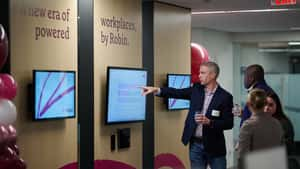
Robin's Top Stability & Growth Strengths
Strong Market Position & Advantage: Gartner included Robin as a Leader in its 2026 Magic Quadrant for Workplace Experience Applications, indicating strong competitive standing in this category. The company’s statement that it serves thousands of organizations further reflects broad market presence.
Market Expansion: The July 2026 launch on Google Cloud Marketplace opens a new procurement path through existing Google Cloud commitments for enterprise buyers. This move represents a meaningful extension of distribution and market access.
Product Line Growth: The platform has expanded from room/desk booking into a broader workplace-operations suite covering visitor management, space planning, analytics, and AI. 2026 updates such as a natural-language workplace agent, CAD-to-map functionality, and move-management tools illustrate continued breadth.
Welcome to Comcast. From the connectivity and platforms we provide to the content and experiences we create, we bring people together, globally. Our people think the world of our work, and that’s why our work is the best in the world.

Comcast's Top Stability & Growth Strengths
Healthy Cash Flow: Operating cash flow increased from $27.7 billion in 2024 to $33.6 billion in 2025, and Q2 2026 free cash flow was $4.6 billion, up 2.3% year over year. This indicates strong cash generation despite uneven top-line trends.
Diversified Revenue Streams: Connectivity revenue rose 4.2% to $46.0 billion in 2025 alongside growth in business services (to $10.2 billion), wireless lines (to 9.3 million), Peacock (revenue up 10% to $5.4 billion; paid subs up 22% to 44 million), and parks. Comcast also highlights six growth drivers—broadband, wireless, business services, studios, streaming, and parks—that represented about 60% of 2025 revenue.
Product Line Growth: Wireless and streaming scaled meaningfully, with approximately 1.5 million wireless line additions in 2025 and Peacock reaching 44 million paid subscribers that year and achieving first-time quarterly profitability in Q2 2026. Business services connectivity also expanded in 2026, including Q2 revenue up 3.7% and EBITDA up 5.0%.
At Dragos, every role advances a mission that matters. Surrounded by people with deep expertise, you’re trusted to own your work, grow your impact and your craft, while safeguarding civilization. Dragos delivers xOT cybersecurity for industrial and critical infrastructure, backed by a decade of frontline incident response experience. The Dragos Platform provides asset visibility, continuous monitoring, vulnerability management, and real-time threat...

Dragos's Top Stability & Growth Strengths
Strong Revenue Growth: The combined Dragos/runZero/NetRise business is described as having materially higher annual recurring revenue by mid-2026, pointing to robust year-over-year momentum. Although the figure reflects the group rather than Dragos alone, it demonstrates significant demand and scale around the platform.
Investor Backing & Capital Strength: A majority investment by Accenture at a multibillion-dollar valuation, together with substantial prior funding, indicates strong financial support and confidence in future expansion. This capital access is positioned to accelerate go-to-market reach and platform scaling.
Product Line Growth: Acquisitions of Phosphorus, runZero, and NetRise in 2026 expanded the offering from core OT security into xOT, exposure management, and software supply-chain security. This broadening of scope increases the addressable market and deepens the platform’s relevance.
.png)
Canoe offers first-of-its kind AI technology powering the future of alternative investments. Canoe has reimagined the future of alternative investments with cloud-based, machine-learning technology for document collection, data extraction, and data science initiatives. We transform complex documents into actionable intelligence within seconds and empower allocators with tools to unlock new efficiencies for their business. Since the beginning, we’ve maintained a focused, client-first...

Canoe's Top Stability & Growth Strengths
Strong Revenue Growth: Company disclosures indicate very strong year-over-year revenue expansion in 2023 with continued gains into 2024 alongside client growth. Investor communications also highlight a significant valuation step-up between the 2023 and 2024 financing rounds, reinforcing momentum.
Market Expansion: Expansion efforts are evident in a rapid international buildout, with notable growth across EMEA and new entries in APAC, adding many new firms and operating across numerous countries. This points to widening geographic reach and ongoing customer acquisition.
Investor Backing & Capital Strength: Capital support appears strong, including a sizable Series C led by a major institutional investor and a definitive agreement to be acquired by Bloomberg. These events suggest external validation and resources to sustain scaling.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate FY2026 revenue rose 19% year over year to roughly $2.02B, with Q1 FY2027 revenue up 16% and ARR up 17%. This points to steady double‑digit expansion across both total and recurring revenue.
Customer Loyalty & Retention: Dollar-based net retention is reported around 110–111%, and ARR growth has tracked slightly ahead of revenue growth. These signals suggest existing customers are expanding usage alongside new logo additions.
Healthy Cash Flow: Company materials highlight strong free cash flow alongside growth, including substantial FY2026 free cash flow and robust margins in recent quarters. The business has also returned capital via notable share repurchases.

Yext (NYSE: YEXT) is the enterprise agentic marketing platform. Built on the world's most comprehensive structured data platform for local businesses, Yext gives brands and their partners the visibility intelligence to win every moment of discovery – across AI and traditional search. Yext's API-first architecture connects structured data to APIs, MCP servers, and generative interfaces, so partners and developers can...

Yext's Top Stability & Growth Strengths
Profitability: Net income turned from -$27.9M in FY2025 to +$37.9M in FY2026, and adjusted EBITDA rose from $67.0M to $107.3M with margin expansion. Profitability continued into FY2027 with strong quarterly EBITDA performance.
Cost & Operational Efficiency: Operating discipline, restructuring, and reduced expenses are credited with materially improving margins and earnings despite muted top-line trends. The business has shifted from loss-making expansion to efficiency and margin expansion.
Future-Ready Strategy: Product investments and positioning around AI/agentic marketing (e.g., Scout, Corvo AI) and targeted acquisitions (e.g., Hearsay) indicate a pivot toward AI-driven search visibility and regulated-industry use cases. This suggests preparation for evolving demand rather than reliance solely on legacy listings revenue.
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
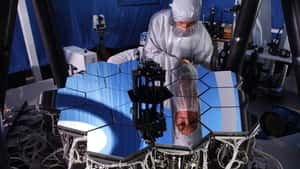
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased 10% in 2025 and 9% in H1 2026, with leadership upgrading 2026 guidance to 8–10% sales growth. Growth was reported across all major sectors.
Profitability: Underlying EBIT rose 12% in 2025 and 11% in H1 2026, alongside an improved return on sales. This points to stronger margins in addition to top-line expansion.
Resilient & Sustainable Growth: A record order backlog of roughly £83.6–84.0 billion and multi‑year contracts provide substantial future revenue visibility. The 2026 outlook also signals continued expansion.
For more than two decades, Imprivata has been redefining how life- and mission-critical industries secure and manage digital identities. We empower healthcare and enterprise organizations to enable fast, compliant, and secure access to technology—allowing clinicians and staff to stay focused on what matters most: patient care and operational excellence. Our digital identity platform is purpose-built for complex environments where every second...

Imprivata's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as sizable and growing rapidly, with independent reporting and credit analyses pointing to continued double‑digit expansion. ARR and ACV are characterized as increasing consistently since 2022.
Customer Loyalty & Retention: Retention is depicted as very high, with consistent expansion within existing accounts that supports sustained recurring revenue growth. Commentary highlights strong share‑of‑wallet gains and durable renewals across healthcare customers.
Product Line Growth: The portfolio has broadened through repeated acquisitions (e.g., SecureLink, Verosint) and new capabilities such as passwordless authentication and agentic identity management. These moves signal active investment to expand addressable use cases and deepen the platform.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Strong Revenue Growth: Optum’s consolidated revenue expanded from $253.0B in 2024 to $270.6B in 2025, indicating continued top-line growth. Multi‑year reporting also highlights ongoing increases at the consolidated level even as segment performance diverges.
Diversified Revenue Streams: Performance is spread across three businesses, with Optum Rx delivering substantial gains, Optum Insight growing modestly, and Optum Health contracting. This mix shows pharmacy and technology services helping sustain overall scale despite softness in care delivery.
Cost & Operational Efficiency: Operating performance improved in 2026 as Optum’s operating income rose year over year to about $4B in Q2 alongside reported gains in technology and clinical operations. UnitedHealth also raised its 2026 adjusted EPS outlook, signaling confidence in execution.
Enova International (NYSE: ENVA) is a leading online financial services company that serves small businesses and consumers who are underserved by traditional banks. For over 20 years, Enova has provided over $72 billion in loans and financing to more than 15 million customers by offering a suite of market-leading products powered by the company's world-class analytics, machine learning algorithms and...
Enova's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a double‑digit pace year over year, with strong 2025 expansion followed by further acceleration in early 2026 and Q2 results. Management also raised full‑year 2026 revenue outlook, signaling confidence in continued top‑line growth.
Profitability: Net income and earnings per share are increasing alongside revenue, with 2025 profits up markedly and Q2 2026 earnings advancing further. Margins strengthened as the net revenue margin improved while credit metrics such as net charge‑offs trended favorably.
Resilient & Sustainable Growth: Growth has persisted across multiple years—through 2024, 2025, and into mid‑2026—supported by rising originations and a record combined loans and finance receivables balance. Guidance calling for continued revenue and adjusted EPS growth underlines expectations for ongoing, multi‑dimensional expansion.

Doximity is the leading clinical AI company with the largest network of U.S. clinicians. Doximity’s AI-powered workflow platform is trusted by over 85% of U.S. physicians and 300+ health systems. Doximity's mission is to help clinicians be more productive so they can provide better care for their patients. We are physicians-first, putting technology to work for doctors instead of the...

Doximity's Top Stability & Growth Strengths
Healthy Cash Flow: Cash generation is strong, with operating and free cash flow increasing year over year and remaining substantial. This indicates the business can fund investments while sustaining stability.
Strong Market Position & Advantage: The platform reports a very large share of U.S. physicians and millions of registered members, alongside broad adoption of workflow tools. This scale supports durable demand from pharmaceutical clients and health systems.
Strong Revenue Growth: Revenue has continued to rise at a double-digit annual pace recently, with steady year-over-year increases across multiple periods. Even as the rate moderates, the top line remains on an upward trajectory.
Celonis makes processes work — for people, companies, and the planet. Powered by process mining and AI, the Celonis Process Intelligence Platform integrates process data and business context to create a living digital twin of business operations. We enable thousands of companies worldwide to understand how their business actually runs and, together with their partners, build intelligent solutions that transform...

Celonis's Top Stability & Growth Strengths
Strong Market Position & Advantage: Market position is described as leading, with the largest customer base and highest revenue share among process‑mining vendors, and the highest share across major regions and buyer segments. Independent analyst assessments also continue to place the company among category leaders, pointing to durable advantage.
Innovation-Driven Growth: The company is expanding from core process mining into Process Intelligence and Enterprise AI, introducing offerings such as AgentC, AI agents, integrations, and an Orchestration Engine. Reported customer‑value milestones and ongoing platform updates suggest innovation is translating into adoption and impact.
Market Expansion: Enterprise deployments reportedly increased from more than 2,500 in 2022 to 5,000+ currently, with 1,400+ businesses served and 20+ offices. Regional traction includes progress such as capturing a majority of CAC 40 firms within five years in France.
McMaster-Carr is trusted by industrial customers around the world to keep manufacturing lines running, operations moving, and turn new ideas into real products. Since 1901, we’ve earned that trust by offering the right products, making them easy to find, and delivering them quickly. Our industry-leading e-commerce experience, indispensable product selection, and world-class service bring hundreds of thousands of customers to our...

McMaster-Carr's Top Stability & Growth Strengths
Market Expansion: Public records and reporting indicate a major new regional headquarters and distribution center in Fort Worth, adding a sixth U.S. node to existing facilities in Illinois, Georgia, Ohio, California, and New Jersey. Additional buildouts at sites like Elmhurst and other regional renewals point to a broader, expanding nationwide footprint.
Innovation-Driven Growth: Project filings describe substantial automation investments at the Texas facility—high-bay racking, tote-shuttle systems, and conveyors—alongside hiring for reliability/automation roles. These moves signal scaling capacity with technology to support same- and next-day fulfillment.
Strong Market Position & Advantage: Industry coverage places the company near the top of MRO/industrial distributor rankings and highlights standout catalog breadth and rapid fulfillment. Company descriptions also cite serving hundreds of thousands of daily customers, indicating strong competitive presence.
Apollo is a $1.6B AI-powered sales platform that helps revenue teams find and engage leads, automate outreach, manage deals, and enrich data — all in one place. Known for its industry-leading B2B database of more than 210 million contacts and 35 million companies, Apollo’s end-to-end platform helps businesses of all sizes unlock their full market potential with unparalleled precision and...

Apollo.io's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported at $150M in May 2025, with a February 2026 update indicating it was approaching $200M. External recognition like Deloitte’s Fast 500 cites very high multi-year revenue growth (e.g., 752% from 2021–2024).
Market Expansion: Customer penetration is described as nearly 100,000 paying customers by February 2026 and more than 600,000 companies served. Movement upmarket is highlighted by a stated 400% increase in enterprise accounts over the prior 12 months.
Innovation-Driven Growth: AI platform usage reportedly grew 500% year over year with 50,000+ weekly active users in 2025. Product momentum includes an AI Assistant launch, new AI integrations, and the Pocus acquisition in 2026.

Tune into the innovation, collaboration and culture that our team members bring to the office every day. We want you to be a part of our journey to build the next generation of technology that transforms the way the world communicates. Our team members are the key to our history of groundbreaking innovation and our continued progress. If you bring...

EchoStar's Top Stability & Growth Strengths
Cost & Operational Efficiency: Adjusted OIBDA increased to $493M in Q1 2026 from $400M in Q1 2025, and other recent periods show sizable OIBDA gains despite lower revenue. This pattern indicates tighter cost control and operational improvements.
Product Line Growth: Wireless service revenue rose in 2025 and again in Q2 2026, with ARPU up and multiple quarters previously showing net subscriber additions. These signals point to growth momentum within the wireless segment even as other lines contract.
Strong Market Position & Advantage: Hughes, an EchoStar company, was named a Leader in Gartner’s 2026 Magic Quadrant for Managed Network Services and has noted wins in aviation connectivity. Such recognition and enterprise traction support competitive strength in defined niches.
TransUnion is a global information and insights company that makes trust possible by ensuring that each consumer is reliably and safely represented in the marketplace. We do this by having an accurate and comprehensive picture of each person. This picture is grounded in our legacy as a credit reporting agency which enables us to tap into both credit and public record...
TransUnion's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is consistently climbing across 2025 and into 2026, with management increasing full‑year guidance after stronger‑than‑expected quarters. Momentum is led by U.S. Financial Services and Emerging Verticals, with multiple quarters of high single‑ to double‑digit organic growth noted.
Profitability: Net income and adjusted earnings expanded alongside revenue, and adjusted EBITDA also increased. This points to improving operating leverage as growth scales across key segments.
Diversified Revenue Streams: Multiple business lines—including credit, fraud/identity, marketing, and international operations—are contributing to results. Expansion such as taking majority ownership in the Mexico bureau and broad-based U.S. segment strength reduce reliance on any single product or geography.



