

Top Cloud Companies (3,288)

In 1939, Bill Hewlett and Dave Packard, college friends turned business partners, started the original Silicon Valley startup in the space of a rented Palo Alto garage. Starting with audio oscillators, the friends built the foundation for a company that would grow to become a global leader in enterprise technology. More than 75 years later, our success is exemplified through...
Hewlett Packard Enterprise's Top Stability & Growth Strengths
Strong Revenue Growth: Record quarterly revenue and raised outlooks indicate accelerating top-line momentum across recent quarters. Growth is concentrated in Networking and Cloud & AI, contributing to substantial year-over-year gains.
Profitability: Operating profit and margins expanded significantly with record operating results reported. This improvement accompanies heightened demand in AI infrastructure, servers, and networking.
Healthy Cash Flow: Operating cash flow and free cash flow increased versus the prior year, reflecting stronger cash generation alongside growth. Management also pointed to higher full-year free cash flow expectations.
PagerDuty, Inc. (NYSE:PD) is a global leader in digital operations management, enabling customers to achieve operational efficiency at scale with the PagerDuty Operations Cloud. The PagerDuty Operations Cloud combines AIOps, Automation, Customer Service Operations and Incident Management with a powerful generative AI assistant to create a flexible, resilient and scalable platform to increase innovation velocity, grow revenue, reduce cost, and...

PagerDuty's Top Stability & Growth Strengths
Profitability: Feedback suggests GAAP operating income turned positive in FY2026 and profitability has continued across recent quarters, indicating stronger earnings discipline.
Healthy Cash Flow: Feedback suggests free cash flow reached roughly $100M+ in FY2026 and remained solid in subsequent quarters, signaling improved cash generation.
Cost & Operational Efficiency: Feedback suggests margin expansion and restructuring efforts have driven better operating efficiency even as top-line growth slowed.
Cat Digital is the digital and technology arm of Caterpillar Inc., responsible for bringing digital capabilities to our world-famous yellow iron. With over 1.5M connected assets worldwide, our teams use data, technology, advanced analytics and AI capabilities to help solve our customers' toughest challenges.
Caterpillar's Top Stability & Growth Strengths
Strong Revenue Growth: Sales and revenues reached record levels in 2025 and accelerated further in early 2026, with multiple quarters showing strong double-digit year-over-year increases. Results attribute the expansion primarily to higher equipment sales volumes, supported by favorable pricing.
Resilient & Sustainable Growth: Backlog is described as record and growing into 2026, which management says supports continued momentum. Raised full‑year and longer‑term revenue outlooks further indicate durability across segments.
Strong Market Position & Advantage: Caterpillar is identified as the global leader in construction and mining equipment, reinforced by independent rankings and a large dealer network. Scale and brand presence appear to underpin demand across Construction Industries, Resource Industries, and Power & Energy.
Wipfli is a leading national advisory and accounting firm with nearly 100 years of serving ambitious middle-market organizations. We understand our clients' unique challenges and help them succeed on their terms through assurance, tax, advisory, outsourcing and technology services. With 2,900+ associates and global alliances, we combine national capabilities with local relationships. "Wipfli" is the brand name under which Wipfli LLP...

Wipfli's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has increased across FY24–FY26 with consecutive year-over-year gains, indicating steady top-line momentum. Company disclosures describe this as “purposeful” and oriented toward sustainable long-term growth alongside expansion in advisory and technology.
Investor Backing & Capital Strength: A strategic minority investment from New Mountain Capital was secured to accelerate growth, fund technology and talent, and support acquisitions. This signals enhanced capital resources to pursue the firm’s expansion agenda.
Product Line Growth: Capabilities have broadened through acquisitions and internal investment, adding areas such as cybersecurity, privacy, risk, digital transformation, and technology services (e.g., CompliancePoint and Harbour Results transactions). New leadership roles focused on growth, sales, and corporate development reinforce the expanding services mix.
Applied is the connective intelligence transforming how insurance works. We build the platforms, data, and agentic systems that connect the entire insurance journey, turning months of manual work into moments. We keep work flowing, from thousands of agencies and carriers to the millions of policyholders they protect.
Applied Systems's Top Stability & Growth Strengths
Strong Market Position & Advantage: Adoption among major insurance brokers is described as deep, with 8 of the 10 largest U.S. brokers and many top-ranked agencies using an Applied system in 2025. Recognition such as Applied Epic’s inclusion in G2’s 2026 Top 100 and a large installed base reinforce a leading position in agency/broker management software.
Innovation-Driven Growth: Product expansion through AI-focused acquisitions such as Planck (2024) and Cytora (2025) adds risk digitization and automation capabilities. New offerings like Applied Recon, rapid growth in Applied Pay usage, and a “submissionless” experience with Travelers indicate active innovation driving usage.
Investor Backing & Capital Strength: Long-term backing from Hellman & Friedman, alongside Stone Point Capital, JMI Equity, and CapitalG, supports ongoing investment capacity and M&A. Multi-year ownership since 2014 aligns with continued acquisitions and product expansion.
DigitalOcean is the Inference Cloud — a full-stack, production-ready cloud platform built to run AI applications with predictable performance, sustainable economics, and radically simpler operations at scale. We are built for teams turning AI into real products — not just training models. Our advantage is not fewer features, but fewer failure modes when operating AI at scale — combining minimal...

DigitalOcean's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported up 29% year over year in Q2 2026 to $281M, with ARR at $1.125B also up 29%. Guidance for 2026 was raised to about 30–31% growth alongside record incremental ARR and a sharply higher RPO.
Innovation-Driven Growth: AI-related momentum is pronounced, with AI customer ARR at $234M, up about 212% year over year, and the launch of offerings like the Inference Engine and an AI‑Native Cloud. Larger $1M+ customer ARR also surged triple-digits, indicating product-driven expansion into higher-value use cases.
Profitability: The business is described as scaling profitably, posting strong net income and robust adjusted EBITDA margins while growing. Management commentary highlights continued profitable expansion even as investment in AI and capacity ramps.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising from $1.62B in FY2023 to $2.17B in FY2024, $2.67B in FY2025, and about $3.35B in FY2026, with Q4 FY2026 up 25% year over year. This trajectory, alongside mid‑20% ARR growth, indicates continued expansion rather than a stall.
Healthy Cash Flow: Cash generation is growing, with free cash flow rising to about $779M in FY2026 and a free‑cash‑flow margin near 23%. Non‑GAAP operating metrics, including an ~80% gross margin, underscore operating leverage.
Strong Market Position & Advantage: Industry evaluations list the company as a Leader in the 2026 Gartner Magic Quadrants for both SSE and SASE, with five consecutive years of SSE leadership. Expanding large‑enterprise adoption and thousands of customers support a durable position in its core zero trust/SSE markets.
SmartBear delivers application integrity for modern tech stacks, ensuring continuous, measurable assurance that software just works as intended – with governance to operate at AI speed and scale. SmartBear offers deep test automation, API lifecycle management, and observability capabilities. With integrations across the SDLC, it sets a new quality standard for application delivery teams. SmartBear is trusted by more than...
SmartBear's Top Stability & Growth Strengths
Profitability: Revenue is described as approaching/exceeding a $500M milestone alongside years of revenue and profitability expansion. Leadership also cites revenue and EBITDA more than tripled during a prior tenure, indicating durable earnings power.
Product Line Growth: The portfolio has expanded through acquisitions (e.g., Reflect, Stoplight, QMetry) and ongoing AI-powered releases and integrations. These moves extend capabilities across API lifecycle, testing, and test management to support continued expansion.
Strong Market Position & Advantage: Analyst recognition as a Leader in API management and enterprise testing, coupled with adoption across 32,000+ organizations and major enterprises, signals entrenched positioning. This breadth enhances cross-sell opportunities across core niches.
BuildOps is the AI-native platform for commercial contractors. Built for the complexity of large-scale commercial work, it replaces disconnected tools and manual workflows with a single system that runs every job from quote to close. At the center of the platform is OpsAI, BuildOps' intelligence layer designed for real work in the trades. OpsAI helps dispatchers send the right tech in...
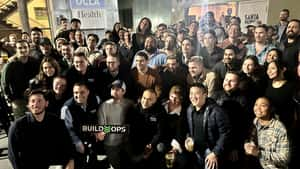
BuildOps's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding rapidly, highlighted by 1,012% three-year growth and a No. 336 placement on the 2026 Inc. 5000, with management indicating revenue doubled in 2023 and 2024. External coverage further describes the company as in a “hyper-growth” phase.
Investor Backing & Capital Strength: Capital position is reinforced by a $127 million Series C in 2025 at a $1 billion valuation, with cumulative funding reported above $225 million. This provides substantial resources for continued scaling and product investment.
Market Expansion: The geographic footprint is widening with an East Coast headquarters in Raleigh and a Canadian headquarters in Toronto, while the customer base has expanded from around 1,000 to 1,500+ contractors across North America. These steps signal broader market reach and operating scale.

Cisco ThousandEyes is a Digital Experience Assurance platform that empowers organizations to deliver flawless digital experiences across every network – even the ones they don’t own. Powered by AI and an unmatched set of cloud, internet and enterprise network telemetry data, ThousandEyes enables IT teams to proactively detect, diagnose, and remediate issues – before they impact end- user experiences. ThousandEyes...
Cisco ThousandEyes's Top Stability & Growth Strengths
Strong Revenue Growth: Observability revenues are described as rising sharply across consecutive years, with ThousandEyes repeatedly identified as a primary contributor to that momentum. Growth continued thereafter even as the broader category’s pace moderated, indicating durable contribution from ThousandEyes.
Market Expansion: ThousandEyes has been embedded into Cisco’s Digital Experience Assurance and extended across enterprise networks, the public Internet, SaaS, and public-cloud environments. Customer penetration among large enterprises has increased materially since FY2020, signaling broader reach and adoption.
Product Line Growth: Cisco has continued to add capabilities such as Cloud Insights and Traffic Insights while integrating data from Meraki and Catalyst. These enhancements expand use cases beyond standalone monitoring toward end‑to‑end network assurance.
Tune into the innovation, collaboration and culture that our team members bring to the office every day. We want you to be a part of our journey to build the next generation of technology that transforms the way the world communicates. Our team members are the key to our history of groundbreaking innovation and our continued progress. If you bring...

EchoStar's Top Stability & Growth Strengths
Cost & Operational Efficiency: Adjusted OIBDA increased to $493M in Q1 2026 from $400M in Q1 2025, and other recent periods show sizable OIBDA gains despite lower revenue. This pattern indicates tighter cost control and operational improvements.
Product Line Growth: Wireless service revenue rose in 2025 and again in Q2 2026, with ARPU up and multiple quarters previously showing net subscriber additions. These signals point to growth momentum within the wireless segment even as other lines contract.
Strong Market Position & Advantage: Hughes, an EchoStar company, was named a Leader in Gartner’s 2026 Magic Quadrant for Managed Network Services and has noted wins in aviation connectivity. Such recognition and enterprise traction support competitive strength in defined niches.
TigerConnect is healthcare’s most widely adopted communication platform – uniquely modernizing care collaboration among doctors, nurses, care teams, and patients. TigerConnect is the only solution that combines a consumer-like user experience for both clinical and patient communication with serious security, privacy, and clinical workflow requirements that today’s healthcare organizations demand. TigerConnect accelerates productivity, reduces costs, and improves patient outcomes. Trusted...

TigerConnect's Top Stability & Growth Strengths
Product Line Growth: The company expanded beyond clinical messaging into pre-hospital communication, transfers, scheduling, alarm management, nurse call, smart rooms, and patient engagement, supported by launches like Pre-Hospital, Transfer, CareConduit, and Alarm Management plus the Twiage and eVideon acquisitions. This breadth indicates a shift toward a comprehensive healthcare-orchestration platform.
Investor Backing & Capital Strength: Approximately $448.6 million has been raised across 10 funding rounds, including a $300 million investment from Vista Equity Partners in 2022. This capital base supports scaling in engineering, product, and go-to-market, exemplified by the Mexico City office expansion.
Strong Revenue Growth: Repeated inclusion on the Inc. 5000, including the 2026 list, is presented as evidence of substantial multi-year revenue growth. This external marker aligns with usage expansion to more than 1 million care-team members across nearly 6,000 organizations.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in the latest quarters, with momentum accelerating into Q2 2026. Monetization per user improved, helping top-line growth outpace audience expansion.
Healthy Cash Flow: Adjusted EBITDA and free cash flow rose sharply, and the company generated positive free cash flow in the latest quarter. These gains indicate stronger operating leverage versus a year earlier.
Diversified Revenue Streams: Subscription and other direct-revenue products such as Snapchat+ expanded rapidly alongside core advertising. “Other revenue” grew significantly and the direct-revenue run rate scaled materially.
DISQO is a leading provider of advertising intelligence, measuring brand and performance outcomes across every media channel to power data-driven marketing decisions. Trusted by 500+ of the world’s largest brands and 150+ agency and media partners, and recognized by Inc., Deloitte, Ad Age, Digiday, Forbes, and Cynopsis, DISQO is redefining the power of measurement in advertising.
DISQO's Top Stability & Growth Strengths
Product Line Growth: Product capabilities have expanded with new cross‑media, cookieless and outcomes‑measurement offerings, a free self‑service brand‑lift tool in 2025, and an AI Search Lift product in 2026. This points to a broader addressable market and deeper product footprint.
Strategic Partnerships: Partnership activity includes being selected by publishers such as Vevo and DAX for outcomes and brand‑lift measurement. These relationships indicate ongoing commercial traction into 2025–26.
Diversified Customer Base: Commercial reach spans 500+ brands and 150+ agency/media partners, with earlier disclosures citing 800+ clients. This breadth across brands, agencies, and media companies reflects a diversified set of customer segments.
Join. Grow. Lead the Future of Supply Chain. At Cleo, we don’t just integrate supply chains—we orchestrate them. As the pioneer and global leader of the Supply Chain Orchestration software category, Cleo is helping thousands of companies around the globe drive transformation, deliver excellence, and shape the future of their global operations. Whether you're joining us from outside or growing within, Cleo...

Cleo's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests revenue expanded from $66M in 2023 to $136M in 2024 and then to $254M in 2025, with ARR exiting 2024 at $186M and third-party estimates indicating continued growth into 2025.
Profitability: Feedback suggests the company became sustainably profitable in 2024, reporting an 8.4% EBITDA margin, net-income profitability from August 2024, and improving gross margins from 57% to 60%.
Resilient & Sustainable Growth: Feedback suggests improving unit economics, including lower customer acquisition cost and strong free-to-paid conversion, accompanied growth in paying subscribers from 148K in 2021 to 1.3M by December 2025.
Nexthink is the global leader in digital employee experience management. Our platform empowers IT teams with real-time visibility, analytics, and automation to proactively detect and resolve issues across any application, device, or network—before they affect employees. By shifting IT from reactive problem-solving to continuous optimization, Nexthink enables more than 1,300 organizations to create productive, seamless, and satisfying digital workplaces for...
Nexthink's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has scaled materially, with ARR approaching the $400M mark and leadership targeting expansion toward $1B, alongside earlier signals such as 42% YoY ARR growth and very high renewal/net expansion. Feedback suggests recent indications of ~$300–350M revenue and expanding customer/end‑user coverage reinforce continued momentum.
Investor Backing & Capital Strength: A majority investment by Vista Equity Partners at an approximately $3B valuation signals strong capital support and confidence in the company’s scaling prospects. Feedback suggests this backing, including associated financing, enables continued product and geographic expansion.
Strong Market Position & Advantage: Repeated recognition as a Leader in Gartner’s DEX Magic Quadrant (2024–2026) and Forrester’s EUEM Wave points to sustained category leadership. Large‑scale enterprise adoption (e.g., 1,500+ customers and 25M+ employees served) further entrenches competitive positioning.

Laudio empowers healthcare leaders to drive large-scale change through everyday human actions. Our platform streamlines workflows for frontline leaders, strengthens interpersonal connections, and aligns C-suite objectives with frontline efforts, enhancing leader efficiency, employee engagement, and patient experience. Laudio makes it possible for patients, frontline workers, and health system leaders to thrive together. Discover how at www.laudio.com.

Laudio's Top Stability & Growth Strengths
Market Expansion: Customer reach is expanding across large U.S. health systems, with cited growth from 14+ systems in 2022 to 20+ more recently and examples of system‑wide expansions (e.g., Northwell Health). This footprint is described as covering thousands of leaders and hundreds of thousands of frontline staff, indicating broader adoption.
Product Line Growth: The platform has added meaningful capabilities, including the 2025 launch of AI‑powered Performance Insights and modules spanning engagement, performance/development, overtime/attendance, and patient rounding/audits. This suggests a strategy to deepen value and expand use cases within existing customers.
Strong Revenue Growth: Historical revenue expansion is externally signaled by Laudio’s #95 placement on Deloitte’s 2023 Technology Fast 500. This recognition aligns with the broader picture of rapid past scaling.
NetBox Labs simplifies the full infrastructure lifecycle for the world’s most demanding technical environments. As the commercial steward of NetBox, the open-source infrastructure system of record trusted by 10,000+ organizations for more than a decade, NetBox Labs streamlines infrastructure procurement, modeling, deployment and management for both humans and agents. The company’s infrastructure intelligence platform powers business-critical systems at companies like...

NetBox Labs's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Funding increased substantially, with a $20M Series A in 2023 followed by a $35M Series B in 2025, bringing disclosed capital to at least $55M. The Series B was led by NGP Capital with participation from existing and new strategic investors, indicating resources to scale.
Product Line Growth: The portfolio expanded beyond NetBox/NetBox Cloud into NetBox Enterprise, NetBox Discovery/Assurance, AI capabilities such as NetBox Copilot, and a 2026 Infrastructure Intelligence Platform. The company also indicates that more than a third of customers use multiple NetBox Labs products.
Market Expansion: Commercial adoption progressed from 60+ customers (including seven Fortune 500) in 2024 to thousands of NetBox Cloud deployments by 2024. The broader NetBox ecosystem reached 10,000+ organizations by 2026, underscoring expanding reach.
Runpod is pioneering the future of AI and machine learning, offering cutting-edge cloud infrastructure for full-stack AI applications. Founded in 2022, we are a rapidly growing, well-funded company with a remote-first organization spread globally. Our mission is to empower innovators and enterprises to unlock AI's true potential, driving technology and transforming industries. Join us as we shape the future of...
Runpod's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as scaling from about $120M ARR in January 2026 to roughly $240M annualized by June 2026, indicating rapid acceleration. This trajectory aligns with simultaneous expansion in developer adoption.
Investor Backing & Capital Strength: Capital raised includes a $100M Series A/growth round at a $1B valuation, alongside a prior $20M seed financing. These milestones signal substantial institutional support for continued scaling.
Customer Loyalty & Retention: Reported net dollar retention of 120% and 155% year-over-year signup growth indicate expanding spend among existing users alongside rapid acquisition. Developer counts moving from ~100K (2024) to 1M+ (2026) reinforce broadening platform engagement.

VelocityEHS is more than a software company - we’re a team of expert problem solvers passionate about making the world a safer, more sustainable place to work. We simplify complex challenges through innovation, collaboration, and smart technology that drives real impact. At VelocityEHS, you’ll join people who care deeply about doing meaningful work, growing together, and helping companies around the...
VelocityEHS's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Institutional investors are providing sustained backing—Partners Group took a significant minority stake in 2022 alongside CVC Growth—with an explicit plan to fund international expansion, new products, and strategic acquisitions. This capital availability signals resources to underwrite the next phase of growth.
Product Line Growth: The company has expanded beyond chemical management into safety, ergonomics, industrial hygiene, operational risk, environmental compliance, ESG, and AI. Recent 2026 launches and new AI capabilities demonstrate continued broadening of the platform and addressable market.
Strong Market Position & Advantage: Independent industry recognition repeatedly places the firm in leadership cohorts (e.g., Verdantix Green Quadrant and G2 category leader listings). A large installed base—spanning 10M+ users and 15,000–19,000 customers across reported periods—reinforces competitive positioning.


Work Your Passion. Live Your Purpose.

