Top Software Companies in Dallas, TX (579)
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising year over year in 2025 and accelerating to double‑digit growth in early 2026, with management raising its full‑year outlook. Bookings and room nights are also increasing, reinforcing the top‑line trend.
Profitability: Profitability expanded faster than revenue in 2025 and continued to improve in 2026, including margin expansion in the latest quarter. This indicates operating leverage and stronger earnings quality alongside growth.
Diversified Revenue Streams: B2B has been growing much faster than the consumer business, and advertising/media also expanded strongly in 2025. Multiple engines—B2B, lodging, and advertising—are contributing materially to overall expansion.
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased 10% in 2025 and 9% in H1 2026, with leadership upgrading 2026 guidance to 8–10% sales growth. Growth was reported across all major sectors.
Profitability: Underlying EBIT rose 12% in 2025 and 11% in H1 2026, alongside an improved return on sales. This points to stronger margins in addition to top-line expansion.
Resilient & Sustainable Growth: A record order backlog of roughly £83.6–84.0 billion and multi‑year contracts provide substantial future revenue visibility. The 2026 outlook also signals continued expansion.
Cat Digital is the digital and technology arm of Caterpillar Inc., responsible for bringing digital capabilities to our world-famous yellow iron. With over 1.5M connected assets worldwide, our teams use data, technology, advanced analytics and AI capabilities to help solve our customers' toughest challenges.
Caterpillar's Top Stability & Growth Strengths
Strong Revenue Growth: Sales and revenues reached record levels in 2025 and accelerated further in early 2026, with multiple quarters showing strong double-digit year-over-year increases. Results attribute the expansion primarily to higher equipment sales volumes, supported by favorable pricing.
Resilient & Sustainable Growth: Backlog is described as record and growing into 2026, which management says supports continued momentum. Raised full‑year and longer‑term revenue outlooks further indicate durability across segments.
Strong Market Position & Advantage: Caterpillar is identified as the global leader in construction and mining equipment, reinforced by independent rankings and a large dealer network. Scale and brand presence appear to underpin demand across Construction Industries, Resource Industries, and Power & Energy.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue appears to be increasing over time, with evidence of substantial growth in 2022 and continued year-over-year expansion into early 2023, even as the pace moderates. Feedback suggests the business is still scaling toward a larger revenue base while transitioning to a mature growth profile.
Profitability: Independent credit commentary highlights improved profitability and a deliberate shift toward a profit-focused operating model. Feedback suggests efficiency gains and margin improvement are becoming central to the company’s stability and growth trajectory.
Innovation-Driven Growth: Ongoing AI platform investment, rising adoption of AI capabilities, and product expansion including acquisitions are cited as current growth engines. Feedback suggests these initiatives are supporting continued operational and market expansion.
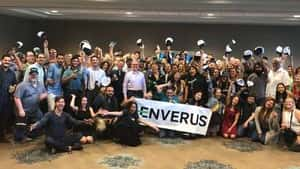
Enverus’ innovative technologies drive production and investment strategies, enable best practices for energy and commodity trading and risk management, and reduce costs through automated processes across critical business functions. Enverus is a strategic partner to more than 6,000 customers in 50 countries. Enverus is a portfolio company of Hellman & Friedman and Genstar Capital.
Enverus's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests recurring revenue expanded from crossing $500M ARR in 2023 to “approaching $600M” by May 2024. These company disclosures indicate meaningful momentum in subscription scale.
Product Line Growth: Feedback suggests the portfolio has broadened via acquisitions and new capabilities—including Pearl Street Technologies (grid interconnection), Spatial Business Systems (utility design automation), PDS Energy exchange platforms, and TGS’s A2D well‑log library. Enverus also cites rapid uptake of newer AI products and substantial growth in power and renewables since 2021.
Investor Backing & Capital Strength: Feedback suggests capital support is robust, with Blackstone agreeing in 2025 to acquire Enverus in a transaction reported around $6–6.5 billion. This major third‑party deal signals external validation of scale and resources for the next growth phase.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Strong Revenue Growth: Optum’s consolidated revenue expanded from $253.0B in 2024 to $270.6B in 2025, indicating continued top-line growth. Multi‑year reporting also highlights ongoing increases at the consolidated level even as segment performance diverges.
Diversified Revenue Streams: Performance is spread across three businesses, with Optum Rx delivering substantial gains, Optum Insight growing modestly, and Optum Health contracting. This mix shows pharmacy and technology services helping sustain overall scale despite softness in care delivery.
Cost & Operational Efficiency: Operating performance improved in 2026 as Optum’s operating income rose year over year to about $4B in Q2 alongside reported gains in technology and clinical operations. UnitedHealth also raised its 2026 adjusted EPS outlook, signaling confidence in execution.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in the latest quarters, with momentum accelerating into Q2 2026. Monetization per user improved, helping top-line growth outpace audience expansion.
Healthy Cash Flow: Adjusted EBITDA and free cash flow rose sharply, and the company generated positive free cash flow in the latest quarter. These gains indicate stronger operating leverage versus a year earlier.
Diversified Revenue Streams: Subscription and other direct-revenue products such as Snapchat+ expanded rapidly alongside core advertising. “Other revenue” grew significantly and the direct-revenue run rate scaled materially.
It’s an exciting time to be a Teragonian! Come help us transform the Private Equity industry and drive AI innovation while taking on new challenges and career growth opportunity. Teragonia provides an AI-based Value Orchestration platform for private equity backed mid-market operators, helping them transform fragmented operational data into an execution-focused view of business performance. With Teragonia, mid-market leaders align their...
Teragonia's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported as more than tripled in 2025, with annual recurring subscription and service revenue increasing by over 220%. Growth is attributed to new and expanding relationships with private equity sponsors and their portfolio companies.
Market Expansion: Office openings and relocations across Chicago, Dallas, New York, and Toronto, plus expanded sponsor footprint and portfolio reach, indicate widening geographic and commercial coverage. The company cites doubling sponsor partnerships and reach into a network representing about $400B AUM.
Strong Hiring & Retention: Headcount is estimated to have risen sharply over 2023–2026, and multiple executive appointments (e.g., EVPs for Finance & Corporate Development and for Technology & Operations) were made to support scaling. Added locations and planned team growth in hubs like Chicago and New York further signal ongoing talent expansion.
Trusted by thousands of service businesses, FieldPulse is an all-in-one platform that gets your entire field service team on the same page, across the office and the field, so that time is focused on growing the business and serving customers. Built with customization at the center, FieldPulse is the only service management software that adapts to the unique ways each service...
FieldPulse's Top Stability & Growth Strengths
Strong Revenue Growth: Inc. 5000 placements show 652% three-year growth at #534 in 2026 (up from #774 in 2025), indicating sustained top-line expansion. Company announcements also cite 4× growth in 21 months and more than 100% year-over-year growth around its Series C.
Investor Backing & Capital Strength: A $50M Series C in August 2025, following a $21M Series B and totaling roughly ~$79–81M across rounds per multiple sources, underscores deep investor support. The funding progression alongside accelerated growth signals capacity to finance scaling initiatives.
Innovation-Driven Growth: The platform has added AI-driven capabilities such as Operator AI, voice tech integration, automated lead conversion tools, job costing, and enhanced mobile workflows. Series C proceeds were described as targeting AI product development and broader platform customization.

.png)
Apex Fintech Solutions provides the tools and services that enable hundreds of clients to launch, scale, and support digital investing for tens of millions of end investors. The company provides essential infrastructure and a comprehensive ecosystem of cloud-based products to enable and streamline trading, wealth management, cost basis, tax reporting, and, through its subsidiary Apex Clearing™, custody and clearing. For...

Apex Fintech Solutions's Top Stability & Growth Strengths
Product Line Growth: Product scope has widened beyond core clearing/custody, with launches such as Apex Ascend (real-time, cloud-native infrastructure), Apex Alts, and new capabilities like AI tools, prediction markets, and direct indexing, plus acquisitions including FinTron and AdvisorArch. These additions indicate a broader platform designed to serve more wealth-tech workflows and asset types.
Strategic Partnerships: Recent announcements highlight collaborations with major platforms and institutions, including Cash App Investing selecting Apex as a strategic clearing platform, Gemini choosing Apex for U.S. stock-trading custody/clearing, and integrations/alliances with Plaid, Google Cloud, and State Street. These relationships point to expanding distribution and external validation of the offering.
Strong Market Position & Advantage: Operating scale is substantial, with company-reported figures of hundreds of billions in assets under custody, tens of millions of accounts, and hundreds of millions of annual trades, alongside support for 200+ platforms. High-profile platform selections reinforce a durable position in digital investing infrastructure.
At Bestow, we’re on a mission to increase financial stability for everyone. We’re building the technology to modernize the life insurance industry and make things easier on everyone from consumers to carriers. It’s an audacious goal, sure. But we’re just crazy enough to pull it off.
Bestow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as having tripled in 2024 and increased roughly tenfold over two years, with ARR growth reported and profitability said to be approaching. Independent coverage echoes the same trajectory, reinforcing a picture of rapid top-line acceleration.
Investor Backing & Capital Strength: Capital position is reinforced by a $120 million Series D in May 2025 co-led by Goldman Sachs Alternatives and Smith Point Capital, alongside an additional credit facility and cumulative equity funding exceeding $300 million. The company indicates proceeds are being used to expand the platform across life and annuities.
Product Line Growth: Product scope is broadening from term-life technology into a fuller life-and-annuity platform, with new launches (e.g., indexed universal life) and numerous feature enhancements. Customer case studies describe meaningful sales lifts on Bestow-powered products, signaling traction across multiple lines.
We create technology that simplifies life for employees and helps our clients succeed.
Paycom's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue continues to rise year over year in recent quarters and full-year results, with outlooks pointing to continued increases. Reported client and volume expansion within its platform align with sustained top-line momentum.
Profitability: Margins and earnings performance are characterized as strong, aided by efficiency and automation. Reports also highlight robust operating performance alongside growth.
Innovation-Driven Growth: Demand for a unified, single-database HCM platform and product innovations like Beti are cited as drivers of expansion. Automation initiatives are described as supporting both product adoption and financial performance.
.png)
Navan (Nasdaq: NAVN) is the leading all-in-one business travel, payments, and expense management platform that makes travel easy for frequent travelers. From finding flights and hotels to automating expense reconciliation, with 24/7 support along the way, Navan delivers an intuitive experience travelers love and finance teams rely on. See how Navan customers benefit and learn more at navan.com.
Navan's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is scaling at strong double-digit rates, reaching $702M in FY2026 and continuing to rise in subsequent quarters, with full‑year FY2027 guidance lifted into the low‑$900M range. Multiple updates indicate momentum in both reported results and outlook.
Healthy Cash Flow: Operating cash flow turned positive in FY2026 and free cash flow was also positive, alongside progress in non‑GAAP profitability in later quarters. These milestones suggest improving financial efficiency as scale increases.
Diversified Customer Base: The company reports 12,500+ active customers and continued wins with large enterprises across technology, manufacturing, and healthcare. This breadth points to demand resilience across multiple industries.
Together, we turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Profitability: Investment performance is described as exceptional over multiple years, with LCH citing record cumulative net gains and annual investor profits including a record ~$16B in 2022 and further multibillion-dollar gains in 2023–2024. This track record positions the firm at or near the top of cumulative profitability rankings.
Strong Revenue Growth: Trading revenue at the affiliated market maker rose sharply, reaching a record ~$12.2B in 2025 and accelerating further with multi‑billion‑dollar quarters in 2026. This momentum indicates expanding top‑line scale alongside broader business activity.
Market Expansion: The geographic footprint is widening with Dubai slated as the 18th city, a growing London hub, and new or expanded sites such as New York, Miami, and Amsterdam. International hiring and build‑outs across Asia and Europe further reinforce expansion into additional markets.
NexGenTek provides enterprise technology solutions that help organizations grow, secure data, and manage digital transformation. Its structured delivery model integrates security, infrastructure, systems integration, data and AI, and software delivery under defined governance controls. The company supports complex technology environments through cybersecurity, cloud services, workflow automation, governed data platforms, operational AI, and enterprise software implementation, with an emphasis on controlled,...
Elixir Multinational is a leading provider of IT services and innovative solutions, dedicated to simplifying the complexities of technology to deliver intuitive and impactful outcomes. Our team of skilled and passionate engineers is committed to enabling client success and contributing to advancements in the global technology ecosystem. We aspire to be the trusted partner of choice for entrepreneurs and business...
Pinnacle Seven Technologies is an eminent firm that provides customizable business applications to various organizations around the globe. We specialize in providing reliable solutions using Cloud-Based Hybrid Technologies. We concentrate on providing intuitive, platform independent, productive and economical business workflow systems through our tools. These are built and delivered on your cloud which is highly approachable and simple to enable...

Kroll is the world’s premier provider of services and digital products related to valuation, governance, risk and transparency. We work with clients across diverse sectors in the areas of valuation, expert services, investigations, cyber security, corporate finance, restructuring, legal and business solutions, data analytics and regulatory compliance. Our firm has nearly 5,000 professionals in 30 countries and territories around the...
Kroll's Top Stability & Growth Strengths
Strong Market Position & Advantage: Multiple third-party descriptions and industry recognitions portray Kroll as a leading independent provider in financial and risk advisory, with top placements in areas like fairness opinions and investigations/forensics. Scale signals such as a global workforce and long operating history reinforce a durable competitive position.
Market Expansion: Evidence points to active expansion through new practices (e.g., Economics and Decision Intelligence), geographic build-outs, and acquisitions across regions including APAC, Europe, and Latin America. Announcements of added services and locations indicate an expanding footprint.
Diversified Revenue Streams: A broad portfolio spanning valuation, investigations, due diligence, compliance, cyber/MDR/IR, restructuring, and agency/trustee services suggests multiple demand drivers. Recognition across several distinct service lines implies revenue is not dependent on a single offering.
For 35 years, TCP Software has helped organizations engage their people by providing flexible workforce management solutions and mobile timekeeping. Trusted by 30,000 customers and millions of users, TCP delivers best-in-class technology and support to organizations of all sizes in the public and private sector to meet their complex employee scheduling, leave management, timekeeping and other workforce needs.

Zones is a Global Solution Provider of end-to-end IT solutions with an unmatched supply chain. Positioned to be the IT partner you need, Zones, a Minority Business Enterprise (MBE) in business for over 35 years, specializes in Digital Workplace, Cloud & Data Center, Networking, Security, and Managed/Professional/Staffing services. Operating in more than 120 countries, leveraging a robust portfolio, and utilizing the...