

Top Tech Companies in Bangalore (10,000+)
Wise is a global technology company, building the best way to move and manage the world's money. With Wise Account and Wise Business, people and businesses can hold 40 currencies, move money between countries and spend money abroad. Large companies and banks use Wise technology too; an entirely new network for the world's money. Launched in 2011, Wise is one...

Wise's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue continues to rise year over year in the latest full-year and quarterly updates, and management reiterates guidance for continued growth within its target range. This trajectory aligns with broad-based gains in customers, volumes, and account usage.
Profitability: Income before tax remains strong, and margin guidance is maintained alongside ongoing expansion. This points to profitable growth rather than growth at any cost.
Diversified Revenue Streams: A significant share of net revenue now comes from non‑transfer activities such as interest on customer balances, cards, and other account features. This mix reduces reliance on core cross‑border fees as usage of the account and platform deepens.
Wipfli is a leading national advisory and accounting firm with nearly 100 years of serving ambitious middle-market organizations. We understand our clients' unique challenges and help them succeed on their terms through assurance, tax, advisory, outsourcing and technology services. With 2,900+ associates and global alliances, we combine national capabilities with local relationships. "Wipfli" is the brand name under which Wipfli LLP...

Wipfli's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue has increased over consecutive fiscal years to $638.4 million in FY26, building on gains reported in FY24 and FY25. This points to continued top-line expansion.
Investor Backing & Capital Strength: A significant minority investment from New Mountain Capital was announced on August 1, 2025 to accelerate growth, technology and acquisitions under an alternative practice structure. This provides funding capacity to scale and pursue M&A.
Innovation-Driven Growth: The mix is shifting toward advisory and technology services (nearly half of revenue per the firm), with capability additions reinforcing this pivot. The CompliancePoint transaction further broadens cybersecurity, privacy and compliance offerings.
Skillsoft (NYSE: SKIL) is a global leader in AI-native skills management for the human + AI era. By unifying learning, real-time skills intelligence, and workforce insights, Skillsoft helps enterprises build their Skillforce™ — humans and AI working together to drive measurable business outcomes. Through personalized, interactive learning across leadership, technology, and compliance, Skillsoft enables organizations to close critical skill gaps...

Skillsoft's Top Stability & Growth Strengths
Customer Loyalty & Retention: Dollar Retention Rate reached 105% in Q1 FY2027, up from 91% a year earlier, signaling stronger expansion within existing accounts. New customer agreements on the Percipio platform also grew 67% quarter over quarter, reinforcing account health.
Innovation-Driven Growth: AI-driven learning usage expanded sharply (e.g., AI learners up 74%, total AI learning hours up 158%, and AI skill benchmark completions up 994%), indicating product innovation is resonating. Adoption of the next-generation, AI-native Percipio platform is accelerating as well.
Cost & Operational Efficiency: Adjusted EBITDA margin improved to 28% in Q1 FY2027 and free cash flow strengthened in recent quarters. Net loss narrowed 37% year over year, pointing to tighter operating discipline even on a smaller revenue base.
Wells Fargo & Company (NYSE: WFC) is a leading financial services company that has approximately $2.2 trillion in assets. We provide a diversified set of banking, investment and mortgage products and services, as well as consumer and commercial finance, through our four reportable operating segments: Consumer Banking and Lending, Commercial Banking, Corporate and Investment Banking, and Wealth & Investment Management....
Wells Fargo's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising year over year, with Q2 2026 up roughly 9% and broad-based increases across Consumer, Commercial, Corporate & Investment Banking, and Wealth. Management also points to continued momentum across both net interest income and fee businesses.
Profitability: Net income and EPS have increased (e.g., Q2 2026 net income around $6.4B and EPS up 25%), and full‑year 2025 earnings improved versus 2024. Efficiency gains contributed to better margins, including an improved efficiency ratio.
Cost & Operational Efficiency: Multi‑year efficiency initiatives, headcount reductions, and branch optimization have supported operating leverage and an efficiency ratio near 60%. The company emphasizes profit growth driven by productivity rather than staff expansion.
iManage is dedicated to Making Knowledge Work. Over one million professionals across 65+ countries rely on our intelligent, cloud-enabled, secure knowledge work platform to uncover & activate the knowledge that exists inside their business content and communications. We are continuously innovating to solve the most complex professional challenges & enable better business outcomes. Our work is not always easy but it...

iManage's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported up 42% year over year in 2024 with a further 28% uplift cited year‑to‑date in late 2025 and continued growth into 2026. Cloud ARR also rose strongly across 2023–2026, reinforcing top‑line momentum.
Market Expansion: New‑customer additions of 305 in 2024, 340 in 2025, and 90 early in 2026, alongside cloud adoption reaching 78% of the base, point to a widening footprint. Additional Azure regions (e.g., Switzerland) and thousands of organizations served further indicate expanded reach.
Innovation-Driven Growth: New AI‑powered offerings such as Ask iManage, iManage AI Enrichment, and Mailbox Assistant, plus secure MCP integrations, signal product‑led expansion. An expanded partnership with Thomson Reuters to deliver governed AI‑powered workflows underscores focus on AI‑enabled growth.
Since 2011, Remitly has been tirelessly delivering on our promises to our customers sending their hard earned money home. Today, we are incredibly proud to have served millions of customers globally. We strive daily to meet our promise to our customers by building peace of mind into everything we do. Join over 2,700 employees across 10 offices who are growing...
Remitly's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue reached roughly $495M in Q2 2026 (about 20% YoY), and the full-year 2026 outlook was raised to $1.978–$1.988B (about 21–22% growth). Active customers surpassed 10.2M and send volume grew ~27% YoY, reinforcing top-line momentum.
Profitability: Record Adjusted EBITDA ($114.7M, +79% YoY) and positive GAAP net income were reported in Q2 2026, with GAAP profitability achieved in 2025. Management has repeatedly raised 2026 Adjusted EBITDA guidance, indicating expanding margins at scale.
Product Line Growth: New offerings such as the Remitly Global Card, stablecoin wallet features, and Remitly Business (serving 25,000+ businesses by Q2 2026) are being rolled out. Expanded features like WhatsApp Send and “Request Money” aim to broaden engagement and add revenue vectors.
Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising rapidly across recent periods, with FY2026 results and the subsequent quarter both showing sharp year-over-year increases and strong subscription-led momentum. Management raised the FY2027 outlook following the latest quarter, underscoring continued demand.
Healthy Cash Flow: Free cash flow is meaningfully positive and improving at scale, including a healthy margin in Q1 FY2027 and a large year-over-year increase in FY2026. Improving subscription contribution margins indicate growing operating leverage.
Strong Market Position & Advantage: Independent analyst recognitions place the company among market Leaders for backup/data protection and cyber recovery, often highlighted for vision. Expanding large-customer cohorts and post-IPO scale further reinforce competitive standing.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue accelerated to about $1.60B in Q2 2026, up 19% year over year, following 12% growth in Q1 2026 and an 11% increase for full-year 2025. Rising ARPU alongside expanding DAU/MAU supported this top-line momentum.
Healthy Cash Flow: Q2 2026 free cash flow reached roughly $121M and operating cash flow improved to about $176M, both sharply higher year over year. These gains indicate improved operating efficiency even as GAAP net income remains negative.
Diversified Revenue Streams: “Other revenue” driven by subscriptions like Snapchat+ grew ~85% year over year in Q2 2026 (after ~87% in Q1), and Snapchat+ surpassed 25M subscribers by mid‑2026. This diversification is complementing ad recovery and helping sustain growth.
Cat Digital is the digital and technology arm of Caterpillar Inc., responsible for bringing digital capabilities to our world-famous yellow iron. With over 1.5M connected assets worldwide, our teams use data, technology, advanced analytics and AI capabilities to help solve our customers' toughest challenges.
Caterpillar's Top Stability & Growth Strengths
Strong Revenue Growth: Record quarterly revenue in Q2 2026 and double‑digit year‑over‑year gains in both Q1 and Q2, alongside a raised full‑year 2026 sales outlook, indicate accelerating top‑line momentum. Sales increased across Construction Industries, Resource Industries, and Power & Energy, supported by higher volume and favorable price realization.
Profitability: Operating and adjusted operating margins expanded versus the prior year in Q2 2026, with profit per share rising strongly. Segment profits improved alongside revenue, reflecting pricing power and scale benefits.
Healthy Cash Flow: Strong cash generation, including robust 2025 enterprise operating cash flow, underpinned an 8% dividend increase and substantial buybacks in 2026. These actions suggest financial flexibility to invest in growth while returning capital.

.jpg)
Acquia is the open digital experience company. We provide the world's most ambitious brands with products built around Drupal to allow them to embrace innovation and create customer moments that matter. At Acquia, we believe in the power of community and collaboration — giving our customers and partners the freedom to build tomorrow on their terms.

Acquia's Top Stability & Growth Strengths
Strong Market Position & Advantage: Placement as a Leader in Gartner’s 2024–2025 Magic Quadrant for Digital Experience Platforms and continued industry recognition indicate durable competitive standing. Ongoing Engage events and partner programs align with sustained enterprise adoption.
Innovation-Driven Growth: Active product expansion—such as the 2026 launches of Acquia AI and major Acquia Source updates, plus prior acquisitions like Monsido and Widen—shows continued investment in the platform. These moves broaden the DXP footprint across AI, DAM/PIM, and governance.
Customer Loyalty & Retention: Company retrospectives for 2022–2023 cite record renewal rates alongside multi‑year revenue increases. This points to a stable installed base that supports resilience through market cycles.

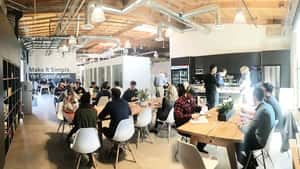
By automating and streamlining common accounting workflows to make them more efficient, FloQast is where accounting teams want to work so they can focus on what matters most, even when that’s just logging off on time. Whether automating reconciliations, documentation requests, or streamlining recurring accounting processes, such as the month-end close, financial reporting, or payroll, FloQast's platform enhances the way...
FloQast's Top Stability & Growth Strengths
Strong Revenue Growth: ARR reportedly rose from $100M in early 2024 to $200M by January 2026, indicating rapid top-line momentum driven by upmarket wins and adoption of AI agents. This step-up is reinforced by multi-year growth recognition such as Deloitte’s Technology Fast 500 placements.
Investor Backing & Capital Strength: A $100M Series E at a $1.6B post-money valuation in April 2024 provides substantial resources for continued product investment and international expansion. This late-stage funding signals confidence in the company’s scaling prospects.
Market Expansion: New offices in London and Sydney, stronger growth in EMEA, and the largest customer to date in Germany point to widening international reach. Alliances with firms such as EY further extend access to large finance transformation programs.
Taboola empowers businesses to grow through performance advertising technology that goes beyond search and social and delivers measurable outcomes at scale. Taboola works with thousands of businesses who advertise directly on Realize, Taboola’s powerful ad platform, reaching approximately 600M daily active users across some of the best publishers in the world. Publishers like NBC News, Yahoo, and OEMs such as Samsung,...

Taboola's Top Stability & Growth Strengths
Profitability: Adjusted EBITDA and ex‑TAC gross profit are rising at double‑digit rates, with Q2 margins expanding and management raising full‑year profitability guidance. This points to increasing operating leverage even as mix shifts favor higher‑margin revenue.
Strategic Partnerships: A 30‑year exclusive native‑ads agreement with Yahoo is live globally and framed as a multi‑year growth driver with sizable revenue potential. Recent publisher wins such as Fox News further extend distribution that supports current results and the outlook.
Innovation-Driven Growth: Momentum in the Realize performance offering and AI initiatives like DeeperDive are cited as contributors to improved results and raised guidance. These offerings indicate continued product evolution beyond classic native formats.
At Rapid7, our vision is to create a secure digital world for our customers, our industry, and our communities. We do this by harnessing our collective expertise and passion to challenge what’s possible and drive extraordinary impact. We’re building a dynamic and collaborative workplace where new ideas are welcome. Protecting 11,000+ customers against bad actors and threats means we’re continuing...
Rapid7's Top Stability & Growth Strengths
Profitability: Q2 2026 delivered positive GAAP operating income of $3.0M and non‑GAAP operating income of $28.9M, with management raising the 2026 non‑GAAP operating income outlook. This indicates margin improvement even as the top line softens.
Healthy Cash Flow: Free cash flow was $31.9M in Q2 2026 and management is targeting around $125–$135M for full‑year 2026. This ongoing cash generation underscores improved efficiency during a reset year.
Investor Backing & Capital Strength: Cash and short‑term investments increased to about $703M as of June 30, 2026, up from roughly $657M at year‑end 2025. This liquidity provides flexibility amid slower ARR and revenue trends.
Headquartered in New York City, Take-Two Interactive Software, Inc. is a leading developer, publisher, and marketer of interactive entertainment for consumers around the globe. We develop and publish products principally through Rockstar Games, 2K, and Zynga. Our strategy is to create hit entertainment experiences, delivered on every platform relevant to our audience through a variety of sound business models. Our...
Take-Two Interactive Software's Top Stability & Growth Strengths
Strong Revenue Growth: GAAP net revenue rose 18% to $6.66 billion in FY2026, and an initial FY2027 net bookings outlook of $8.0–$8.2 billion implies further scale. In Q1 FY2027, GAAP net revenue also increased year over year and bookings slightly exceeded guidance.
Diversified Revenue Streams: Live services and in‑game purchases comprised the majority of Q1 FY2027 revenue and bookings, helping to smooth results between major releases. The expanded mobile footprint following the Zynga acquisition adds a meaningful second pillar beyond premium console/PC titles.
Future-Ready Strategy: Management has tied FY2027 scale to the November 19, 2026 launch of Grand Theft Auto VI while reaffirming bookings guidance. A successful release is positioned to materially lift results.

LogicMonitor® is the AI-first hybrid observability platform powering the next generation of digital infrastructure. LogicMonitor delivers complete visibility and actionable intelligence across on-premises, cloud, and edge environments. By anticipating issues before they strike, optimizing resources in real time, and enabling faster, smarter decisions, LogicMonitor helps IT and business leaders protect margins, accelerate innovation, and deliver exceptional digital experiences without compromise....

LogicMonitor's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is described as rising from over $300M in 2025 to over $400M by mid-2026, alongside large-scale telemetry usage that signals expanding adoption. This trajectory indicates sustained top-line expansion through 2026.
Innovation-Driven Growth: AI-led capabilities such as Edwin AI are portrayed as a meaningful driver of bookings with rapid recurring revenue momentum, and the company is advancing an “Autonomous IT” roadmap. Continued AI feature launches through 2026 point to product-led expansion.
Investor Backing & Capital Strength: An $800M financing in late 2024 at around a multi‑billion valuation provides resources to accelerate platform expansion, acquisitions, and entry into new markets. This capital base supports ongoing scaling initiatives.
Our platform creates comprehensive digital twins of your supply chain with AI-powered digital workers to automate resolution, improve collaboration and drive outcomes across all stakeholders. Unlike traditional control towers, we enable true real-time execution and intelligent fulfillment, transforming both your supply and customer-facing operations.
FourKites's Top Stability & Growth Strengths
Diversified Customer Base: Customer count expanded from more than 1,200 brands in 2023 to 1,600+ by 2026, indicating broader adoption across regions and modes.
Innovation-Driven Growth: Multiple 2026 launches—Loft AI, Inventory Twin enhancements, and an agentic ocean booking platform—signal an active roadmap and continued go‑to‑market motion.
Strong Market Position & Advantage: Being named a Leader in Gartner’s 2024 Magic Quadrant for RTTVPs reflects established competitive standing heading into 2025.

M-Files is redefining how work gets done. Our context-first document management system offers purpose-built business use cases—spanning universal and industry-specific workflows—to enable secure collaboration, automate processes, and ensure governance. Unlike traditional systems, M-Files organizes content around the context of your business, connecting documents to related people, projects, and transactions. With our unique metadata-driven architecture, organizations can model content in line...

M-Files's Top Stability & Growth Strengths
Strong Revenue Growth: ARR and bookings are described as at record levels in 2025, building on the $100M ARR milestone achieved in 2023. Company updates point to continuing ARR expansion through 2025.
Market Expansion: Nearly 500 new customers added during 2025 indicates healthy net-new adoption and broadening reach. Enhanced partner programs and Microsoft 365 alignment are positioned to open additional routes to market.
Strategic Partnerships: An expanded Microsoft partnership in 2025 positions the platform more natively within Microsoft 365. This alignment is framed as a catalyst for pipeline generation and upsell.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Total revenue increased 19% in FY2026 and 16% in Q1 FY2027, while ARR reached about $2.14B, up roughly 17% year over year. Net‑new ARR also accelerated, signaling strengthening demand.
Profitability: Non‑GAAP operating income was $592M in FY2026 with ~29% margin, and Q1 FY2027 reported a ~29% margin alongside robust adjusted free cash flow. Free cash flow for FY2026 was $529M, underscoring strong operating leverage.
Resilient & Sustainable Growth: Multi‑year double‑digit ARR and revenue expansion, record large deals, and 41% organic net‑new ARR growth in Q1 FY2027 point to durable demand. A subscription‑led model and fast‑growing logs consumption support ongoing platform adoption.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Strong Revenue Growth: Consolidated revenues increased from $253 billion in 2024 to $270.6 billion in 2025, with quarterly gains such as Q4 2025 up 8% year over year. Growth was led primarily by Optum Rx and supported by steady contributions from Optum Insight.
Market Expansion: Expansion through acquisitions such as Holston Medical Group (August 2025) and Alegeus (July 2026), alongside earlier combinations like Change Healthcare and Atrius Health, broadened capabilities across care, pharmacy, and payments. These moves extend Optum’s platform into adjacent services and operating domains.
Diversified Revenue Streams: A multi-segment model—Rx, Insight, and Health—helps sustain aggregate growth even as individual lines vary, with pharmacy and technology businesses offsetting care-delivery softness. Parent-company commentary continuing to frame Optum as a growth engine and raising 2026 guidance underscores the benefit of this portfolio effect.
CDW Corporation is a leading multi-brand provider of information technology solutions to business, government, education and healthcare customers in the United States, the United Kingdom and Canada. A Fortune 500 company and member of the S&P 500 Index, CDW helps its customers to navigate an increasingly complex IT market and maximize return on their technology investments. For more information about...

CDW's Top Stability & Growth Strengths
Strong Revenue Growth: Net sales rose 6.8% in 2025 to $22.4B and accelerated to 9.2% in Q1 2026 and 10.0% in Q2 2026, with non‑GAAP EPS also increasing. Management continues to target outgrowing the U.S. IT addressable market by 200–300 bps.
Diversified Customer Base: Growth was broad across Commercial (+9.2%), Government (+13.6%), Education (+0.7%), and international “Other” (+22.9%) in Q2 2026, with 2025 gains led by Small Business, Corporate, and UK/Canada. This breadth helps smooth spending cycles and supports share gains.
Healthy Cash Flow: Regular capital returns continued, highlighted by a $0.63 quarterly dividend declared for September 10, 2026. Operating income and non‑GAAP earnings increased, indicating ongoing cash generation to fund dividends.



