

Top Tech Companies in Bangalore (10,000+)

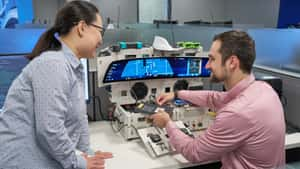
At General Motors, our vision is to create a world with Zero Crashes, Zero Emissions, and Zero Congestion. We wholeheartedly embrace the responsibility to lead the change that will make our world better, safer, and more equitable for all. Our industry and company are undergoing a once-in-a-lifetime technological transformation, which is reshaping our approach to technology and innovation. We are expanding...
General Motors's Top Stability & Growth Strengths
Profitability: Profit metrics and margins are rising in 2026, with Q2 EBIT‑adjusted up ~30% to $3.94B and the margin improving to 8.2%, alongside a first‑half margin of 8.9%. Management also raised full‑year 2026 profit guidance to $14–$16B, reflecting stronger earnings power driven by mix, pricing, and cost discipline.
Healthy Cash Flow: Adjusted automotive free cash flow grew sharply (up 78% in Q2 and 73% year to date), and the company reinforced confidence by declaring a $0.18 quarterly dividend and authorizing a $6B buyback. These capital returns accompany higher full‑year free‑cash‑flow guidance of $9.5–$11.5B.
Diversified Revenue Streams: Software‑enabled services and subscriptions are contributing more meaningfully, with roughly 620,000 subscribers, $5.4B of deferred revenue at 2025 year‑end, and OnStar revenue up ~20% year over year in Q2 2026. The company indicates software revenue is on track to exceed $3B in 2026.
We are a mobility company that innovates like a start-up and thinks like a technology company. This helps us anticipate change in one of the most complex industries in the world and respond quickly. We depend on a team of 171,000 dynamic, entrepreneurial-minded employees in an environment where great ideas flourish. Our presence spans 343 manufacturing operations and 88 product...

Magna International's Top Stability & Growth Strengths
Profitability: Q2 2026 results show adjusted EBIT up 16%, margin up 70 bps to 6.2%, and adjusted EPS up 29% to a Q2 record $1.86. Following Q2, management raised the 2026 adjusted EPS outlook, signaling confidence in continued margin expansion.
Healthy Cash Flow: Free cash flow more than doubled year over year to $617M in Q2 2026, reaching $989M for the first half. The full-year 2026 outlook calls for approximately $1.75–$1.85B of free cash flow.
Cost & Operational Efficiency: Cost actions and productivity improvements are expanding margins and boosting earnings. Mix shift toward higher‑margin programs and recent wins support organic growth into future periods.
We're honored to be No. 10 on Great Place to Work's World's Best Workplaces and recognized in the Fortune 100 Best Companies to Work For® list in 2025. At MetLife, we're leading the global transformation of an industry we’ve defined for over 157 years. At MetLife, every innovation and line of code is a lifeline for our customers and their...

MetLife's Top Stability & Growth Strengths
Profitability: Adjusted EPS advanced at a double‑digit pace in both Q1 and Q2 2026, with adjusted ROE at the high end of the target range, supported by favorable underwriting and stronger net investment income. Capital deployment remained robust alongside these gains.
Future-Ready Strategy: Management’s “New Frontier” plan targets sustained double‑digit adjusted EPS growth and mid‑teens adjusted ROE through 2029. Expansion of fee‑based earnings via MetLife Investment Management—now scaled into the hundreds of billions of AUM with a stated path toward roughly $1T—supports the plan.
Diversified Revenue Streams: Broad‑based momentum across Group Benefits, Retirement & Income Solutions, Asia, Latin America, EMEA, and MIM lifted adjusted earnings and revenue‑related metrics in early 2026. Underlying PFO growth excluding episodic pension risk transfers outpaced headline totals, indicating multiple engines of growth.
Adyen (ADYEN:AMS) is the financial technology platform of choice for leading companies. By providing end-to-end payments capabilities, data-driven insights, and financial products in a single global solution, Adyen helps businesses achieve their ambitions faster. With offices around the world, Adyen works with the likes of Meta, Uber, H&M, eBay, and Microsoft.
Adyen's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue is rising at a double‑digit pace across FY 2025 and into H1 2026, with guidance indicating continued momentum on a constant‑currency basis. Growth is supported by expansion with existing enterprise customers and new wins across regions and pillars.
Profitability: EBITDA margins remain high alongside strong free cash flow conversion, indicating solid operating leverage even as the company scales. Multi‑year margin ambitions are reaffirmed, signaling confidence in sustained earnings quality.
Product Line Growth: AI‑focused launches and the additions of Talon.One and Orb broaden the platform beyond core payments into loyalty, promotions, and usage‑based billing. These moves point to a widening solution set aimed at deeper share of wallet with enterprises.
Vantor is forging the new frontier of spatial intelligence to unlock a more autonomous, interoperable world. We empower decision makers and operators with the clarity they need to navigate what’s happening now and shape what’s coming next. Our AI-powered spatial intelligence platform fuses data from the world’s highest-resolution satellites with real-time sensor feeds from space, air, and ground to create...
Vantor's Top Stability & Growth Strengths
Innovation-Driven Growth: Recent moves pair a planned constellation expansion that combines higher-resolution imaging with higher revisit rates with an AI-centric platform and new 3D offerings. Together, these signal movement up the value chain toward higher-margin software and systems.
Market Expansion: Statements highlight expanding international activity, including a Bundeswehr-focused joint effort, more than a dozen new European customers in 2025, and 60+ government partners. These point to growing geographic reach and customer adoption.
Strategic Partnerships: Collaborations such as a German JV with Rheinmetall for ISR data integration and a build partnership with BAE Systems on next-generation satellites indicate deepening ecosystem ties. Such alliances can accelerate access to new programs and markets.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent analysts continue to place Qualtrics at the front of its market, with Gartner naming it a Leader in the Magic Quadrant for Voice of the Customer Platforms and positioning it highest on Ability to Execute and furthest on Completeness of Vision. This standing typically aligns with robust enterprise demand and supports commercial momentum.
Market Expansion: The company closed a $6.75 billion acquisition of Press Ganey Forsta on May 18, 2026, materially expanding its healthcare experience footprint and enlarging its data assets. Such scope increases are noted as common precursors to revenue growth and broader vertical penetration.
Innovation-Driven Growth: Qualtrics highlights rapidly expanding AI capabilities and analysis of billions of interactions annually, with usage of AI features surging and adoption widespread among large enterprise accounts. This product momentum supports upsell and cross‑sell into the installed base.
Zynga was founded in 2007 with the vision that play would become one of the core activities on the Internet. We pioneered social games with the belief that if we could make games simple, accessible and social the world would start playing. We are excited that games have grown to become the second most popular activity by time spent, even...
Zynga's Top Stability & Growth Strengths
Strong Revenue Growth: FY2026 net bookings rose 19% to $6.72B, with mobile (largely Zynga) increasing to about $3.33B from roughly $2.94B. Q4 FY2026 delivered record mobile net bookings of ~$829M, reinforcing full‑year momentum.
Strong Market Position & Advantage: Mobile, driven by Zynga, represented roughly half of company bookings, and independent tallies place Take‑Two/Zynga among the global top tier of mobile publishers by IAP revenue. Portfolio breadth across titles like Toon Blast, Match Factory!, Empires & Puzzles, Words With Friends, and Zynga Poker supports that positioning.
Product Line Growth: Management highlighted strong title performance (e.g., Toon Blast up ~26% YoY) and initiatives such as Zynga Poker’s PC/Steam launch and expanding direct‑to‑consumer channels. Announced pipeline items (e.g., CSR 3, Top Goal) and plans for additional mobile launches indicate continued slate expansion.
Accuris gives engineers trusted answers, not just access. Our Engineering Intelligence platform combines verified data, actionable insights, and purpose-built workflows — so technical and business leaders can move faster, reduce risk, and make decisions they can defend.

Accuris's Top Stability & Growth Strengths
Strong Revenue Growth: Company communications describe substantially accelerated revenue growth in 2024 with “exceptional momentum” continuing into Q1 2025 and performance on track to exceed financial targets. These statements align with concurrent product launches and go-to-market investments.
Product Line Growth: Multiple new offerings and upgrades—such as Accuris Thread (2025), an AI Assistant (2026), AI-powered BOM Intelligence (2026), and Engineering Workbench enhancements—signal sustained investment in the roadmap. This cadence broadens solution scope and supports upsell and cross-sell potential.
Market Expansion: A new global headquarters in Denver and additional offices in the UK, India, Malaysia, and Japan indicate an expanding geographic footprint. Senior commercial hires (e.g., a CRO in 2025 and a Head of Sales, Americas in 2026) further suggest scaling sales capacity.
Dscout helps companies better understand the experiences people have with their products and brands in everyday life. Our SaaS video research platform helps our customers gather, manage, share and analyze millions of in-context moments submitted by people around the world.
Dscout's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $70M Series C in March 2022 indicates capital in place to scale product and go-to-market over a multi-year window. This runway supports continued investment without reliance on new external rounds in the near term.
Market Expansion: The acquisition of Panelfox and the establishment of a U.K. presence led by a new MD signal movement beyond the core U.S. base. These steps broaden geographic reach and deepen recruiting/workflow capabilities.
Innovation-Driven Growth: Being named a Leader in Forrester’s Experience Research Platforms Wave (2023) alongside a steady cadence of new features through 2026 point to sustained R&D momentum. AI-focused launches such as AI Studio further reinforce a forward-looking roadmap.

Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising rapidly across recent periods, with FY2026 results and the subsequent quarter both showing sharp year-over-year increases and strong subscription-led momentum. Management raised the FY2027 outlook following the latest quarter, underscoring continued demand.
Healthy Cash Flow: Free cash flow is meaningfully positive and improving at scale, including a healthy margin in Q1 FY2027 and a large year-over-year increase in FY2026. Improving subscription contribution margins indicate growing operating leverage.
Strong Market Position & Advantage: Independent analyst recognitions place the company among market Leaders for backup/data protection and cyber recovery, often highlighted for vision. Expanding large-customer cohorts and post-IPO scale further reinforce competitive standing.
Motive builds technology to improve the safety, productivity, and profitability of businesses that power the physical economy. The Motive Automated Operations Platform combines IoT hardware with AI-powered applications to automate vehicle and equipment tracking, driver safety, compliance, maintenance, spend management, and more. Motive serves more than 120,000 businesses, across a wide range of industries including trucking and logistics, construction, oil...
Motive's Top Stability & Growth Strengths
Strong Revenue Growth: ARR rose from $338M (2023) to $417M (2024) and reached $501M by September 30, 2025, alongside revenue growth of 19% in 2024 and 22% for the first nine months of 2025. Growth in large customers—from 234 (2023) to 349 (2024) and 494 by September 2025—supports continued scale.
Investor Backing & Capital Strength: The company secured $150M in July 2025 to accelerate AI development and international expansion. This capital underpinned new product launches (e.g., Motive Analytics) and broader go‑to‑market efforts.
Customer Loyalty & Retention: Enterprise net revenue retention was cited above 127%–130%, and ARR from customers spending over $100K more than doubled since 2024. Multi‑product penetration also deepened, with 89% of Core Customers using at least two products and 40% using three or more by September 30, 2025.
.jpeg)
We are a world leader in innovative memory solutions that transform how the world uses information to enrich life for all. For over 45 years, our company has been instrumental to the world’s most significant technology advancements, delivering optimal memory and storage systems for a broad range of applications.

Micron Technology's Top Stability & Growth Strengths
Strong Revenue Growth: Record fiscal Q3 2026 revenue of $41.46B with GAAP net income of $28.24B and guidance to roughly $50B for Q4 signal sharp top-line acceleration. Momentum spans data center, client/mobile, and automotive/embedded, reflecting broad-based demand.
Innovation-Driven Growth: Emphasis on high-bandwidth memory and advanced DRAM/NAND for AI data centers, including 1‑gamma DDR5 RDIMMs and an HBM4/HBM4E roadmap, anchors growth in the fastest-ramping segments. Company materials and Computex updates highlight next‑gen shipments and timelines aligned to AI infrastructure build‑outs.
Strategic Partnerships: Long‑term strategic customer agreements with automotive players (e.g., Qualcomm, HARMAN, Hyundai Mobis, Ford) and collaborations with Intel and AMD enhance demand visibility and ecosystem reach. New U.S. commitments of up to $3B to strengthen the semiconductor ecosystem underscore expanding supply‑chain partnerships.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Total revenue increased 19% in FY2026 and 16% in Q1 FY2027, while ARR reached about $2.14B, up roughly 17% year over year. Net‑new ARR also accelerated, signaling strengthening demand.
Profitability: Non‑GAAP operating income was $592M in FY2026 with ~29% margin, and Q1 FY2027 reported a ~29% margin alongside robust adjusted free cash flow. Free cash flow for FY2026 was $529M, underscoring strong operating leverage.
Resilient & Sustainable Growth: Multi‑year double‑digit ARR and revenue expansion, record large deals, and 41% organic net‑new ARR growth in Q1 FY2027 point to durable demand. A subscription‑led model and fast‑growing logs consumption support ongoing platform adoption.
Cisco ThousandEyes is a Digital Experience Assurance platform that empowers organizations to deliver flawless digital experiences across every network – even the ones they don’t own. Powered by AI and an unmatched set of cloud, internet and enterprise network telemetry data, ThousandEyes enables IT teams to proactively detect, diagnose, and remediate issues – before they impact end- user experiences. ThousandEyes...
Cisco ThousandEyes's Top Stability & Growth Strengths
Strong Revenue Growth: Cisco’s filings indicate Observability revenue rose year over year, with Q2 FY2026 growth “primarily driven by growth in ThousandEyes,” and 6% growth for the full year—pointing to a continued positive trend. This suggests ThousandEyes is expanding its contribution within Cisco’s Observability category.
Product Line Growth: New capabilities and positioning—including updated Internet/Cloud Intelligence pages and broadband/ISP assurance showcased at MWC 2026—show ongoing investment and widening use cases. The cadence of launches indicates active development rather than stagnation.
Innovation-Driven Growth: Deepening integrations across Meraki/Catalyst and Internet Insights and a push toward end‑to‑end digital experience assurance align with rising cloud/SaaS reliance. These moves reflect a forward‑leaning roadmap aimed at broader, outcome‑oriented visibility.

CrowdStrike has redefined security with the world’s most advanced cloud-native platform that protects and enables the people, processes and technologies that drive modern enterprise. Tested and proven, the world's largest organizations trust CrowdStrike to stop breaches with unparalleled protection against the most sophisticated cyberattacks. The CrowdStrike culture has been built upon our Core Values since the day we began. We...
CrowdStrike's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose 26% year over year to $1.39B in Q1 FY2027, while ARR grew 24% to $5.51B with record net new ARR. Management also raised FY2027 revenue and ARR guidance, indicating confidence in continued double‑digit expansion.
Profitability: GAAP profitability was achieved in Q1 FY2027 (diluted EPS $0.11) alongside higher non‑GAAP earnings, reflecting operating leverage at scale. Prior periods also highlighted improving profit metrics, reinforcing an upward profitability trend.
Healthy Cash Flow: Cash generation reached record levels in Q1 FY2027 with $591M in operating cash flow and $468.5M in free cash flow. FY2026 likewise set records for operating and free cash flow, underscoring durable unit economics.

About Coursera: Coursera was launched in 2012 by Andrew Ng and Daphne Koller with a mission to provide universal access to world-class learning. Coursera partners with leading university and industry partners to offer a broad catalog of content and credentials, including courses, Specializations, Professional Certificates, and degrees. Coursera’s platform innovations — including AI-powered personalized guide and features, like Role Play and...
Coursera + Udemy 's Top Stability & Growth Strengths
Strong Revenue Growth: As-reported results show a sharp top-line increase after the Udemy close, and management lifted the full-year outlook. Enterprise and consumer segments contributed to this momentum, with improving adjusted EBITDA indicating better near-term operating performance.
Strong Market Position & Advantage: The merged platform now spans hundreds of millions of learners and tens of thousands of enterprise relationships, creating meaningful cross-sell and data advantages. This breadth across consumer, enterprise, and credentialed offerings strengthens defensibility versus peers.
Cost & Operational Efficiency: Management targets substantial run-rate synergies by year-end 2026 and has signaled margin expansion as integration progresses. Early signs include higher adjusted EBITDA and clear plans to rationalize overlapping costs.

CWAN was founded on a simple belief: investment professionals deserve modern technology that actually works for them. Not legacy systems that slow them down. Not fragmented data that creates confusion. But one comprehensive platform that gives you complete visibility and crystal-clear insights. The result? Investment management that works as seamlessly as your investment strategy. Since our founding in 2004, CWAN has been...

Clearwater Analytics (CWAN)'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating sharply across late 2025 and early 2026, with multiple consecutive quarters of substantial year-over-year gains. Annualized recurring revenue expanded materially over the same periods, reinforcing momentum.
Customer Loyalty & Retention: Client relationships appear sticky, with strong gross retention and ongoing net expansion across the base. Management also notes over 2,500 clients by year-end 2025, pointing to low churn and healthy upsell.
Healthy Cash Flow: Operating cash flow is described as strong alongside rising adjusted EBITDA with healthy margins. These trends suggest increasing capacity to fund integration and platform investments.
DigitalOcean is the Inference Cloud — a full-stack, production-ready cloud platform built to run AI applications with predictable performance, sustainable economics, and radically simpler operations at scale. We are built for teams turning AI into real products — not just training models. Our advantage is not fewer features, but fewer failure modes when operating AI at scale — combining minimal...

DigitalOcean's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue growth is accelerating with Q2 2026 up ~29% year over year and full-year 2026 guidance raised to about 30–31% growth. Management also points to a 35%+ exit rate in Q4 2026 and stronger momentum into 2027.
Innovation-Driven Growth: Recent AI‑Native Cloud launches (15+ new offerings across infrastructure, inference, data, and agents) are credited with fueling demand. AI customer ARR rose sharply in 2026, and record incremental ARR underscores product‑led momentum.
Customer Loyalty & Retention: Net Dollar Retention improved to roughly 101% in late 2025 and 102% in Q2 2026, indicating expanding spend among existing customers. Growing multi‑year commitments, with RPO nearing $900M, add visibility to that expansion.
SmartBear delivers application integrity for modern tech stacks, ensuring continuous, measurable assurance that software just works as intended – with governance to operate at AI speed and scale. SmartBear offers deep test automation, API lifecycle management, and observability capabilities. With integrations across the SDLC, it sets a new quality standard for application delivery teams. SmartBear is trusted by more than...
SmartBear's Top Stability & Growth Strengths
Innovation-Driven Growth: AI-centric releases across TestComplete (Vision AI), ReadyAPI (AI test generation), Swagger governance, and integrations with Anthropic’s Claude, Atlassian, and GitHub indicate active R&D and platform expansion. The 2026 cadence suggests the portfolio is evolving in step with current demand and developer workflows.
Strategic Partnerships: Ecosystem moves—including deep integrations with Atlassian and GitHub, channel enablement highlighted in trade coverage, and Atlassian Partner of the Year recognition for AI innovation—signal growing leverage through partners and channels. These efforts expand distribution and embed capabilities where teams already work.
Investor Backing & Capital Strength: Ownership by Francisco Partners and investment from Vista Equity Partners provide capital support consistent with scaling and roll-up strategies. This backing underpins ongoing M&A (e.g., Reflect, QMetry) and the resources to integrate and broaden the platform.
iManage is dedicated to Making Knowledge Work. Over one million professionals across 65+ countries rely on our intelligent, cloud-enabled, secure knowledge work platform to uncover & activate the knowledge that exists inside their business content and communications. We are continuously innovating to solve the most complex professional challenges & enable better business outcomes. Our work is not always easy but it...

iManage's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported up 42% year over year in 2024 with a further 28% uplift cited year‑to‑date in late 2025 and continued growth into 2026. Cloud ARR also rose strongly across 2023–2026, reinforcing top‑line momentum.
Market Expansion: New‑customer additions of 305 in 2024, 340 in 2025, and 90 early in 2026, alongside cloud adoption reaching 78% of the base, point to a widening footprint. Additional Azure regions (e.g., Switzerland) and thousands of organizations served further indicate expanded reach.
Innovation-Driven Growth: New AI‑powered offerings such as Ask iManage, iManage AI Enrichment, and Mailbox Assistant, plus secure MCP integrations, signal product‑led expansion. An expanded partnership with Thomson Reuters to deliver governed AI‑powered workflows underscores focus on AI‑enabled growth.



