

Top Payments Companies With Best Stability & Growth (2,347)
Mastercard powers economies and empowers people in 200+ countries and territories worldwide. Together with our customers, we’re building a resilient economy where everyone can prosper. We support a wide range of digital payments choices, making transactions secure, simple, smart and accessible. Our technology and innovation, partnerships and networks combine to deliver a unique set of products and services that help...

Mastercard's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue rose at double‑digit rates in 2025 and continued to increase at a similar pace in early 2026, supported by higher gross dollar volume, cross‑border activity, and switched transactions. The multi‑quarter trend indicates consistent top‑line momentum rather than a one‑off spike.
Profitability: Operating income outpaced revenue growth in 2025, expanding margins, while net income and EPS also advanced strongly. This points to operating leverage as volumes and higher‑yield cross‑border flows scale.
Diversified Revenue Streams: Value‑added services and solutions grew markedly faster than the core network, with security, digital authentication, analytics, and consulting cited as key contributors. This mix shift broadens growth beyond card payment fees and supports resilience.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating income has risen materially alongside growth, with the latest quarter reporting meaningful GAAP and adjusted operating profits and expanding margins. This indicates the business is scaling while improving earnings quality.
Resilient & Sustainable Growth: Gross profit is expanding at a strong, accelerating pace, with both Cash App and Square contributing and management raising full‑year outlooks. Longer‑term disclosures also highlight multi‑year compounding in gross profit per user across ecosystems.
Cost & Operational Efficiency: A leaner organizational structure and disciplined spending have driven record adjusted operating margins and improved operating leverage. Efficiency gains appear to be a second engine alongside revenue drivers.
As the foundation for secure markets, OCC is a customer-driven organization that delivers world-class Risk Management, Clearing, and Settlement Services for a sophisticated mix of financial products that includes standard options, stock loans, and futures contracts.
The Options Clearing Corporation (OCC)'s Top Stability & Growth Strengths
Strong Revenue Growth: Financial statements indicate total revenue rose from $499.7M in 2024 to $737.5M in 2025, with clearing‑fee revenue increasing materially over the same period. Operating data into 2026 shows elevated activity levels, consistent with continued top‑line momentum.
Profitability: Net income increased from $70.2M in 2024 to $190.7M in 2025, and operating income shifted from losses in prior years to a positive result. This reflects improved earnings alongside higher clearing volumes.
Resilient & Sustainable Growth: Contracts cleared reached record levels in 2025 and continued to expand into 2026, while the securities‑lending program also grew in value and transactions. Multi‑year trends from 2020 to 2025 show options activity more than doubling, indicating durable expansion.

REPAY is a full-service payment technology and processing provider that enables the expedient and secure collection of payments through any channel at any time. Our omnichannel payment platform provides direct integration with enterprise management systems and access to a suite of payment solutions, including credit/debit card processing, ACH processing, Instant Funding, IVR/phone pay, text pay, electronic bill payment and presentment...
REPAY's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show clear acceleration, with reported revenue rising strongly and organic growth remaining positive, while late‑2025 normalized trends also improved. Management’s outlook indicates continued growth through 2026.
Market Expansion: Scale and reach expanded meaningfully through the KUBRA acquisition, adding breadth across bill‑payment verticals and materially increasing overall platform activity. Distribution indicators such as software relationships and the AP supplier network also grew markedly.
Healthy Cash Flow: Cash generation is solid, highlighted by substantial free cash flow and strong conversion in the latest quarter. Adjusted profitability also improved alongside the expanding revenue base.
Moov is a payments infrastructure platform making it easy to accept, store, send, and spend money all from a single, elegantly-designed API. Instead of stitching together multiple vendors, software companies simply add Moov to their products to get the latest in payment technology, user onboarding, licensing, compliance, and more.
Moov's Top Stability & Growth Strengths
Product Line Growth: Current materials show support for accepting payments, bank payments, wallets, issuing cards, payouts, account verification, and multiple rails including ACH, RTP, and FedNow, positioning the company as infrastructure rather than only a card processor. This broader workflow coverage can increase payment volume per customer and create more acquisition opportunities.
Strategic Partnerships: Recent announcements and legal documents reference collaborations with institutions such as Jack Henry, Visa Direct, Coinbase, SouthState Bank, and Veridian Credit Union. These relationships extend distribution into community and regional financial institutions and reinforce enterprise readiness.
Investor Backing & Capital Strength: The funding trajectory progressed from a $5.5M seed and $27M Series A in 2020 to a $45M Series B in 2023 led by Commerce Ventures with participation from Andreessen Horowitz, Bain Capital Ventures, and Visa. This pattern signals sustained access to capital aligned with scaling the business and infrastructure.
Wise is a global technology company, building the best way to move and manage the world's money. With Wise Account and Wise Business, people and businesses can hold 40 currencies, move money between countries and spend money abroad. Large companies and banks use Wise technology too; an entirely new network for the world's money. Launched in 2011, Wise is one...
Wise's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue increased 19% in FY2026 to about $2.5bn and rose a further 25% year over year to $714m in Q1 FY2027, indicating continued top-line momentum. Growth is broad-based alongside rising customers and cross-border volumes.
Profitability: Income before tax reached roughly $660m in FY2026, equating to a 26% margin while volumes and usage scaled. Profitability held even as the company reduced take rates to remain competitive.
Diversified Revenue Streams: Card spend grew 37% to ~$44bn and customer holdings rose ~40% to ~$39bn in FY2026, with card and other revenue also expanding, indicating monetization beyond transfer fees. Wise Platform partnerships with banks further extend revenue sources beyond direct consumer transfers.
Circle (NYSE: CRCL) is a global, internet financial platform company powering the foundation of an open, borderless, and programmable economy. Circle connects financial institutions, enterprises, and developers to the next generation of the internet financial system through digital assets such as USDC, Circle Payments Network for global money movement, and Arc, an enterprise-grade blockchain designed to become the Economic OS...

Circle's Top Stability & Growth Strengths
Profitability: Adjusted EBITDA more than doubled to $582M in FY2025 and increased again in Q2 2026, indicating improving operating earnings. Pay is considered strengthened further by FY2025 operating earnings outpacing revenue growth.
Diversified Revenue Streams: Other revenue grew 41% in Q2 2026, while the company is expanding payments, tokenized assets, the Circle Payments Network, and its Arc blockchain. Feedback suggests this reflects progress beyond a single revenue source.
Strong Market Position & Advantage: USDC circulation and usage continued to rise (e.g., $73.3B in Q2 2026, +19% YoY; $14.8T on-chain volume, +151% YoY), alongside growth in meaningful wallets. These adoption signals reinforce standing among the largest stablecoin networks.
Scratch Financial is a veterinary fintech company on a mission to make pet care more accessible and help veterinary practices grow. More than 19,000 veterinary practices across the U.S. and Canada use Scratch to offer flexible payment options and simplify how they get paid. Our products are built to make veterinary care easier for everyone. Scratch Pay™ gives pet owners simple,...

Scratch Financial's Top Stability & Growth Strengths
Strong Revenue Growth: Inclusion on the 2024–2026 Inc. 5000, including a reported 461% three‑year growth rate, signals rapid multi‑year revenue momentum. Repeated rankings across years reinforce sustained growth despite limited public financial disclosures.
Market Expansion: The provider network increased from 16,000+ in February 2025 to 17,000+ by September 2025 and to 18,000+ in 2026, alongside availability across all 50 U.S. states and most of Canada. This indicates continued distribution gains and broader geographic reach.
Investor Backing & Capital Strength: A $35 million Series C in 2022 brought total funding above $108 million, and a May 2026 purchase facility with Victory Park Capital expanded financing capacity. These moves suggest strong access to capital to scale originations and operations.
Justworks is a cloud-based software platform that takes the busyness out of growing a business and alleviates the unknown. We've combined a simple platform and exceptional 24/7 customer service to help entrepreneurs and businesses grow with confidence by giving them access to corporate-level benefits, automated payroll, HR tools, and compliance support— all in one place.
Justworks's Top Stability & Growth Strengths
Strong Revenue Growth: Company statements describe being on track for higher net revenue, and earlier filings documented substantial year-over-year expansion. Additional references point to rising contribution metrics over recent years.
Customer Loyalty & Retention: Company updates highlight record-high satisfaction and retention alongside a recent step-up in new-customer signups. These signals point to a stable, expanding customer base.
Product Line Growth: The business continues broadening its offering beyond core PEO into payroll, benefits, HR tools, and international employment, described under a “One Justworks” strategy. New capabilities and partnerships indicate ongoing investment in breadth.

CPG is a multi-trillion-dollar industry, but the path from factory to store shelf still runs on spreadsheets, emailed PDFs, and legacy systems held together with duct tape. Brands lose real time and money every day reconciling data, fighting retailer disputes, and coordinating across finance, sales, and supply chain. We're replacing that manual work with AI agents on a single intelligent platform...

Confido's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Recent financings include a $55M Series B led by Insight Partners and a prior $15M Series A, bringing total reported funding to roughly $77M. These capital events coincide with visible signals like active hiring and continued platform build-out.
Strong Revenue Growth: Growth is repeatedly described as 5x year-over-year since the Series A, alongside a 5x increase in valuation. Customer adoption reportedly expanded to 250+ CPG brands with $30B+ in retail sales planning flowing through the platform.
Product Line Growth: The offering has broadened from cash application and deductions into trade promotion management, sales forecasting, demand/supply planning, and analytics. Additions such as AI contract reading, auto‑disputes, and the Muffin Data acquisition indicate ongoing capability expansion.
Spade is the only transaction data enrichment solution backed by real data. We leverage our vast first-party data network to bring instant clarity and context to every purchase and payment—with precisely matched merchant, category, and geolocation details that empower you to build the next generation of financial technology.
Spade's Top Stability & Growth Strengths
Strong Revenue Growth: Reported 470% year-over-year revenue growth in the year preceding the March 2026 Series B, alongside peak daily processing of up to 1.9 billion transactions, points to accelerated commercial momentum. Company materials also note billion-plus monthly transactions and expanding enterprise usage.
Investor Backing & Capital Strength: A $40M Series B in March 2026 led by Oak HC/FT with participation from a16z, Flourish, Gradient, NAventures and YC, following earlier seed and Series A rounds, provides substantial capital for scale. Stated use of proceeds includes expanding the team, deepening merchant coverage, and building the platform’s intelligence layer.
Product Line Growth: The offering is described as evolving from a transaction-enrichment API into a broader data and AI platform supporting rewards attribution, fraud, behavioral segmentation, and other workflows. Coverage has broadened across payment rails (e.g., cards, ACH, wires/RTP), increasing addressable use cases.
.jpg)
Founded in 2002, Leader Bank is a Massachusetts-based entrepreneurial financial institution that approaches banking differently. The core tenets of Leader Bank include client services, exemplary products, and innovation to meet the needs of its clients. Leader Bank’s best-in-class staff has been at the forefront of supporting the bank’s rapid growth and client-oriented solutions, as the bank has continued to expand...

Leader Bank's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Assets and loans have increased over multiple years, with total assets moving from $4.434B in 2023 to $5.032B in 2025 and further increases reported into 2026. This trajectory is supported by expanding residential lending volumes and a broadened footprint.
Profitability: Net income rose from $17.0M in 2023 to $23.7M in 2024, indicating stronger earnings performance. This improvement accompanied portfolio growth and higher lending production in 2024.
Market Expansion: Physical presence is growing with three new Massachusetts branches announced for 2026 (Boston Seaport, Andover, Falmouth). Reach is further extended by additions like a nationwide SBA lending group and a West Coast deposit team.
We recently updated our Vision and Values as we are more than simply a technology. In our evolved Vision statement, we now emphasize the word, "integrity" as we know it is the combination of technology and PEOPLE that truly sets us apart. Our clients look good because their citizens are better served using our platform and processes that include real...

ClassWallet's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has surged, with ClassWallet reporting more than doubled revenue in FY2022 and multi‑year growth rates of 916%, 1,217%, and 610% across successive Inc. 5000 periods. Business booked reached more than $1.1B in 2022 as transaction volume rose 158%.
Market Expansion: Operations have broadened from 27 to 37 states, while cumulative funds distributed climbed to about $6.5B alongside growth in clients, programs, and users. New statewide contracts in 2025, including Ohio’s selection and Indiana’s expansion, reinforce ongoing geographic growth.
Investor Backing & Capital Strength: The company closed a $95M institutional growth-capital round in 2023, with trackers citing roughly $102.6M in total funding. The financing was explicitly positioned to support continued expansion.
Upside is a technology company that increases the financial power of people and businesses in the real world. Our technology has helped millions of people get more purchasing power on the things they need, and tens of thousands of brick-and-mortar businesses earn measurable profit. Billions of dollars in commerce run through the Upside platform every year, and that value goes...
Upside's Top Stability & Growth Strengths
Market Expansion: Feedback suggests Upside expanded its marketplace with 14,669 new retailer locations and 1.6M new customers in 2025, alongside 128M transactions and a 64% YoY jump in restaurant transactions in July 2025. Feedback suggests category breadth deepened as well, with Taco Bell locations up 400% year over year and the network reaching 100,000+ retailers and ~35M consumers.
Strong Market Position & Advantage: Feedback suggests scale signals are substantial, including 35M consumers, 100,000+ retailers, >$1B cumulative cash back, and a rise in retailer incremental profit from $605M in 2024 to $707M in 2025. Feedback suggests repeated inclusion on growth rankings (e.g., Inc. 5000, Deloitte Technology Fast 500) further reflects momentum and visibility.
Strategic Partnerships: Feedback suggests partnerships and integrations broaden distribution and merchant adoption, including Marqeta and rollouts with large operators such as Save Mart and major QSR franchise groups. Feedback suggests these alliances extend Upside’s reach beyond the standalone app via partner networks that help drive consumer exposure and category expansion.
.png)
Charted clears the path for finance teams with AP Automation solutions built directly into your NetSuite environment—no integrations, no extra systems. Gain real-time clarity on every invoice, approval, and payment so you can focus on what really matters. Eliminate manual data entry with AI-powered capabilities and expense accrual automation to accelerate your month-end close. Combine the power of your full...
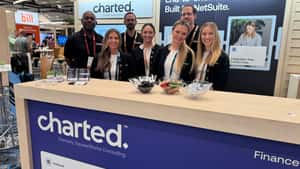
Charted, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue growth is underscored by consecutive placements on Deloitte Technology Fast 500 and the Inc. 5000, indicating multi-year expansion measured through 2025. Recognition spans overlapping earlier periods and a more recent measurement window, signaling sustained momentum rather than a one-off spike.
Market Expansion: Geographic reach widened with the opening of a UK office to support customers in the UK and EMEA following the international-payments launch and 2025 rebrand. This move complements a global customer base reported in prior updates.
Product Line Growth: The platform broadened with launches such as International Payments and Touchless Invoice Processing, with further plans cited for e-invoicing, analytics, and faster payment processing. Rising invoice-processing volumes over 2023–2025 further reflect growing adoption.
Airwallex is the only unified payments and financial platform for global businesses. Powered by our unique combination of proprietary infrastructure and software, we empower over 250,000+ businesses worldwide – including Brex, Navan, Qantas, SHEIN, McLaren and many more – with fully integrated solutions to manage everything from business accounts, payments, spend management and treasury, to embedded finance at a global...
Airwallex's Top Stability & Growth Strengths
Strong Revenue Growth: Annualized revenue increased from $720M in March 2025 to $1.3B by March 2026, with ARR surpassing $1B in late 2025 and continuing upward. This trajectory points to sustained top-line momentum across the period cited.
Market Expansion: Geographic reach broadened with new regulated entries across multiple regions, alongside plans to deploy over $1B in the U.S. and substantial investment in Europe. Regional performance in the Americas and EMEA also advanced meaningfully, indicating traction beyond APAC.
Investor Backing & Capital Strength: Valuation rose from $6.2B (May 2025) to $11B (June 2026) through successive large funding rounds. Independent reporting corroborated the latest financing, signaling strong capital access and external confidence.
Waystar harnesses the power of agentic AI, generative AI, and advanced automation to drive meaningful outcomes so providers reach peak financial performance and patients receive care with confidence. The Waystar platform is used by more than 1 million providers and supports over 60% of the U.S. patient population - and integrates with all major HIS and practice management systems. The financial and...
Waystar's Top Stability & Growth Strengths
Strong Revenue Growth: Reported revenue has been rising at a double‑digit pace across fiscal 2025 and the first half of 2026, with both Q1 and Q2 showing solid year‑over‑year increases. Management also raised full‑year 2026 revenue guidance, indicating confidence in continued expansion.
Profitability: Profitability is strong, with adjusted EBITDA growing year over year and margins holding in the low‑40s through fiscal 2025 and recent quarters. The company also reported positive net income and healthy cash generation.
Customer Loyalty & Retention: Net revenue retention remained expansionary and the number of larger clients increased year over year. Subscription revenue grew faster than total revenue in recent periods, suggesting deeper adoption within the existing base.
.png)
Navan (Nasdaq: NAVN) is the leading all-in-one business travel, payments, and expense management platform that makes travel easy for frequent travelers. From finding flights and hotels to automating expense reconciliation, with 24/7 support along the way, Navan delivers an intuitive experience travelers love and finance teams rely on. See how Navan customers benefit and learn more at navan.com.
Navan's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is scaling at strong double-digit rates, reaching $702M in FY2026 and continuing to rise in subsequent quarters, with full‑year FY2027 guidance lifted into the low‑$900M range. Multiple updates indicate momentum in both reported results and outlook.
Healthy Cash Flow: Operating cash flow turned positive in FY2026 and free cash flow was also positive, alongside progress in non‑GAAP profitability in later quarters. These milestones suggest improving financial efficiency as scale increases.
Diversified Customer Base: The company reports 12,500+ active customers and continued wins with large enterprises across technology, manufacturing, and healthcare. This breadth points to demand resilience across multiple industries.

At Revel, we are revolutionizing the way the world’s most critical hardware is controlled—across aerospace, automotive, energy, and manufacturing sectors. Our next-generation software stack combines an intuitive command/control interface, a specialized programming language tailored for hardware control, and a high-performance runtime environment. We empower engineers to build, test, and deploy critical systems rapidly, reliably, and safely.

Revel's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor appetite appears strong, with a $150M Series B in February 2026 reportedly valuing the company around $1B and providing substantial runway to scale. The rapid step-up from earlier funding suggests ample capital to expand product and go-to-market.
Market Expansion: Expansion beyond an initial aerospace testing niche into defense, robotics, nuclear, oil & gas, water, power, data centers, and biomedical manufacturing is underway. This broadening footprint indicates movement toward a larger addressable market across multiple industries.
Customer Loyalty & Retention: Conversion of pilots into paying customers and deepening within accounts—such as 80+ RevelTest instances at Impulse Space and a defense contractor scaling from 0 to 25 deployments in two months—signal strong adoption and stickiness. Named customers across advanced hardware companies reinforce ongoing usage.
Founded in 2013 in Hawaii and acquired by Booking Holdings in 2018, FareHarbor creates powerful tools that enable our clients (think boat rentals, museums, food tours, events and more!) to operate and grow. With over 20,000 clients across 90+ countries—we’re the largest in our industry and shaping the future of travel, together. Our team is an ‘Ohana of 900+...
FareHarbor's Top Stability & Growth Strengths
Market Expansion: Geographic reach and activity levels are growing, with 1,200+ operators joining from Australia and New Zealand and bookings in several major markets up 14% year over year. The operator base has risen from about 20,000 in 2024/25 to 23,000+ today, extending a long-run climb from roughly 5,000 at the 2018 acquisition.
Strategic Partnerships: Distribution reach has widened via the FareHarbor Distribution Network and deep integrations, including a global Booking.com tie-in that brings large volumes of attractions and OTA access. These connections drove a 27% year-over-year increase in total transaction volume in 2025 through partner and affiliate channels.
Product Line Growth: Product cadence remains high, with 184 platform updates in 2025 and further tools rolled out into 2026. This includes growth-focused offerings such as FareHarbor Sites and expanded distribution capabilities.



