

Top Robotics Companies (1,034)

At General Motors, our vision is to create a world with Zero Crashes, Zero Emissions, and Zero Congestion. We wholeheartedly embrace the responsibility to lead the change that will make our world better, safer, and more equitable for all. Our industry and company are undergoing a once-in-a-lifetime technological transformation, which is reshaping our approach to technology and innovation. We are expanding...
General Motors's Top Stability & Growth Strengths
Profitability: Profitability is trending upward in 2026, with management twice raising full-year adjusted EBIT guidance and North America’s EBIT margin improving to 8.6%. Strong demand, improved margins, lower EV losses, and higher operating efficiency are cited as drivers.
Strong Market Position & Advantage: Market position in the U.S. remains strong, with 2025 deliveries up 6% to about 2.9 million and market share rising to roughly 17.2%, alongside leadership in full-size pickups and full-size SUVs. Several brands posted record or decade-best results, and crossovers grew to more than 46% of sales by Q1 2026.
Healthy Cash Flow: Cash generation is viewed as robust, with executives indicating more than $10 billion of free cash flow per year on average over the last five years. Capital returns were reinforced by a higher dividend and a new $6 billion share repurchase authorization.
We are a mobility company that innovates like a start-up and thinks like a technology company. This helps us anticipate change in one of the most complex industries in the world and respond quickly. We depend on a team of 171,000 dynamic, entrepreneurial-minded employees in an environment where great ideas flourish. Our presence spans 343 manufacturing operations and 88 product...

Magna International's Top Stability & Growth Strengths
Profitability: Adjusted EBIT, margin, and EPS rose in 2025 despite lower sales, and improved further in Q2 2026 with EBIT up 16% and margin expanding to 6.2%.
Healthy Cash Flow: Cash generation strengthened, with H1 2026 free cash flow of $989M and full‑year guidance increased toward roughly $1.6–$1.8B.
Innovation-Driven Growth: New wins in high‑voltage hybrid/EV programs, ADAS, next‑gen seating, and 800V eDrive and driver/occupant monitoring awards indicate a growing pipeline for future revenue and content per vehicle.
Carbon Robotics is the leader in physical AI for agriculture, helping farmers become more profitable and sustainable. Its flagship product, the LaserWeeder™, is the world’s leading commercial laser weeding system with hundreds of units operated by farmers in 15 countries worldwide. LaserWeeder combines computer vision, AI, robotics, and high-powered lasers to identify weeds and destroy them with sub-millimeter precision—no herbicides, hand...

Carbon Robotics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have doubled over the 12 months prior to October 2024 and later surpassed $100M annually for the fiscal year ending January 31, 2026. Subsequent commentary describes continued scaling beyond this milestone, indicating ongoing momentum.
Market Expansion: Operations are described as spanning roughly 15–20 countries with particularly strong traction in the U.S., Western Europe, and Australia, alongside manufacturing and service footprints in the U.S. and Europe. Customer adoption is cited as 200+ growers across 15 countries, signaling broadening geographic reach.
Product Line Growth: The company moved beyond LaserWeeder into Carbon Autonomy/AutoTractor and launched the LaserWeeder G2 line. Another agricultural robot in development and autonomy programs further indicate portfolio expansion.
Securing The Freedom of Operations Headquartered in Colorado, Sierra Space is a mission-proven Defense Tech company delivering satellite platforms, critical subsystems, reusable spaceplanes, hypersonic technologies, propulsion systems, and infrastructure for the nation’s most critical missions. With more than three decades of heritage and a record of flight-proven success in space, Sierra Space is trusted by U.S. National Security, Civil customers, and global...
Sierra Space's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised has grown markedly, including a $550 million Series C in March 2026 that lifted total investments since 2021 above $2 billion and valued the company at $8 billion. This financing momentum aligns with sizable government awards and ongoing scale-up efforts.
Market Expansion: The creation of a dedicated defense unit, new manufacturing capacity (e.g., the 60,000-square-foot Victory Works) and a footprint exceeding 1 million square feet indicate expansion from development into larger-scale defense manufacturing. Significant awards since 2023—such as $1.5 billion in defense contracts and Space Development Agency awards of $740 million (2024) and $798 million (2026)—reinforce this broader market reach.
Diversified Customer Base: Activity spans national-security customers, NASA (e.g., a lunar logistics study and payloads for the Dream Chaser inaugural flight), the U.S. Air Force (engine development), and Mitsubishi Heavy Industries (ISS docking components). This mix points to multiple civil, defense, commercial, and international demand sources.
Fairly Even is a a dual-purpose marketing and technology platform focused on empowering entrepreneurs to build passive income streams through business automation tools. We operate primarily in the fintech and hospitality sectors, providing solutions for point-of-sale (POS) systems and automated kitchen technology.
Fairly Even's Top Stability & Growth Strengths
Strong Hiring & Retention: Hiring is expanding, with field-sales roles across 42 locations and a salaried New York position posted in early 2026. Company profiles also indicate roughly 30 employees and active recruiting, signaling a build-out of sales and product capacity.
Market Expansion: Geographic reach is widening through a multi-location field-sales organization covering dozens of U.S. markets. Independent company overviews further highlight this nationwide sales push as a core element of the expansion strategy.
Product Line Growth: The offering has broadened from POS into a fuller restaurant-technology platform, including mobile ordering/payments, kitchen displays, loyalty/marketing tools, and integrated payments. Added emphasis on automated cooking products and expansion into scheduling and inventory tools suggests an actively growing portfolio.
SharkNinja is a global product design and technology company, with a diversified portfolio of 5-star rated lifestyle solutions that positively impact people’s lives in homes around the world. Powered by two trusted, global brands, Shark and Ninja, the company has a proven track record of bringing disruptive innovation to market and developing one consumer product after another has allowed SharkNinja...
SharkNinja's Top Stability & Growth Strengths
Strong Revenue Growth: Net sales rose to roughly $6.40B in FY2025 and then accelerated year over year in early 2026, with management citing a long streak of double-digit quarterly growth. Full-year 2026 revenue guidance was increased after a strong second quarter, indicating confidence in continued expansion.
Profitability: Profitability expanded alongside sales, with operating income, net income, and adjusted EBITDA all rising in FY2025 and continuing to grow on adjusted metrics in 2026. Management characterized recent periods as among the company’s strongest on several profit measures.
Market Expansion: International sales outpaced domestic growth in FY2025 and accelerated further in 2026, reflecting traction in the U.K., Europe, and Latin America. This geographic scaling contributed meaningfully to the company’s overall growth profile.
LTS serves three markets today. In media & entertainment, studios, VFX houses, and video platforms use LTX for animation, keyframing, and generating video at scale from existing assets. In real-time experiences, LTX powers talking avatars and efficient on-device rendering for interactive engines like Unity. In robotics and physical AI, we work with partners like Standard Bots and Markov Robotics to...
LTX's Top Stability & Growth Strengths
Product Line Growth: LTX has expanded from an AI filmmaking app into a broader AI video/model platform, adding open‑weights models (the LTX‑2 family), an API, Desktop, Studio, and a Trainer. Reported adoption indicators such as 135,000 Studio users and millions of model downloads point to a widening product footprint.
Innovation-Driven Growth: A rapid release cadence delivered capabilities like native 4K/50fps video, synchronized audio, multishot generation, and longer clips across LTX‑2, 2.3, and 2.5. The move to open weights and strong developer traction on Hugging Face reinforce sustained R&D momentum.
Investor Backing & Capital Strength: The business was separated from Facetune to “hypercharge” growth and reportedly received substantial internal investment from Lightricks, signaling committed capital support. Organizational focus on LTX as the generative‑AI growth initiative underpins capacity to invest through cycles.
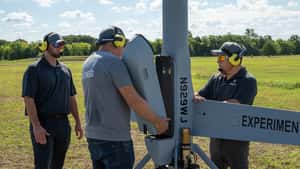
At Shield AI, you won't wait years to see your work reach the field. You'll build hardware and software that operates in the real world right now, in the hands of the people who depend on it. Hivemind, our AI pilot, has been flying since 2018. It has flown more than 30 platforms, including an F-16, and it now sits under...
Shield AI's Top Stability & Growth Strengths
Strong Revenue Growth: Company reports indicate FY2026 orders and revenue doubled year over year. Management projections point to revenue well above $500 million for 2026, signaling rapid topline acceleration.
Investor Backing & Capital Strength: Recent financings include a $1.5 billion Series G and $500 million in preferred equity at a $12.7 billion valuation. These steps indicate substantial capital access and confidence from major financial backers.
Market Expansion: Program momentum includes a U.S. Air Force production award for CCA autonomy and a U.S. Navy ISR vehicle with a high task‑order ceiling. International traction spans India, Greece, Poland, and Taiwan, alongside plans for regional offices.
Allen Control Systems is a defense technology company for a new era of drone warfare and to completely change battlefield economics. ACS is developing counter-drone robotic gun systems targeted at neutralizing attacking drone swarms, drones that are pre-programmed with AI, and drones that are non-jammable. ACS was created to lower the cost per kill of a drone to a few...

Allen Control Systems's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $200 million Series B at a $2.2 billion valuation, following earlier rounds, provides substantial resources to scale. Company announcements link this capital directly to manufacturing expansion and accelerated deployment of Bullfrog.
Market Expansion: Operations expanded with a 191,000-square-foot manufacturing facility in Austin and a new engineering office in Silicon Valley, alongside earlier growth of the Austin headquarters. Awards with the U.S. Army and Marine Corps and reported activity with allied militaries indicate broader market reach.
Strong Hiring & Retention: Headcount has risen into the hundreds, and active requisitions span engineering, manufacturing, and operations. Hiring events and multi-disciplinary job postings signal continued workforce scaling to meet production needs.


At Revel, we are revolutionizing the way the world’s most critical hardware is controlled—across aerospace, automotive, energy, and manufacturing sectors. Our next-generation software stack combines an intuitive command/control interface, a specialized programming language tailored for hardware control, and a high-performance runtime environment. We empower engineers to build, test, and deploy critical systems rapidly, reliably, and safely.

Revel's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor appetite appears strong, with a $150M Series B in February 2026 reportedly valuing the company around $1B and providing substantial runway to scale. The rapid step-up from earlier funding suggests ample capital to expand product and go-to-market.
Market Expansion: Expansion beyond an initial aerospace testing niche into defense, robotics, nuclear, oil & gas, water, power, data centers, and biomedical manufacturing is underway. This broadening footprint indicates movement toward a larger addressable market across multiple industries.
Customer Loyalty & Retention: Conversion of pilots into paying customers and deepening within accounts—such as 80+ RevelTest instances at Impulse Space and a defense contractor scaling from 0 to 25 deployments in two months—signal strong adoption and stickiness. Named customers across advanced hardware companies reinforce ongoing usage.

Headquartered in sunny Los Angeles, GrayMatter Robotics is an AI robotics company that builds the factories of the future today, empowering people, creating safer workplaces, and shaping a more prosperous society. We build next-generation factories that transcend human constraints, driving exponential productivity and sustainable economic growth. Our technology brings together robotics, Physical AI, and human ingenuity to create intelligent systems...

GrayMatter Robotics's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised has scaled meaningfully, including a $45M Series B in June 2024 that brought total disclosed funding to roughly $70M–75M+. Company materials link this capital to expansion in hiring, facilities, and product deployment.
Market Expansion: Deployments and geographic footprint have broadened, with robots reported across 30+ locations in 16+ states and operations in four countries. Customer base reportedly quadrupled and existing accounts such as Pierce Manufacturing expanded usage.
Strategic Partnerships: High‑profile industrial and defense relationships are advancing, including an HII memorandum of understanding and multiple AFWERX/Navy SBIR activities. Collaborations with established players (e.g., 3M, FANUC) and selection in Navy innovation programs signal growing market access.
.png)
Doodle Labs designs and produces industrial-grade wireless networking solutions. The company focuses on mesh networking for robotic systems, providing high throughput, long-range Mesh Rider solutions for UAVs, UGVs, AMRs and other robotic applications. The company’s Helix Mesh Rider Radio was developed with sponsorship from DIU and is the Blue UAS program’s datalink of choice. Doodle Labs was named one of Fast...

Doodle Labs's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships are described as expanding across OEMs, integrators, and channels, including integrations with Auterion, Teledyne FLIR, Teal/Red Cat, and new agreements such as LUXUAV and distribution via Mouser. These relationships are portrayed as increasing platform embed opportunities and international reach.
Product Line Growth: The portfolio is reported to have expanded from Mesh Rider into Nano², Mini, OEM, Boost, and Wearable radios, along with Sense-EW capabilities and a mobile app. This widening set of form factors and features suggests a broader addressable market and use cases.
Market Expansion: Activity is noted across U.S. defense programs (e.g., an Army Phase II SBIR award) and into Europe through NATO-aligned pushes and the LUXUAV partnership. Company materials also highlight integrations across drones and robotics globally, indicating growing geographic and sector presence.
Apptronik is building robots for the real world to improve human quality of life and to help solve the ever-increasing labor shortage problem. Our team has been building some of the most advanced robots on the planet for years, dating back to the DARPA Robotics Challenge. We apply our expertise across the full robotics stack to some of the most...

Apptronik's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor participation is substantial, with nearly $1B raised across Series A tranches and backing from corporates like Google and Mercedes‑Benz to fund production and deployment. Feedback suggests this capital base is intended to accelerate scaling of Apollo and broader operations.
Strategic Partnerships: Partnerships span Mercedes‑Benz, GXO Logistics, Jabil, and Google DeepMind, moving Apollo from demos into pilots and industrial integrations. These relationships indicate advancing commercialization and access to manufacturing and AI capabilities.
Strong Hiring & Retention: Headcount expanded into the hundreds with senior hires from Waymo, Boston Dynamics, and Amazon to drive commercialization. Public statements note continued hiring to support production, facilities build‑out, and deployments.
Boston-based company Piaggio Fast Forward Inc. (PFF) was founded in 2015 by the Piaggio Group (the Italian manufacturer that created the iconic Vespa scooter). In order to bring products to market today, PFF is solving the problem of robotic interaction with people in dynamically changing environments. We’re innovators, neighbors and creators with a passion for local living and pushing the...
Piaggio Fast Forward's Top Stability & Growth Strengths
Product Line Growth: Product offerings have expanded from consumer robots (gita, gitamini) to the B2B kilo platform, with additional features like Forward Following, Trips, and hybrid navigation introduced in 2025–2026. This points to an actively developing portfolio rather than a static lineup.
Market Expansion: The move from consumer-focused products into manufacturing, warehousing, and facilities management signals a broader addressable market. Parent-company materials in 2026 still describe active marketing and Boston-based manufacturing across multiple robot platforms.
Innovation-Driven Growth: Continued releases such as a production-ready hybrid-navigation AI model and other capability updates indicate ongoing R&D and technology maturation. Brand collaborations like the Grogu/Star Wars gitamini also reflect sustained commercialization activity.
Relativity Space is on a mission to better connect humanity to space and the universe beyond our planet. Our medium-to-heavy lift reusable rocket, Terran R, will deliver customer payloads to orbit, meeting the growing demand for launch capacity. But that’s just the start. Achieving commercial success with Terran R will unlock new opportunities to advance science, exploration, and innovation, pioneering progress that...
Relativity Space's Top Stability & Growth Strengths
Market Expansion: Access to NASA’s NLS II and the U.S. Space Force’s NSSL Phase 3 Lane 1 broadens eligibility for future government missions, while multi‑launch agreements and a multibillion‑dollar backlog point to widening commercial demand. Facility growth on Florida’s Space Coast further extends operational reach.
Product Line Growth: Scope has expanded beyond launch services with an Interplanetary Sciences Program and a planned Mars science orbiter in 2028. Terran R has advanced from design into flight‑hardware production, engine acceptance testing, structural qualification, and launch‑site build‑out.
Strong Hiring & Retention: Headcount has risen materially to a reported ~2,000 employees across multiple U.S. locations. Concurrent expansion of Long Beach manufacturing and Cape Canaveral infrastructure indicates sustained organizational scaling.

AMP is applying AI-powered sortation at scale to modernize the world's recycling infrastructure and maximize the value in waste. AMP gives waste and recycling leaders the power to harness AI to reduce labor costs, increase resource recovery, and deliver more reliable operations. With hundreds of deployments across North America, Asia, and Europe, AMP’s technology offers a transformational solution to waste...

AMP's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raises are substantial, including a $91M Series C expanded above $99M and a $91M Series D in 2024, with participation from prominent institutional investors. Funding momentum is positioned to support scaling of AMP ONE facilities and further international deployment.
Market Expansion: Deployment has broadened from ~275 robots in 2022 to hundreds of systems across the U.S., Canada, Japan, and Europe by 2024, with ~400 robots and three operating facilities reported by late 2024. Recent announcements also highlight additional facilities, acquisitions/partnerships, and new municipal-waste projects through 2025–26.
Product Line Growth: The business has evolved from selling individual robots to designing, building, and operating full-scale automated sorting facilities, including the AMP ONE platform. Expansion into operated infrastructure and new project types signals a wider solution set beyond components.
Rangeview is building a modern casting platform to manufacture critical metal parts for aerospace, defense, and energy. We combine advanced software, automation, and materials science to reinvent how parts are designed and produced. Based in El Segundo, California, our team brings engineering, manufacturing, and technology together to build the foundry system that reindustrializes America.
Rangeview's Top Stability & Growth Strengths
Strategic Partnerships: Recent selections by Kratos for advanced turbine-engine components and a U.S. Navy MRO production contract indicate traction with major defense customers. These relationships mark a progression from technology development into funded, production-scale programs.
Investor Backing & Capital Strength: A U.S. government SBIR Phase II award alongside mentions of venture backing provide meaningful capital support for scaling operations. Feedback suggests this blend of non‑dilutive funding and venture capital is enabling equipment investment and production timelines.
Market Expansion: Becoming awardable via the DoD CDAO Tradewinds Solutions Marketplace and adding a new facility signal expanding access to government channels and increased capacity. Company statements of high order demand further point to growing market reach.
Treeswift builds physical AI for labor. We use robotics and machine learning to help the people who do real work get more done, starting with the crews who keep the electric grid running,.
Treeswift's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Funding progression includes a reported Series A in 2023 and total capital in the mid‑teens of millions, indicating resources to scale operations and product. Named institutional investors and multiple rounds point to continued capacity to support growth initiatives.
Market Expansion: Positioning has broadened from forestry robotics into AI‑powered field operations for utilities, including vegetation management, asset inspection, construction, and disaster response. This shift suggests access to larger, higher‑value commercial segments.
Product Line Growth: Activity logs cite next‑generation backpack and vehicle hardware shipments, faster data processing, expanded species identification, and a desktop review application. These updates indicate ongoing investment in capabilities aligned to real‑world utility workflows.

Unusual Machines, Inc. is an American company that manufactures and sells drone components, specializing in First-Person View (FPV) technology. They also operate a drone-focused e-commerce marketplace and are involved in counter-UAS systems.
Unusual Machines, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue more than doubled in 2025 and accelerated through 1H 2026, with Q2 2026 reaching about $16.7M and first-half revenue of $24.8M. The mix pivoted toward enterprise component sales, which became the primary driver by 2025 and dominated in early 2026.
Investor Backing & Capital Strength: The company raised substantial equity, including a $60M at-the-market offering completed May 29, 2026, and reported roughly $229.6M in cash and $86.8M in investments as of June 30, 2026. This capital base is being deployed into facilities, equipment, inventory, and headcount to support scaling.
Future-Ready Strategy: Emphasis on NDAA-compliant, U.S.-made components and Blue UAS/Framework alignment positions the firm to benefit from policy-driven shifts away from Chinese supply chains. Orlando-based manufacturing build-out and the Fat Shark/Rotor Riot acquisitions underpin access to FPV and defense-adjacent demand.

Observable Space is unlocking continuous, real-time observations of space with the industry’s first line of vertically integrated hardware and software products. The company is the result of a merger between PlaneWave Instruments, the leader in advanced telescope design and manufacturing in the US, and OurSky, a company founded by SpaceX’s former VP of software engineering to create a developer platform...



Work Your Passion. Live Your Purpose.

