

Top Machine Learning Companies in Washington, DC (68)
.png)
GRAIL is a healthcare company whose mission is to detect cancer early, when it can be cured. GRAIL is using the power of high-intensity sequencing, population-scale clinical studies, and state-of-the-art computer science and data science to enhance the scientific understanding of cancer biology, and to develop and commercialize pioneering products.
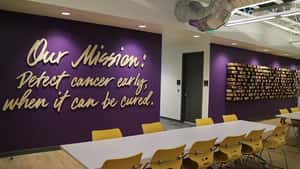
GRAIL's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising across 2025 and into 2026, with Galleri driving year-over-year increases and volumes outpacing revenue. Feedback suggests growth accelerated in early 2026 as test adoption broadened.
Strategic Partnerships: Partnerships such as Epic EHR integration and a collaboration with Samsung for Asia expansion are expanding distribution and market access. These relationships also support commercialization through employers, health systems and digital-health channels.
Investor Backing & Capital Strength: A sizable cash balance and recent equity financing provide a substantial runway to fund R&D and commercial expansion. This capital position helps buffer the costs of scaling while regulatory review proceeds.
STR makes the world a safer place by developing technology and applying it to solve emerging national security challenges.
STR's Top Stability & Growth Strengths
Market Expansion: Facilities, workforce, and a seven-location U.S. footprint have scaled markedly since 2010 as operations extended from airborne processing into cyber, undersea, space, land, and maritime systems. Current hiring across engineering and program roles reinforces an expanding presence in multiple hubs.
Innovation-Driven Growth: Capability breadth now spans six areas—AI/analytics, autonomy, hardware systems, cyber effects, sensing and spectrum, and adaptive mission engineering—with technology reuse across programs. Documented SBIR activity and awards from DARPA and the military services indicate momentum anchored in advanced R&D.
Diversified Customer Base: Federal contracting activity spans DARPA and the Air Force, Navy, and Army, demonstrating access to multiple defense customers. This multi-agency footprint reduces dependence on any single sponsor within the government sector.
Vannevar combines Silicon Valley innovation with former special operators to build AI for real-world national security outcomes. Since our founding in 2019, Vannevar has deployed its technology across 125 missions, safeguarding our service members and improving our country's deterrence. We believe our military service members and intelligence officers deserve access to the best technology American innovation can offer, and we are...

Vannevar's Top Stability & Growth Strengths
Strong Revenue Growth: Company-reported figures indicate scale to roughly $80 million in 2024 annual contract value and recognition on the Inc. 5000 list for rapid multi-year expansion. Government contract obligations under a production vehicle and continued awards further reflect meaningful commercial momentum, even as contract ceilings are not revenue.
Profitability: The business is described as having achieved three consecutive profitable years while expanding contract value. This points to growth supported by operating discipline rather than reliance solely on external financing.
Market Expansion: A transition from a DIU prototype to a production-scale agreement and reported deployment across all U.S. military branches and combatant commands indicate widening reach within the defense market. Partnerships and authorizations announced in 2026 are positioned to extend access across combatant commands and federal agencies.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Quarterly revenue increased materially year over year in Q2 2026, and full-year 2025 sales also rose. The acceleration into 2026 alongside expanding user metrics signals momentum in top-line performance.
Healthy Cash Flow: Free cash flow turned positive and expanded meaningfully versus the prior year, alongside a large step-up in adjusted EBITDA. This points to improving cash generation and operating efficiency.
Diversified Revenue Streams: Subscriptions and other direct revenue grew much faster than advertising, with products like Snapchat+, Lens+, and Memories contributing significantly. This diversification reduces sole dependence on the ad cycle and broadens monetization levers.
ASI is a dual-use software company that deploys predictive AI to the world's most complex operating environments. Backed by leading investors–including Andreessen Horowitz, Renegade Partners, and Spark Capital–we actively manage over 40% of all US air traffic across both public and private sector air operations. Partnering with major airlines like United and Alaska, we optimize thousands of flights daily, delivering...
Air Space Intelligence's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $325 million Series C at a reported $3 billion valuation, led by Spark Capital with participation from firms such as Andreessen Horowitz, signals strong capital access and confidence in future scale. The company describes using this capital to expand aviation, defense, energy, logistics, research, and engineering operations.
Market Expansion: Major awards like the FAA’s 12-year program (reported up to $875 million) and a five-year, $99 million U.S. Army contract, alongside airline customers and a National Grid collaboration, indicate expansion across government, commercial, and energy sectors. Partnerships such as Joby Aviation and new defense programs (e.g., DIU and the Open Mission Engine) further extend reach beyond the original aviation focus.
Strong Hiring & Retention: Dealroom reports 26.3% annual team growth with an estimated 173 employees and open positions, while another market source cites an increase from 163 to 228 in a quarter. Active recruiting across engineering, machine learning, cloud, mission operations, and growth roles points to organizational scaling.
Upside is a technology company that increases the financial power of people and businesses in the real world. Our technology has helped millions of people get more purchasing power on the things they need, and tens of thousands of brick-and-mortar businesses earn measurable profit. Billions of dollars in commerce run through the Upside platform every year, and that value goes...
Upside's Top Stability & Growth Strengths
Market Expansion: Retailer participation expanded from over 50,000 locations in 2022 to about 100,000 by 2025, with 14,669 new locations added in 2025 and rollouts such as The Save Mart Companies’ nearly 200 stores. Feedback suggests consumer reach remains large at around 35 million, alongside substantial transaction and return-visit activity reported for 2025.
Strategic Partnerships: Partnerships and integrations with retailers and financial/tech platforms (e.g., Save Mart, Cary Oil expansion, Marqeta, Varo Bank, and distribution through Uber/Chime/Instacart) broaden access and deepen adoption. Feedback suggests existing partners are scaling usage and piloting new offer models, such as QuickChek’s fuel-offer approach.
Product Line Growth: Expansion beyond fuel into restaurants and grocery shows momentum, with reported year-over-year restaurant transaction gains and high volumes of grocery offers claimed monthly. Feedback suggests new product moves and category breadth (including hardware) are contributing to diversified growth.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Profitability: Operating earnings and margins improved notably in 2026, with Q3 operating earnings up sharply year over year and the operating margin rising to 5.6%. Feedback suggests earnings resilience is being supported by operational changes and a shifting business mix.
Strong Revenue Growth: Reported annual revenue expanded from $226.6B in 2023 to $270.6B in 2025, including roughly 12% growth in 2024 and 7% in 2025. This establishes a robust multi‑year revenue trajectory even as recent growth rates have moderated.
Cost & Operational Efficiency: Cost controls and operational improvements are described as lifting earnings despite lower revenue in 2026. Optum Health’s operating earnings rose from $41M to $735M year over year while serving fewer value‑based patients, indicating stronger execution.
Altana powers agentic trade workflows and public-private collaboration across product value chains — the source of truth for where products come from. With Altana, businesses can prove compliance before goods ship and build more efficient, resilient, and secure supply chains. Logistics providers can automate the full brokerage workflow, and governments can promote economic security, manage borders, and enable the flow...

Altana's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Evidence highlights a $200 million Series C in July 2024 at a $1 billion valuation with participation from prominent investors, indicating substantial capacity to fund expansion. While valuation alone does not confirm revenue growth, the capital base supports continued scaling.
Market Expansion: Adoption appears to be widening across major logistics providers and governments, including an expanded CBP contract, a UK government program, FedRAMP High authorization, and reported daily use by more than 5,000 CBP agents. Partnerships such as Maersk and work with multiple governments suggest broader reach across sectors and geographies.
Product Line Growth: The July 2026 acquisition of Cervo AI extends capabilities from supply-chain intelligence into automated customs-entry workflows. Additional deployments like Product Passports and tariff tools indicate a deepening and broadening of the offering.

Space was once the quietest place in the universe. Now, it's crowded, contested, and confrontational. We are True Anomaly: the only defense company focused exclusively on space defense. Founded in 2022 by ex-U.S. Space Force members, True Anomaly designs and builds advanced systems for space superiority: agile and powerful spacecraft platforms, mission software engineered for unmatched command and control, and payloads...

True Anomaly's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $650 million Series D in April 2026 lifted total capital raised since 2022 to over $1 billion, with a reported $2.2 billion valuation. These resources are directed toward scaling manufacturing, missions, and hiring, signaling strong capacity to fund expansion.
Strong Hiring & Retention: Headcount moved from roughly 170 in April 2025 toward a stated goal of exceeding 500 by year-end 2026, with third-party estimates during 2026 supporting substantial growth. Hiring tied to facility buildout and a growing mission cadence indicates active team scaling across engineering and operations.
Market Expansion: Selections for additional U.S. Space Force programs in 2026—such as GHOST-R GEO reconnaissance, Kronos battle-management software, Andromeda, and space-based interceptors—indicate widening demand for Jackal spacecraft and Mosaic software. Manufacturing investment in Long Beach and a growing mission pipeline further point to increasing participation in national-security space.


At Shield you won't wait years to see your work reach the field. You'll build hardware and software that operates in the real world right now, in the hands of the people who depend on it. Hivemind, our AI pilot, has been flying since 2018. It has flown more than 30 platforms, including an F-16, and it now sits under a...
Shield 's Top Stability & Growth Strengths
Strong Revenue Growth: Company updates describe orders and revenue doubling year over year in FY2026, with independent estimates showing substantial growth through 2024. Additional reporting notes a projection of more than 80% revenue growth for 2026.
Investor Backing & Capital Strength: A $2 billion financing package in March 2026 at a $12.7 billion post-money valuation is cited, including a large Series G and preferred equity. The capital was linked to expansion initiatives and the planned acquisition of Aechelon Technology.
Market Expansion: New defense wins and international deployments are described, including a U.S. Air Force production contract, Coast Guard and Navy programs, and activity across Europe and the Asia-Pacific. Company communications also highlight wider adoption of Hivemind and expansion of V-BAT operations.
MORSE is a specially selected team of scientists, engineers, and software developers who use asymmetric and unconventional approaches to deploy practical solutions that solve difficult multi-disciplinary problems faced by the US National Security Ecosystem.
MORSE Corp's Top Stability & Growth Strengths
Market Expansion: The company opened offices in Arlington, VA (2024) and Seattle, WA (2025), moves described as supporting continued growth, customer access, and recruiting. This expanded footprint indicates deliberate entry into new regions tied to defense customers and talent pools.
Innovation-Driven Growth: Substantial awards spanning AI-enabled systems, autonomous aircraft, and DARPA research (including a $66.7M Army data/software contract, a $98M ceiling AI/T&E vehicle, and a $48.05M Army autonomous-aircraft agreement) point to growth anchored in advanced technologies. Selection as a prime on R&D vehicles further underscores momentum in applied AI and autonomy.
Strong Market Position & Advantage: Prime selections and sizable U.S. Army and DARPA programs, along with rising multi-year federal obligations since FY2022, suggest strengthening competitive standing in defense technology. Access to government-wide vehicles such as IAC MAC Pool 2 expands routes to future task orders.
We bring together one of the world’s largest libraries of multimodal clinical and molecular data with a robust suite of AI tools to help physicians personalize care in real time, connect patients with therapies and clinical trials, and enable partners to accelerate discovery and development of new treatments. With ~8 million de-identified research records and 350+ petabytes of data, Tempus partners...
Tempus AI's Top Stability & Growth Strengths
Strong Revenue Growth: Recent financial results highlight sustained top-line expansion with rising quarterly revenue and management increasing full‑year guidance, indicating momentum across 2025 and into 2026.
Diversified Revenue Streams: Growth is coming from both diagnostics and data licensing/AI applications, with testing volumes and data contracts expanding rather than reliance on a single line of business.
Customer Loyalty & Retention: Reported net revenue retention above 100% and sizable remaining contract value suggest existing pharmaceutical customers are deepening engagements.
Bellagent is an enterprise-level AI agent platform built to automate everyday business operations with zero-touch integrations that connect instantly to more than 1,300 applications. Launched in 2025 by Proactifi Inc., and headquartered in Chicago, the platform is built for practicality with industry-leading compliance and security standards, enabling organizations to deploy AI agents without friction from day one. Bellagent’s mission to...
Bellagent's Top Stability & Growth Strengths
Strong Hiring & Retention: Hiring across product, engineering, and AI sales, a reported team size in the 20–25 range, and a new Chicago West Loop office point to tangible team expansion. Feedback suggests the organization is investing beyond a founder-only stage and building go-to-market capacity.
Product Line Growth: A February 2026 public launch and marketed workflows across sales, support, and operations with 1,300+ integrations indicate a shift from development to commercial distribution. Materials also show the offering broadening into multiple operational use cases.
Investor Backing & Capital Strength: References to Canvas Ventures and named investor support signal external capital and ecosystem ties. Inclusion in third-party company databases and investor quotations reinforce the presence of funding even though specific amounts are undisclosed.
Getty Images believes the right image, video or illustration can move the world. We deliver standout visual content to our customers, to power their commerce and ideas, and connect to their audience. For nearly 30 years, we’ve helped creative, business and media customers to define moments and shift perceptions using powerful visuals from gettyimages.com, istockphoto.com and unsplash.com.

Getty Images's Top Stability & Growth Strengths
Strong Market Position & Advantage: Competitive assessments place the company alongside Shutterstock and Adobe as one of the principal global providers of paid stock content, and as the clear UK leader in editorial. Longstanding relationships with major news and sports outlets reinforce this position.
Innovation-Driven Growth: Generative AI tools trained on licensed content and delivered with indemnification position the offering as a risk‑mitigated choice for enterprises. Being a launch partner on NVIDIA’s evolving Edify roadmap signals continued differentiation in safe‑to‑use AI.
Diversified Revenue Streams: A multi‑brand portfolio spanning premium enterprise (Getty Images), SMB/prosumer (iStock), and free‑plus‑subscription (Unsplash) reaches buyers from large media houses to individual creators. Revenue comes from a mix of annual subscriptions and large licensing agreements, creating multiple monetization paths even as deal timing can be lumpy.

Dataminr -- long recognized as one of the world’s leading artificial intelligence (AI) startups -- puts real-time AI and public data to work for our customers, generating relevant and actionable alerts for thousands of users working in more than 100 countries for hundreds of client organizations--spanning global corporations, public sector agencies, NGOs, and newsrooms. As 2020 taught us, the unexpected can...


The space enterprise has been transformed by rapid change and growth. New vehicles for national security space, a more rapid launch cadence, proliferated satellite constellations, the pursuit of interplanetary exploration, and thriving commercial ventures are changing the nature of the space industry. The Aerospace Corporation (Aerospace) is a leading architect for U.S. space programs, shaping efforts to outpace threats to...

The Aerospace Corporation's Top Stability & Growth Strengths
Strong Market Position & Advantage: The company is described as the nation’s principal technical architect and the only space‑exclusive FFRDC, serving as a trusted advisor to the U.S. Space Force and NRO. This independent, non‑competing role positions it as a central, stabilizing technical authority across national‑security space.
Innovation-Driven Growth: Major investments such as the $100M El Segundo labs, the Space Warfighting Center, and creation of xLab, along with emphasis on AI/ML and digital engineering, expand technical capacity. A new collaboration with Google Public Sector on agentic AI further signals capability expansion into data‑driven operations.
Strong Revenue Growth: Revenue increased to about $1.4B by 2024 and held in 2025 as its Washington Technology Top 100 rank improved from No. 33 to No. 29. Headcount growth to 4,800+ employees, with a high share of technical staff, supports rising mission demand.

Armaments Research Company (ARC) is a defense technology company developing AI-enabled weapons sensors for warfighters. Its ARC AI-Enabled Weapons Sensor collects and transmits real-time tactical data to the cloud, delivering situational awareness, predictive logistics, and predictive maintenance capabilities. ARC combines Internet of Things technology and machine learning to generate actionable insights at the tactical edge, improving survivability, decision-making, readiness, and...

Cogent Security is an Applied AI Lab building AI systems for cybersecurity. They provide an AI-driven platform that automates vulnerability management by assessing risks and remediating issues before breaches occur.
Consumer behavior is changing rapidly; people are empowered, connected and expect an unprecedented level of service and convenience. Simultaneously, the financial and retail industries we operate in are converging as mobile, contactless tech, smart data and advanced analytics blur the lines. The world is “always on” – it’s a digital era that requires us to orchestrate touchpoints in ways that...
Diebold Nixdorf's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent trackers and filings place the company as a top‑tier competitor in bank‑grade ATMs and a global No. 2 in retail self‑checkout, with recognized leadership in ATM software. This breadth across hardware, software, and services in both Banking and Retail underpins competitive advantage.
Profitability: Recent results highlight growing adjusted EBITDA and positive EPS since the 2023 restructuring. Management targets further margin expansion and has reaffirmed guidance that emphasizes earnings growth.
Healthy Cash Flow: The company has delivered consecutive quarters of positive free cash flow, including a record first‑quarter performance in 2026. Guidance and multi‑year targets emphasize stronger cash generation versus prior years.
inca is a venture-backed startup and AI-native Third Party Administrator (TPA) on a mission to automate insurance claims through Agentic AI. The company develops an automated insurance claims evaluation platform designed to streamline claim assessment while maintaining regulatory quality, supporting insurers facing heavy workloads or profitability pressures in claims processing.



