

Top Aerospace Companies in Washington, DC (85)
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased 10% in 2025 and 9% in H1 2026, with leadership upgrading 2026 guidance to 8–10% sales growth. Growth was reported across all major sectors.
Profitability: Underlying EBIT rose 12% in 2025 and 11% in H1 2026, alongside an improved return on sales. This points to stronger margins in addition to top-line expansion.
Resilient & Sustainable Growth: A record order backlog of roughly £83.6–84.0 billion and multi‑year contracts provide substantial future revenue visibility. The 2026 outlook also signals continued expansion.
A leading global aerospace company and top U.S. exporter, Boeing develops, manufactures and services commercial airplanes, defense products and space systems for customers in more than 150 countries. Our U.S. and global workforce and supplier base drive innovation, economic opportunity, sustainability and community impact. Boeing is committed to fostering a culture based on our core values of safety, quality and...

Boeing's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising year over year, with H1 2026 up 11% and Q1/Q2 growing 14% and 8% respectively, supported by higher commercial-aircraft deliveries. This momentum reflects increased production throughput and broader top-line recovery.
Healthy Cash Flow: Cash generation is improving, as H1 2026 operating cash flow turned positive and free cash flow improved, including a positive result in Q2. This shift indicates better working-capital dynamics alongside rising delivery volume.
Strong Market Position & Advantage: Backlog is at a record level of roughly $715 billion, including more than 6,200 commercial aircraft. This depth of contracted demand provides multi‑year visibility for production and revenue.
Vantor is forging the new frontier of spatial intelligence to unlock a more autonomous, interoperable world. We empower decision makers and operators with the clarity they need to navigate what’s happening now and shape what’s coming next. Our AI-powered spatial intelligence platform fuses data from the world’s highest-resolution satellites with real-time sensor feeds from space, air, and ground to create...
Vantor's Top Stability & Growth Strengths
Market Expansion: International presence is expanding with a new U.K. headquarters and local leadership in multiple new markets, alongside three multi-year contracts totaling about $204.7M across the Middle East and Africa and more than a dozen new European customers in 2025. Company materials also describe broadened relationships across U.S. government, international government, and commercial customers.
Product Line Growth: The business is moving beyond satellite imagery into an end-to-end, software-driven spatial-intelligence platform with offerings such as Tensorglobe, Cortex, Forge, Nexus, and new releases like WorldView 3D. Constellation plans (Vantage and Pulse) further extend scope toward higher-resolution and high-revisit capabilities.
Strategic Partnerships: Partnerships with BAE Systems, EnduroSat, and CACI underpin next-generation satellites, while collaborations with Esri, Google, Rheinmetall, and Anduril expand distribution and solution integration. These alliances indicate deeper ecosystem reach across defense and commercial geospatial workflows.
MORSE is a specially selected team of scientists, engineers, and software developers who use asymmetric and unconventional approaches to deploy practical solutions that solve difficult multi-disciplinary problems faced by the US National Security Ecosystem.
MORSE Corp's Top Stability & Growth Strengths
Market Expansion: The company added Arlington, VA (2024) and Seattle, WA (2025) to its Cambridge base, explicitly linking the Seattle opening to “steady growth” and proximity to customers and talent. This footprint expansion indicates broader geographic reach and increased customer access.
Innovation-Driven Growth: Large awards tied to advanced technologies—such as a ~$97.5M Army STEAM IDIQ for AI-enabled systems, a $48M Army UAS OTA, and a DARPA Albatross prime—show momentum in AI/ML, autonomy, and high-end R&D. These programs suggest growing demand for its applied engineering and experimentation capabilities.
Strong Hiring & Retention: Headcount signals moved from 150+ employees in 2022 to roughly 200+ more recently, alongside active multi-site recruiting. Workplace recognitions and the company’s description as a “thriving” employee-owned firm support continued talent attraction.
ASI is a dual-use software company that deploys predictive AI to the world's most complex operating environments. Backed by leading investors–including Andreessen Horowitz, Renegade Partners, and Spark Capital–we actively manage over 40% of all US air traffic across both public and private sector air operations. Partnering with major airlines like United and Alaska, we optimize thousands of flights daily, delivering...
Air Space Intelligence's Top Stability & Growth Strengths
Market Expansion: ASI has broadened beyond commercial aviation into defense and critical infrastructure, adding a DIU sustainment tool, a National Grid collaboration, and a Joby partnership alongside a major FAA program rolling out from the Washington, D.C. region. Company materials describe a scope spanning aviation, defense, logistics, energy and more, with locations in Boston, Washington, D.C., and Gdańsk.
Strong Market Position & Advantage: A 12-year, $875M FAA selection for FMDS and SMART—now in operational deployment around Washington, D.C.—signals meaningful competitive strength at national scale. Available reporting indicates ASI prevailed in a field that included larger incumbents, underscoring differentiation.
Strong Hiring & Retention: Signals include a “rapidly expanding team,” added offices, and recent defense-oriented roles (e.g., a Data Lead in Colorado Springs), with external coverage citing 165+ employees and plans to grow beyond 250 to deliver major programs. Active postings across technical and federal roles further reflect continued team build-out.
Relativity Space is on a mission to better connect humanity to space and the universe beyond our planet. Our medium-to-heavy lift reusable rocket, Terran R, will deliver customer payloads to orbit, meeting the growing demand for launch capacity. But that’s just the start. Achieving commercial success with Terran R will unlock new opportunities to advance science, exploration, and innovation, pioneering progress that...
Relativity Space's Top Stability & Growth Strengths
Market Expansion: Access to NASA’s NLS II and the U.S. Space Force’s NSSL Phase 3 Lane 1 broadens eligibility for future government missions, while multi‑launch agreements and a multibillion‑dollar backlog point to widening commercial demand. Facility growth on Florida’s Space Coast further extends operational reach.
Product Line Growth: Scope has expanded beyond launch services with an Interplanetary Sciences Program and a planned Mars science orbiter in 2028. Terran R has advanced from design into flight‑hardware production, engine acceptance testing, structural qualification, and launch‑site build‑out.
Strong Hiring & Retention: Headcount has risen materially to a reported ~2,000 employees across multiple U.S. locations. Concurrent expansion of Long Beach manufacturing and Cape Canaveral infrastructure indicates sustained organizational scaling.
Vast is developing next-generation space stations to ensure continuous human presence in space for America and its allies, enabling advanced microgravity research and manufacturing, and unlocking a new space economy for government, corporate, and private customers. Using an incremental, hardware-rich and low-cost approach, Vast is rapidly developing its multi-module Haven Station. Haven Demo’s 2025 success made Vast the only operational...

Vast's Top Stability & Growth Strengths
Investor Backing & Capital Strength: The company announced $500M of new funding in March 2026, bringing total private investment in its technology and facilities to over $1B. It says the capital will expand facilities, grow the team, and advance Haven-2.
Strong Hiring & Retention: Headcount is described as rising from fewer than 140 in 2023 to 700+ by early 2025 and 1,000+ by 2026. Additional figures point to around 1,236 employees in 2026, indicating sustained scaling.
Strategic Partnerships: NASA selected the company for its sixth private astronaut mission to the ISS targeted for 2027, and it maintains a transport relationship with SpaceX. International agreements and new payload partners further indicate expanding institutional and commercial ties.
At Shield AI, you won't wait years to see your work reach the field. You'll build hardware and software that operates in the real world right now, in the hands of the people who depend on it. Hivemind, our AI pilot, has been flying since 2018. It has flown more than 30 platforms, including an F-16, and it now sits under...
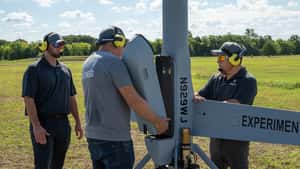
Shield AI's Top Stability & Growth Strengths
Strong Revenue Growth: Company reports indicate FY2026 orders and revenue doubled year over year. Management projections point to revenue well above $500 million for 2026, signaling rapid topline acceleration.
Investor Backing & Capital Strength: Recent financings include a $1.5 billion Series G and $500 million in preferred equity at a $12.7 billion valuation. These steps indicate substantial capital access and confidence from major financial backers.
Market Expansion: Program momentum includes a U.S. Air Force production award for CCA autonomy and a U.S. Navy ISR vehicle with a high task‑order ceiling. International traction spans India, Greece, Poland, and Taiwan, alongside plans for regional offices.
Ursa Major was founded to address a critical shortfall in the U.S. industrial base and bring a new model to aerospace and defense systems: we design and manufacture the world’s leading propulsion systems for space, hypersonic applications, and missile systems. Our products and technologies require an extraordinary team – a team that will mold tomorrow’s technologies while deploying today’s best....

Ursa Major's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Funding rounds, debt commitments, and a proposed SPAC with committed PIPE capital are described as expanding the capital base to accelerate production. Independent reporting also notes a step‑up valuation around $2.3B, reinforcing access to growth financing.
Strong Market Position & Advantage: Bookings exceeding $115M through Q3 2025 and multi‑year awards with organizations such as AFRL, Stratolaunch, and the U.S. Navy point to rising commercial traction. Operational milestones (100+ engines produced, 100,000+ seconds of testing) further support competitive standing.
Product Line Growth: Capabilities are described as expanding from liquid engines into hypersonics, solid rocket motors, space mobility, and complete systems like HAVOC. Manufacturing scale‑ups and a new Longmont facility were opened to meet this broader program mix.


Space was once the quietest place in the universe. Now, it's crowded, contested, and confrontational. We are True Anomaly: the only defense company focused exclusively on space defense. Founded in 2022 by ex-U.S. Space Force members, True Anomaly designs and builds advanced systems for space superiority: agile and powerful spacecraft platforms, mission software engineered for unmatched command and control, and payloads...
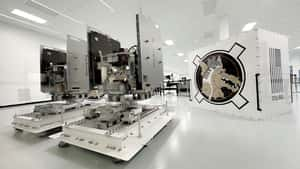
True Anomaly's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised has accelerated from a $260M Series C in 2025 to a $650M Series D in 2026, pushing cumulative funding above $1B and indicating substantial financing capacity. Funding is described as enabling facility expansion, manufacturing scale-up, and a larger mission cadence.
Strong Hiring & Retention: Headcount expanded from a small founding team to ~250 by end-2025, with stated targets of 500+ in 2026 and 1,000+ in 2028 alongside multi-site growth in Colorado and Long Beach. Independent coverage during 2026 also points to 250–300+ employees, reinforcing tangible workforce scaling.
Strong Market Position & Advantage: Selection for multiple Space Force efforts—such as VICTUS HAZE operations, Kronos software, GHOST-R/RG-XX, and Space-Based Interceptors—signals movement from small R&D awards toward larger defense procurement. The company reports transition from development flights to operational missions, including a space-to-space pursuit during VICTUS HAZE.

At AV, we build shoulder-to-shoulder with our customers, delivering systems shaped by real-world missions, not theoretical requirements. Now stronger than ever, we deliver integrated capabilities across every domain of modern warfare—from autonomous systems and loitering munitions to space-based platforms, directed energy, cyber and electronic warfare. We build to win today’s battles and shape tomorrow’s conflicts.
AeroVironment's Top Stability & Growth Strengths
Strong Revenue Growth: Recent quarters show record revenue and bookings, with management guiding to a significantly larger fiscal 2026 and citing robust demand across unmanned and counter‑UAS programs. Multiple large contract awards and a growing backlog reinforce visibility into continued top‑line expansion.
Diversified Revenue Streams: The BlueHalo acquisition and prior tuck‑ins broadened the portfolio into space, cyber, directed energy, and counter‑UAS alongside core UAS and loitering munitions. This wider mix creates additional avenues for growth across products and services and opens cross‑selling opportunities.
Strong Market Position & Advantage: The company is recognized as a leader in U.S. tactical small UAS and Western loitering munitions, anchored by long‑standing programs of record like Raven, Puma, and Switchblade. Combat validation and recurring Army orders signal durable franchise positions in these niches.

Epirus is a high-growth technology company developing solid-state, software-defined directed energy systems that enable unprecedented counter-electronics effects and power management solutions to optimize power efficiency in defense and commercial applications. With a constant emphasis on innovation, we are redefining the future of power to bring tomorrow’s capabilities to life, today. To deliver on our mission, we are always looking for...
Epirus's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $250 million Series D in March 2025 pushed total venture funding above $550 million, with the company stating the raise would “hyperscale” Leonidas manufacturing and scale operations. Private‑market trackers also placed valuation around $1.0B in that period, indicating substantial backing at a growth stage.
Market Expansion: Cross‑service traction includes U.S. Army prototype deliveries and follow‑on Gen‑II orders in 2025 and a Navy warfare center delivery in 2025, and an MoU with Singapore’s DSTA in January 2026 added international momentum. Public demos and exercises with U.S. and allied observers in 2025 further broadened visibility across theaters.
Strategic Partnerships: Integrations and teaming span General Dynamics Land Systems (autonomous Leonidas AR/AGV on GDLS/Kodiak platforms) and links with Anduril’s Lattice C2, with additional teaming like Peraton and Digital Force Technologies to extend the cUAS kill chain. These collaborations expand platform routes to market and support layered‑defense integration.

Ricondo & Associates, Inc. (Ricondo) is a full-service aviation consulting firm. The services we provide to airport owners and operators, airlines, and federal and state aviation-related agencies include facilities and operations planning, environmental planning, and financial planning. We provide technical consulting and project management services relating to airport facilities planning, airport master planning, financial analyses, environmental planning, feasibility studies, airfield...

Peraton is a next-generation national security company that drives missions of consequence spanning the globe and extending to the farthest reaches of the galaxy. As the world’s leading mission capability integrator and transformative enterprise IT provider, we deliver trusted, highly differentiated solutions and technologies to protect our nation and allies. Peraton operates at the critical nexus between traditional and nontraditional...

Peraton's Top Stability & Growth Strengths
Strong Market Position & Advantage: The company is positioned among the larger private government contractors, with continued top-tier placement in major industry rankings and material federal obligations that signal sustained scale. Large multi-year wins and access to marquee IDIQ/BPA vehicles reinforce competitiveness in sensitive national-security IT and mission support.
Strong Revenue Growth: Revenue direction is described as modestly increasing since 2023, supported by backlog indicators and multiple multi-year IT/cyber/mission support awards. Big-ticket awards like the eight-year USSOCOM task order and additional classified wins underpin the view of continued top-line expansion despite program churn.
Leadership Stability: Leadership updates in 2024–2025 are framed as not disrupting the company’s broader trajectory, with ongoing trade coverage highlighting awards and continued positioning as a go-to provider for sensitive missions. This suggests continuity in strategic direction through leadership change.

Howmet Aerospace Inc., headquartered in Pittsburgh, Pennsylvania, is a leading global provider of advanced engineered solutions for the aerospace and transportation industries. The Company’s primary businesses focus on jet engine components, aerospace fastening systems, and titanium structural parts necessary for mission-critical performance and efficiency in aerospace and defense applications, as well as forged wheels for commercial transportation. With nearly 1,150...
Howmet Aerospace's Top Stability & Growth Strengths
Strong Market Position & Advantage: The company is widely recognized as a leader across jet-engine components, aerospace fasteners, and forged aluminum truck wheels, supported by qualification moats and consolidated supply chains. Recent capacity additions, portfolio expansion, and record results reinforce pricing power and share in core aero end markets.
Strong Revenue Growth: Recent results show double-digit top-line growth with margin expansion and raised full-year guidance. Broad-based demand in commercial and defense aerospace and gas turbines, plus contributions from acquisitions, support continued momentum.
Future-Ready Strategy: Management is investing in turbine-blade capacity and expanding the fasteners portfolio via acquisitions such as CAM to meet sustained engine OEM and spares demand. A multi-year growth framework and portfolio shaping signal preparation for continued scale and mix improvements.
Decision Technologies, Inc. is a defense-focused technical support and engineering consultancy that helps Department of Defense and federal acquisition programs make better technology decisions. Its capabilities include systems engineering, program management, in-service engineering, equipment repair, research and development, test and evaluation, intelligence support, logistics, and RF and missile-sensor systems expertise. The company provides specialized, cost-effective solutions for complex defense missions.

We are GDIT. The people supporting some of the most complex government, defense, and intelligence projects across the country. We deliver. Bringing the expertise needed to understand and advance critical missions. We transform. Shifting the ways clients invest in, integrate, and innovate technology solutions. We ensure today is safe and tomorrow is smarter. We are there. On the ground, beside...
General Dynamics Information Technology's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Forward visibility looks durable due to a $100+ billion companywide backlog and repeated references to multi‑year contract wins that extend revenue coverage into 2026. The outlook frames demand as supported by defense and federal IT modernization priorities, suggesting the business can absorb near-term volatility.
Strong Market Position & Advantage: GDIT is positioned as a top-tier federal IT prime, reinforced by recurring placement in major federal contractor rankings and a steady cadence of marquee awards across DoD, intel, and civilian agencies. Its scale inside General Dynamics and ability to deliver mission-critical programs (e.g., enterprise IT modernization and large federal systems) signal competitive advantage in accreditation-heavy government work.
Diversified Revenue Streams: Revenue support is described as coming from multiple General Dynamics segments (Aerospace, Marine, Combat Systems, Technologies) alongside GDIT’s mix of defense, intelligence, health, and civilian programs. This multi-segment and multi-mission exposure reduces dependence on any single program area and supports stability through procurement cycles.
PSA Airlines is a wholly owned subsidiary of American Airlines that provides regional passenger air transportation on American’s behalf. It operates an all-jet fleet of regional aircraft, serving nearly 100 domestic and international destinations through hundreds of daily departures. The airline emphasizes teamwork, inclusivity, and professional development for its more than 5,500 employees, while supporting American’s broader customer network.

Founded in 2006, Rocket Lab is an end-to-end space company with an established track record of mission success. We deliver reliable launch services, spacecraft components, satellites and other spacecraft and on-orbit management solutions that make it faster, easier and more affordable to access space. Headquartered in Long Beach, California, Rocket Lab designs and manufactures the Electron small orbital launch vehicle...
Rocket Lab's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising sharply, with 2025 reaching $602M and new quarterly records around $200M in Q1 2026 alongside higher guidance for Q2 2026, signaling ongoing scale-up. Booking momentum and an expanding launch manifest reinforce the near-term top-line trajectory.
Diversified Revenue Streams: Business mix is broadening beyond launch as Space Systems becomes a large revenue driver, supported by prime-contract wins (e.g., SDA Tranche 3) and ongoing spacecraft and component deliveries. This diversification extends into payloads and new offerings such as the portable “GHOST” spaceport.
Strong Market Position & Advantage: Electron is identified as the most widely used small orbital launcher as of April 2026, underpinned by a high 2025 cadence and additional multi‑launch awards that took the manifest to 70+ missions. This niche leadership provides schedule and orbit-control advantages even as overall market leaders operate at larger scale.

ATI Inc. specializes in advanced materials, including Ni/Co-base superalloys and specialty steels, serving industries such as Aerospace and Defense. The company also offers services in environmental remediation, research, facility management, construction, and building design.
ATI Inc.'s Top Stability & Growth Strengths
Profitability: Recent results show rising earnings and expanding margins, and management raised full‑year earnings and free‑cash‑flow guidance. Margin strength is tied to higher‑value aerospace engine materials and forged components.
Strategic Partnerships: Long‑term agreements with GE Aerospace, Safran, Boeing, and Airbus, plus multi‑year aerospace sales commitments, indicate durable demand and preferred‑supplier positioning. Deep OEM integration provides visibility across long‑cycle engine and airframe programs.
Strong Market Position & Advantage: The company is recognized as a top‑tier Western supplier in aerospace‑grade titanium and nickel superalloys, supported by industry qualifications and distinctive isothermal forging capabilities. A record backlog and an increased aerospace and defense mix reinforce leadership in critical applications.



