Top Washington, DC Companies With Best Stability & Growth (2,637)
.png)
GRAIL is a healthcare company whose mission is to detect cancer early, when it can be cured. GRAIL is using the power of high-intensity sequencing, population-scale clinical studies, and state-of-the-art computer science and data science to enhance the scientific understanding of cancer biology, and to develop and commercialize pioneering products.
GRAIL's Top Stability & Growth Strengths
Strong Revenue Growth: Galleri and total revenue have risen consistently, with full-year 2025 up 17% and U.S. Galleri up 26%, followed by Q1–Q2 2026 total revenue gains of 28% and 26% alongside 50% and 35% volume growth. This cadence, including Q4 2025 Galleri revenue up 31%, indicates sustained commercial momentum after the June 2024 spin‑off.
Strategic Partnerships: Channel and platform integrations such as Epic EHR and Quest Diagnostics, plus collaborations like Samsung for Asian commercialization, are expanding access and streamlining ordering. Additional distribution wins (e.g., Priority Health employer plans and digital health channels) reinforce multi‑channel penetration for Galleri.
Investor Backing & Capital Strength: The company reports a substantial cash balance (~$861.6M as of Q2 2026) and closed a $110M equity financing with Samsung, bolstering financial flexibility. Public listing post‑spin‑off further enhances capital‑markets access to fund trials and commercialization.
Build what’s next — with tech that matters PwC provides professional services across Audit and Assurance, Advisory and Tax — powered by a global network of over 370,000 people in 149 countries. You may know us for our business expertise, but technology is core to how we help clients move faster, build trust and deliver meaningful outcomes. As a technologist, you’ll work...

PwC's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Revenue increased in FY2024 and again in FY2025 to a record ~US$56.9B, with all three lines of service expanding. Growth in the Americas and EMEA helped offset softness in parts of Asia Pacific, indicating steady, if modest, momentum.
Innovation-Driven Growth: A multi‑year push includes roughly US$1.5B to expand and scale AI capabilities, alongside AI‑enabled platforms and dedicated AI hubs/factories. These investments are positioned to extend growth beyond core assurance and tax and to support new, tech‑enabled offerings.
Strong Market Position & Advantage: As one of the Big Four with record scale and repeated “Leader” placements in independent analyst evaluations, the firm operates from a top‑tier competitive position. Rising brand value and leadership recognition in selected consulting categories reinforce commercial strength.
As the foundation for secure markets, OCC is a customer-driven organization that delivers world-class Risk Management, Clearing, and Settlement Services for a sophisticated mix of financial products that includes standard options, stock loans, and futures contracts.
OCC's Top Stability & Growth Strengths
Strong Revenue Growth: Clearing fee revenue and net income increased sharply in 2025 alongside record contract volumes, and 2026 monthly updates indicate continued double‑digit year‑over‑year activity. These trends point to rising financial throughput consistent with accelerated operating scale.
Market Expansion: The organization began clearing for MIAX Futures in May 2026, extending coverage to 21 exchanges and trading platforms. This broader network signals a widening footprint across venues and products.
Strong Market Position & Advantage: As the sole central counterparty for U.S. listed options and a designated SIFMU, it operates from an entrenched position with unmatched scale. Record multi‑year volumes and substantial risk resources reinforce that advantage.
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Group sales increased 10% in 2025 and 9% in the first half of 2026, with underlying EBIT up 11%, and full‑year 2026 sales and EBIT guidance raised. These trends indicate broad-based momentum that includes U.S. programs.
Resilient & Sustainable Growth: A record order backlog of about £83.6–£84.0bn provides multi‑year revenue visibility and underpins capacity additions at U.S. sites. Free cash flow also strengthened, reinforcing durability of the growth profile.
Market Expansion: Facility expansions and upgrades in Endicott (NY), Austin (TX), Hudson (NH), and a new Utah site, alongside the 2024 acquisition of Ball Aerospace (now Space & Mission Systems), enlarge the U.S. footprint and portfolio. Recent U.S. and international contract wins further extend reach across markets.

Rokt is the global leader in ecommerce, unlocking real-time relevance in the moment that matters most - The Transaction Moment. Rokt’s AI Brain and Ecommerce Network powers billions of transactions connecting hundreds of millions of customers, and is trusted to do this by the world’s leading companies including Live Nation, Macy’s, Fanatics, AMC Theatres, PayPal, Uber, Hulu, Staples, Albertsons and...

Rokt's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described at roughly $600M in 2024 with about 43% year-over-year growth and an estimated $900M annualized run-rate by October 2025. External recognitions like Deloitte Technology Fast 500 and the FT Americas’ Fastest Growing Companies 2026 align with this expansion trajectory.
Product Line Growth: Acquisitions of AfterSell (2024), mParticle (January 2025), and Canal (July 2025) expanded capabilities into SMB upsells, customer data platform functionality, and distributed commerce via Rokt Catalog. These additions broaden the offering beyond core checkout ads and support continued scale.
Investor Backing & Capital Strength: A January 16, 2025 secondary share sale valued the company at about $3.5B, signaling strong late-stage investor support. Coverage also notes a potential 2026 IPO target, consistent with capital-markets readiness.
Upside is a technology company that increases the financial power of people and businesses in the real world. Our technology has helped millions of people get more purchasing power on the things they need, and tens of thousands of brick-and-mortar businesses earn measurable profit. Billions of dollars in commerce run through the Upside platform every year, and that value goes...
Upside's Top Stability & Growth Strengths
Market Expansion: The network is expanding with 14,669 new retailer locations and 1.6 million new customers added in 2025, alongside claims of 100,000+ participating locations and reach to tens of millions of consumers. New 2026 rollouts such as Save Mart’s nearly 200 stores and a New Jersey fuel model with QuickChek illustrate continued geographic and category expansion.
Strategic Partnerships: Recent additions and expansions with The Save Mart Companies, Coen Markets, Wendy’s via Meritage, and Desert De Oro Foods, plus integrations with Varo Bank and Marqeta, broaden access beyond the standalone app. Partnerships with platform players (e.g., Uber) and fuel brands support scaled distribution across verticals.
Product Line Growth: Growth is expanding beyond fuel, with restaurant transactions up 64% year over year in July 2025 and over half a million grocery offers claimed monthly. Ongoing grocery and QSR additions in 2026 are positioned to further lift non‑fuel transactions.
Ursa Major was founded to address a critical shortfall in the U.S. industrial base and bring a new model to aerospace and defense systems: we design and manufacture the world’s leading propulsion systems for space, hypersonic applications, and missile systems. Our products and technologies require an extraordinary team – a team that will mold tomorrow’s technologies while deploying today’s best....

Ursa Major's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $138M Series D/D-1 (Nov 30, 2023) followed by a $100M Series E plus $50M in debt (Nov 18, 2025) provides substantial resources for scaling. Management links this capital to accelerating production across hypersonics, solid rocket motors, and space mobility.
Market Expansion: A new Longmont, Colorado manufacturing facility opened on August 20, 2026 alongside a broader multi‑site build‑out, with the state citing potential for up to 1,850 new jobs. Company updates say it “completed the next phase” of its scaling plan, indicating increased capacity.
Product Line Growth: Hot‑fires and flight activity across Draper and solid‑rocket‑motor programs, plus an SRM pathfinder completion and the unveiling of HAVOC, mark a shift from R&D toward production. Government awards in hypersonics and SRMs (e.g., $28.6M AFRL; $10M Navy MK 104) broaden applications and demand.
Together, we turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Profitability: All‑time profit leadership and continued gains in 2024–2025 underpin sustained investor demand and fee generation. Returning roughly $5 billion of 2025 profits while maintaining about $66–$67 billion in AUM highlights durable earnings and disciplined sizing.
Market Expansion: The Miami headquarters build, additional 2026 real‑estate purchases, and a planned Dubai office point to an expanding physical footprint and long‑dated strategic commitments. Acquisitions in power and energy trading (e.g., FlexPower and Paloma Natural Gas) extend reach into global commodities markets.
Strong Hiring & Retention: Ongoing large‑scale recruiting, including new cohorts for the Citadel Associate Program and other early‑career pipelines, signals sustained investment in talent to support platform growth.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Strong Revenue Growth: Consolidated revenues increased from $253 billion in 2024 to $270.6 billion in 2025, with quarterly gains such as Q4 2025 up 8% year over year. Growth was led primarily by Optum Rx and supported by steady contributions from Optum Insight.
Market Expansion: Expansion through acquisitions such as Holston Medical Group (August 2025) and Alegeus (July 2026), alongside earlier combinations like Change Healthcare and Atrius Health, broadened capabilities across care, pharmacy, and payments. These moves extend Optum’s platform into adjacent services and operating domains.
Diversified Revenue Streams: A multi-segment model—Rx, Insight, and Health—helps sustain aggregate growth even as individual lines vary, with pharmacy and technology businesses offsetting care-delivery softness. Parent-company commentary continuing to frame Optum as a growth engine and raising 2026 guidance underscores the benefit of this portfolio effect.

Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent analysts continue to place Qualtrics at the front of its market, with Gartner naming it a Leader in the Magic Quadrant for Voice of the Customer Platforms and positioning it highest on Ability to Execute and furthest on Completeness of Vision. This standing typically aligns with robust enterprise demand and supports commercial momentum.
Market Expansion: The company closed a $6.75 billion acquisition of Press Ganey Forsta on May 18, 2026, materially expanding its healthcare experience footprint and enlarging its data assets. Such scope increases are noted as common precursors to revenue growth and broader vertical penetration.
Innovation-Driven Growth: Qualtrics highlights rapidly expanding AI capabilities and analysis of billions of interactions annually, with usage of AI features surging and adoption widespread among large enterprise accounts. This product momentum supports upsell and cross‑sell into the installed base.
Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising rapidly, with Q2 FY2026 results well above the prior year and management increasing the full‑year outlook while guiding continued momentum into Q3. These signals indicate sustained top‑line acceleration rather than a one‑off spike.
Resilient & Sustainable Growth: Contracted demand expanded, as current remaining performance obligations grew strongly in Q2 FY2026. Upmarket customer gains and elevated net retention further point to durable expansion from existing cohorts.
Innovation-Driven Growth: An AI/edge “inference layer” launch and ongoing Workers AI/Radar updates show active platform expansion and growing developer adoption. This product velocity positions the business to capture emerging AI‑driven workloads.
Altana powers agentic trade workflows and public-private collaboration across product value chains — the source of truth for where products come from. With Altana, businesses can prove compliance before goods ship and build more efficient, resilient, and secure supply chains. Logistics providers can automate the full brokerage workflow, and governments can promote economic security, manage borders, and enable the flow...

Altana's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $200M Series C in July 2024 at a reported $1B valuation provides material resources for product expansion and scaling. Active hiring across engineering, product, sales, and government affairs aligns with investment-fueled growth plans.
Market Expansion: U.S. Customs and Border Protection executed a formal two-year contract to test the platform in 2025. FedRAMP High authorization in February 2026 reduces procurement friction with federal agencies and regulated customers, positioning the company for broader rollout.
Product Line Growth: The July 2026 acquisition of Cervo AI enables an end-to-end, agentic customs brokerage workflow. Altana states this brings its logistics customer base to “8 of the 10 largest logistics providers,” indicating capability-driven expansion.
ASI is a dual-use software company that deploys predictive AI to the world's most complex operating environments. Backed by leading investors–including Andreessen Horowitz, Renegade Partners, and Spark Capital–we actively manage over 40% of all US air traffic across both public and private sector air operations. Partnering with major airlines like United and Alaska, we optimize thousands of flights daily, delivering...
Air Space Intelligence's Top Stability & Growth Strengths
Strong Market Position & Advantage: The FAA selected ASI in June 2026 to help modernize the National Airspace System through a multi-year program that brings its Flyways AI into core ATC operations. This selection signals scale-up potential and long-term revenue visibility.
Customer Loyalty & Retention: Alaska Airlines adopted Flyways in 2021 and renewed the partnership in 2024, citing operational and fuel-efficiency benefits. Alaska’s subsequent reports and white papers describe ongoing, production use, indicating continued value delivery.
Market Expansion: Partnerships announced in 2026 with Joby Aviation for eVTOL integration and with National Grid to apply “operational AI” to the electric grid show movement into adjacent markets beyond traditional airlines. These moves broaden relevance across aviation and critical infrastructure.
Applecart advises the C-suites of hundreds of industry-leading organizations spanning over 100 Fortune 500 companies, top communications and advertising agencies, major trade associations, leading nonprofit organizations, and governments. Applecart’s platform enables CEOs, Chief Corporate Affairs Officers, CCOs, CMOs and other C-suite executives to generate visibility for their most valuable content with critical decision makers and those in their orbits across...

Applecart's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Recent funding from Blackstone Growth—$100 million in January 2026 at a reported $500–700 million valuation—signals strong external confidence and provides runway to scale. Company communications describe the capital as intended to fuel continued growth at scale.
Strong Revenue Growth: Multiple recent job postings describe revenue up roughly 10x over the last four years, reflecting a fast-growth trajectory. These statements frame the business as expanding rapidly across its core offerings.
Strong Hiring & Retention: Company materials and LinkedIn indicate the team grew to more than 200 employees in 2025 with headcount up nearly 5x over four years, and the listed company-size band of 201–500 suggests ongoing expansion. Active hiring posts reinforce that scaling is underway.
Octus, was founded in 2013 with a simple conviction: credit decisions deserve clarity, not chaos. Markets were fragmented. Intelligence was gated. Data lived in silos. Professionals were forced to stitch together incomplete pictures while the clock kept running. We built Octus to change that. Octus is the essential credit platform that tracks the entire credit lifecycle. From origination and underwriting to...
Octus's Top Stability & Growth Strengths
Product Line Growth: Launches of CreditAI (March 10, 2026) and the MCP connector (July 14, 2026) show active expansion of AI-enabled features and distribution into third-party LLMs. Additional rollouts like CreditAI Vault and covenant/term analytics in 2025 reinforce ongoing product investment.
Market Expansion: Acquisitions of Sky Road (2025) and LevPro (2026) extend Octus from intelligence and data into portfolio management and trading workflows for CLO and private-credit managers. A 43,000‑square‑foot New York office lease and reported growth in global users suggest a broader footprint and installed base.
Strong Hiring & Retention: Built In lists roughly 808 employees, seven offices, and active hiring across functions, and other sources describe substantial onboarding in 2025. These indicators point to headcount expansion supporting scale.
Wipfli is a leading national advisory and accounting firm with nearly 100 years of serving ambitious middle-market organizations. We understand our clients' unique challenges and help them succeed on their terms through assurance, tax, advisory, outsourcing and technology services. With 2,900+ associates and global alliances, we combine national capabilities with local relationships. "Wipfli" is the brand name under which Wipfli LLP...

Wipfli's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue has increased over consecutive fiscal years to $638.4 million in FY26, building on gains reported in FY24 and FY25. This points to continued top-line expansion.
Investor Backing & Capital Strength: A significant minority investment from New Mountain Capital was announced on August 1, 2025 to accelerate growth, technology and acquisitions under an alternative practice structure. This provides funding capacity to scale and pursue M&A.
Innovation-Driven Growth: The mix is shifting toward advisory and technology services (nearly half of revenue per the firm), with capability additions reinforcing this pivot. The CompliancePoint transaction further broadens cybersecurity, privacy and compliance offerings.
Vast is developing next-generation space stations to ensure continuous human presence in space for America and its allies, enabling advanced microgravity research and manufacturing, and unlocking a new space economy for government, corporate, and private customers. Using an incremental, hardware-rich and low-cost approach, Vast is rapidly developing its multi-module Haven Station. Haven Demo’s 2025 success made Vast the only operational...

Vast's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor backing is described as substantial, including a $500 million financing in March 2026 to accelerate Haven stations, with total private capital cited at over $1 billion in multiple summaries. This provides runway for manufacturing, hiring, and mission preparation.
Strategic Partnerships: Partnerships with major institutions are expanding, highlighted by NASA’s selection for the sixth private astronaut mission to the ISS (no earlier than summer 2027), SpaceX launch and crew transport arrangements, and international agreements with France and the UK. These alignments signal access to customers, transport, and payload ecosystems important for near-term operations.
Innovation-Driven Growth: Technical progress is evidenced by the Haven Demo spacecraft that launched in late 2025 and was successfully deorbited in February 2026, alongside ongoing Haven‑1 integration and testing toward a 2027 debut. This sequence of flight heritage and hardware milestones underpins momentum toward initial commercial station operations.
TransUnion is a global information and insights company that makes trust possible by ensuring that each consumer is reliably and safely represented in the marketplace. We do this by having an accurate and comprehensive picture of each person. This picture is grounded in our legacy as a credit reporting agency which enables us to tap into both credit and public record...
TransUnion's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is advancing at a double‑digit pace in early 2026, with successive quarters outperforming internal targets and full‑year guidance raised. Momentum is driven by U.S. Financial Services and improving International trends.
Profitability: Earnings are expanding, with adjusted EBITDA and adjusted EPS up year over year and full‑year guidance implying further gains. Absolute EBITDA improved even as the company invested and integrated recent acquisitions.
Market Expansion: Reach is widening through improved performance in Canada, the U.K., and India, alongside completed acquisitions in Mexico and a mobile division that extend capabilities. These moves contributed to stronger reported results and a higher outlook.
Relativity Space is on a mission to better connect humanity to space and the universe beyond our planet. Our medium-to-heavy lift reusable rocket, Terran R, will deliver customer payloads to orbit, meeting the growing demand for launch capacity. But that’s just the start. Achieving commercial success with Terran R will unlock new opportunities to advance science, exploration, and innovation, pioneering progress that...
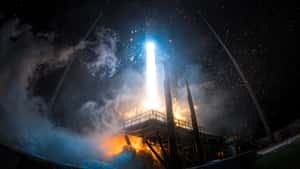
Relativity Space's Top Stability & Growth Strengths
Market Expansion: Access to government and commercial markets is broadening, with on‑ramp into NSSL Phase 3 Lane 1 and a larger Florida manufacturing/test footprint supporting capacity. Multi‑launch commercial agreements and a growing contract backlog point to expanding go‑to‑market ahead of a late‑2026 Terran R debut.
Diversified Customer Base: Demand spans government and blue‑chip telecom operators (e.g., SES and Intelsat), contributing to a multibillion‑dollar backlog across a dozen‑plus customers. This mix provides multiple paths to convert contracts once Terran R begins flying.
Strong Hiring & Retention: Headcount has expanded from roughly 1,200 in 2023 to about 2,000 in 2026, alongside elevated job postings. This staffing ramp aligns with ongoing Terran R production, testing at Stennis, and pad buildout at Cape Canaveral.

Space was once the quietest place in the universe. Now, it's crowded, contested, and confrontational. We are True Anomaly: the only defense company focused exclusively on space defense. Founded in 2022 by ex-U.S. Space Force members, True Anomaly designs and builds advanced systems for space superiority: agile and powerful spacecraft platforms, mission software engineered for unmatched command and control, and payloads...

True Anomaly's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised accelerated with a $260M Series C in April 2025 followed by a $650M Series D in April 2026, and third‑party trackers also reflect the D round and cumulative capital. These financings are described as enabling vertical integration, facility expansion, product development, and hiring.
Market Expansion: Contracts broadened from hardware into software, including July 15, 2026 selection to deliver Mosaic for the Space Force’s Kronos battle‑management program alongside spacecraft work like VICTUS HAZE. Company and trade updates also indicate participation on vehicles such as Andromeda and expanding mission scope (e.g., Mission X‑3 in June 2026 and VICTUS HAZE operations).
Strong Hiring & Retention: Employee growth indicators point to several hundred staff by mid‑2026 with plans to exceed 500 by year‑end 2026 and target 1,000 by 2028. New facilities—including a 90,000‑square‑foot Long Beach factory and expanded GravityWorks in Colorado—support ramping manufacturing and engineering capacity.