

Top Fintech Companies in Phoenix, AZ (125)
Formally known as Freedom Financial Network, Achieve launched in 2022 as the leading digital personal finance company helping everyday people get on, and stay on, the path to a better financial future. Achieve delivers personalized financial solutions for real people through intelligent technology and an empathetic human touch. From the single parent trying to buy a home to the overworked...
Achieve's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital access is evident in repeated personal-loan and HELOC securitizations, with cumulative issuance reported above $7.5B and the addition of a debt‑settlement‑fee securitization channel. These moves indicate diversified funding sources supporting larger origination volumes.
Market Expansion: Distribution is broadening through the launch of Achieve Pro for third‑party HELOC origination, alongside HELOC availability expanding to 31 states covering nearly 80% of the U.S. population. These steps point to wider geographic reach and channel diversification.
Resilient & Sustainable Growth: Operational scale shows multi-year momentum, with total loan originations rising from above $12B (Oct 2024) to above $14B (Aug 2026) and HELOC securitizations growing from above $920M to above $1.7B over a similar period. Reported customer milestones (1M+ to 2M+ served) further underscore sustained platform expansion.
Wells Fargo & Company (NYSE: WFC) is a leading financial services company that has approximately $2.2 trillion in assets. We provide a diversified set of banking, investment and mortgage products and services, as well as consumer and commercial finance, through our four reportable operating segments: Consumer Banking and Lending, Commercial Banking, Corporate and Investment Banking, and Wealth & Investment Management....
Wells Fargo's Top Stability & Growth Strengths
Profitability: Financial results indicate rising earnings, with full-year net income higher year over year and additional gains in subsequent quarters. EPS and returns improved as lending and fee-based businesses strengthened after regulatory constraints eased.
Market Expansion: The lifting of the Federal Reserve’s asset cap enabled renewed balance-sheet growth, reflected in higher loans, deposits, and total assets. Growth is described as broadening across cards, auto lending, commercial banking, investment banking, and wealth management.
Cost & Operational Efficiency: Operations are being streamlined through headcount reductions and branch optimization, supporting better efficiency and operating leverage. These actions have coincided with increased dividends and share repurchases.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating income has risen materially alongside growth, with the latest quarter reporting meaningful GAAP and adjusted operating profits and expanding margins. This indicates the business is scaling while improving earnings quality.
Resilient & Sustainable Growth: Gross profit is expanding at a strong, accelerating pace, with both Cash App and Square contributing and management raising full‑year outlooks. Longer‑term disclosures also highlight multi‑year compounding in gross profit per user across ecosystems.
Cost & Operational Efficiency: A leaner organizational structure and disciplined spending have driven record adjusted operating margins and improved operating leverage. Efficiency gains appear to be a second engine alongside revenue drivers.
Wipfli is a leading national advisory and accounting firm with nearly 100 years of serving ambitious middle-market organizations. We understand our clients' unique challenges and help them succeed on their terms through assurance, tax, advisory, outsourcing and technology services. With 2,900+ associates and global alliances, we combine national capabilities with local relationships. "Wipfli" is the brand name under which Wipfli LLP...

Wipfli's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has increased across FY24–FY26 with consecutive year-over-year gains, indicating steady top-line momentum. Company disclosures describe this as “purposeful” and oriented toward sustainable long-term growth alongside expansion in advisory and technology.
Investor Backing & Capital Strength: A strategic minority investment from New Mountain Capital was secured to accelerate growth, fund technology and talent, and support acquisitions. This signals enhanced capital resources to pursue the firm’s expansion agenda.
Product Line Growth: Capabilities have broadened through acquisitions and internal investment, adding areas such as cybersecurity, privacy, risk, digital transformation, and technology services (e.g., CompliancePoint and Harbour Results transactions). New leadership roles focused on growth, sales, and corporate development reinforce the expanding services mix.
We’re a Detroit-based company obsessed with helping our clients achieve the dream of homeownership and financial freedom. Our flagship business, now known as Rocket Mortgage, was founded by Dan Gilbert in 1985. Since then, we’ve revolutionized the mortgage industry – twice – and taken our place as the industry leader. Today, the Rocket brand is synonymous with providing simple, fast...

Rocket's Top Stability & Growth Strengths
Strong Revenue Growth: 2025 revenue rose to $6.7B from $5.1B in 2024, and Q1–Q2 2026 revenues of roughly $2.94B and $2.78B were nearly double the prior-year periods. Adjusted revenue and earnings also accelerated materially over these intervals.
Strong Market Position & Advantage: Purchase-market share increased from 5.5% in Q4 2025 to 6.2% in Q2 2026, while refinance share reached 14.3%, alongside leadership claims in home equity and a top-tier servicing footprint. These gains occurred as closed mortgage volumes climbed in 2025 and continued strongly into early 2026.
Diversified Revenue Streams: The servicing portfolio expanded to about $2.1T and ~9.5M loans, with management indicating roughly $5B of annualized recurring cash flow from servicing and deposit income—reducing dependence on quarterly originations. Additional contributions from Rocket Money subscriber growth and home-equity lending broaden the mix.
Gusto is a modern, online small business platform that helps small businesses take care of their teams. On top of full-service payroll, Gusto offers health insurance, 401(k)s, expert HR, and team management tools. Today, Gusto offices in Denver, San Francisco, and New York serve more than 400,000 businesses. Our customers come from all walks of life, and so do we. We...
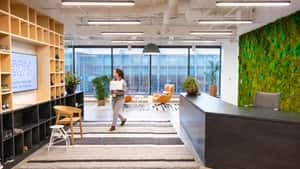
Gusto's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue reportedly surpassed $1 billion on a trailing-12-month basis, with management indicating growth accelerated across five consecutive quarters. A customer base exceeding 500,000 businesses underscores scale consistent with continued top-line expansion.
Healthy Cash Flow: The company is described as cash-flow positive for several years, indicating growth supported by operating discipline. This suggests expansion that is not overly dependent on external financing.
Product Line Growth: The acquisition of Guideline added retirement services to payroll/HR/benefits, and expansions into compliance, financial tools, and embedded capabilities broaden the offering. These additions create new monetization paths beyond core payroll.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...
Square's Top Stability & Growth Strengths
Profitability: Square gross profit increased year over year in 2025 and again in recent quarters, with gains driven by processing, software, and financial solutions like Square Loans. Filings indicate this momentum continued into 2026, with growth excluding hardware also improving.
Strong Market Position & Advantage: Square is described as a leader in small-business POS and commerce, serving millions of sellers and processing a very large volume of payments. Industry recognition and scale suggest durable competitive positioning in its core segments.
Market Expansion: International payment volume is growing faster than the U.S., and sectors such as food and beverage led recent gains. Seller acquisition accelerated late in 2025, indicating widening reach across geographies and customer segments.
As a member-owned, not-for-profit financial cooperative, we are guided by the credit union philosophy of “people helping people.” Putting people over profit guides our everyday business decisions. Unlike many financial institutions, we aren’t privately owned. As a cooperative, we are owned by our members. This drives us to do right by the member, and right by each other as coworkers....
BECU's Top Stability & Growth Strengths
Market Expansion: Physical footprint has been expanding with new Neighborhood Financial Centers in 2025 and additional openings announced for 2026–2027. A proposed combination with SAFE Credit Union would extend reach into California, pending required approvals and member vote.
Investor Backing & Capital Strength: Cooperative equity increased over the latest period, and the 2025 net‑worth ratio was reported well above well‑capitalized thresholds. This strong capital position supports continued investment and resilience.
Resilient & Sustainable Growth: After a flat patch in 2025, mid‑2026 results indicate renewed balance‑sheet growth across assets, loans, and member shares. Membership also continued to rise in 2024 and 2025, reinforcing durable franchise momentum.

Engine is the AI-native platform for intelligent travel. For a decade, Engine has built the proprietary technology and supply behind modern business travel, serving 40,000 customers and 2 million travelers, along with leading travel and AI companies that build on Engine's infrastructure. One system powers business travel, group travel, human agents, and AI agents. Engine has been recognized as one of...

Engine's Top Stability & Growth Strengths
Strong Revenue Growth: Reported roughly 70% year-over-year revenue growth in 2024 alongside expectations of 10M+ room nights points to strong top-line momentum. Independent press coverage corroborated these figures during the 2024 financing round.
Profitability: The company was described as profitable at scale around its 2024 funding milestone, indicating growth accompanied by operational discipline. Continued expansion into 2025–2026 has been paired with statements of cash-flow positivity.
Investor Backing & Capital Strength: A $140M Series C at a $2.1B valuation and a funding history totaling over $200M signal strong access to capital and investor confidence. The rising valuation from 2021 to 2024 underscores sustained financial backing.

Western Alliance Bancorporation (NYSE: WAL) is one of the country’s top-performing banking companies. Its primary subsidiary, Western Alliance Bank, Member FDIC, offers a full spectrum of tailored commercial banking solutions and consumer products, all delivered with outstanding service by banking and mortgage experts who put customers first. Serving clients across the country wherever business happens, Western Alliance Bank operates individual,...
Western Alliance Bank's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent rankings place the company near the top among large regional banks, and it shows distinctive leadership in specialty lines such as association/HOA banking and business escrow. Management and franchise accolades reinforce competitive standing within its asset class.
Strong Revenue Growth: Net revenue and pre-provision earnings expanded year over year, with margin improving alongside rising deposits, assets, and loans through late 2025 into early 2026. This points to solid underlying earnings power as the balance sheet scales.
Resilient & Sustainable Growth: Post-2023 stabilization has transitioned into renewed growth in deposits and assets, with core earnings capacity remaining intact despite episodic portfolio clean-ups. Momentum across 2025–2026 supports a durable expansion path.
HELP US REIMAGINE MONEY. At PayPal, we believe that now is the time to democratize financial services so that moving and managing money is a right for all citizens, not just the affluent. We are driven by this purpose, and we uphold our cultural values of collaboration, innovation, wellness and inclusion as our guide for making decisions and conducting business every...
PayPal's Top Stability & Growth Strengths
Strong Market Position & Advantage: PayPal operates at global scale with one of the largest online payment throughputs and broad merchant checkout ubiquity across brands. Its wallet remains widely embedded in online commerce and recognized across key geographies.
Diversified Revenue Streams: The portfolio spans consumer wallets, enterprise processing, peer-to-peer, cross‑border, payouts, and BNPL, enabling participation across multiple payment flows. This breadth supports both consumer and enterprise merchants worldwide through PayPal, Venmo, Braintree, Xoom, and Zettle.
Healthy Cash Flow: The business generated substantial free cash flow in the latest quarter. It also returned significant capital via share repurchases and dividends, indicating ongoing cash generation capacity.

Established in 1999 in New Zealand, Windcave stands as a high-growth, innovative leader in payment technology. We offer a seamless, global platform catering to diverse clientele including corporate, banking, and SMEs. By consolidating payment needs through a single provider, Windcave streamlines payment processes, ensuring superior experiences for countless global brands. Our services span online, in-store, and unattended environments, boasting features...
Broadridge Financial Solutions, Inc. (NYSE: BR), is a global fintech leader, delivering technology-driven solutions that drive digital transformation for banks, broker-dealers, asset and wealth managers and public companies. At Broadridge, we are committed to making a difference. Our unique culture is guided by the Service-Profit Chain—the idea that success is mutual, directly connecting employee engagement, client satisfaction, and the creation...
Broadridge's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising year over year, with recent quarters also showing growth in recurring revenues and management lifting forward guidance. This pattern supports a view of steady expansion rather than a one-off increase.
Innovation-Driven Growth: Innovation appears to be converting into measurable adoption, highlighted by the rapid scaling of the Distributed Ledger Repo Platform and tokenized settlement volumes. This suggests new technology initiatives are contributing to growth alongside the core business.
Strong Market Position & Advantage: The company is positioned as a core infrastructure provider in investor communications and post-trade workflows, with large-scale processing volumes and high switching costs implied by embedded platforms. This entrenched role supports resilience through recurring, mission-critical demand.
Experience. Expertise. Extraordinary Results. PrimeLending, a PlainsCapital Company (NMLS: 13649), is a proven powerhouse in home lending, combining personal guidance and local expertise with fast service, more choices and the flexibility to meet homeowners’ unique needs. We’re a national home lender relentlessly focused on empowering our customers to boldly pursue their homeownership goals. Whether a borrower is looking to buy, refinance...
Financial advice is changing, and at LPL Financial, we’re at the forefront. We’re building a future where advisors can—with no friction or complexity, as simple as turning the dials—pick the business model, services, technology, and product mix that best meet their clients’ needs. With one platform, one sign-on, and one team to call, you can take your business anywhere you want...
LPL Financial's Top Stability & Growth Strengths
Strong Market Position & Advantage: LPL is widely regarded as the category leader in the U.S. independent broker‑dealer/advisor‑platform market, ranked the largest by revenue and advisor count with broad multi‑channel reach. Scale has been reinforced by acquisitions such as Atria, The Investment Center, and Commonwealth that materially expanded advisors and assets.
Strong Revenue Growth: Full‑year 2024 revenue increased to $12.39B from $10.05B, with Q4 2025 adjusted EPS at $5.23 and net income up year over year amid record platform scale. Rising client assets to roughly $2.37T and robust net new assets and recruited assets through 2025 underpin sustained top‑line momentum.
Strong Hiring & Retention: The advisor network expanded to approximately 32,200 by early 2026, with multi‑year leadership in net advisor adds and significant recruited assets. A scalable onboarding model and institutional wins (e.g., Wintrust) supported continued headcount and asset inflows.
AssetMark’s platform empowers advisors to provide the highest level of service possible to their clients. We provide financial advisors with innovative solutions, insightful guidance, and our undivided attention. Our company’s mission is centered around helping financial advisors make a difference in the lives of their clients. To help them do that, we aim to provide advisors with holistic support. Whether...
AssetMark's Top Stability & Growth Strengths
Market Expansion: Disclosures describe continued scaling via acquisitions (e.g., Morningstar Wealth’s TAMP assets and Efficient Advisors), geographic growth with a new East Coast hub in Charlotte, and entry into private markets. The advisor and household counts, along with rising platform assets, indicate broader footprint and reach.
Strong Market Position & Advantage: AssetMark is repeatedly characterized as a leader in the TAMP/wealth platform segment and was named Best Overall TAMP in 2025. Significant platform scale and industry recognition support its competitive standing.
Investor Backing & Capital Strength: The go-private transaction with GTCR underscores sponsor support and resources for further investment and M&A. Company statements highlight ambitions to materially scale the business under this backing.

As of September 30, 2023, First Busey Corporation (Nasdaq: BUSE) was a $12.26 billion financial holding company headquartered in Champaign, Illinois. Busey Bank, a wholly-owned bank subsidiary of First Busey Corporation, had total assets of $12.23 billion as of September 30, 2023, and is headquartered in Champaign, Illinois. Busey Bank currently has 46 banking centers serving Illinois, eight banking centers serving...
Busey's Top Stability & Growth Strengths
Profitability: Q1 2026 diluted EPS of $0.67 exceeded expectations, with net interest margin expanding to 3.77%. Adjusted returns (ROAA ~1.42%, ROATCE ~14.12%) and an improved efficiency ratio indicate strengthening earnings power post‑integration.
Market Expansion: The CrossFirst combination extended the franchise to roughly 80 locations across about 10 states, followed by new offices in Denver’s Cherry Creek, Scottsdale (Phoenix), Oklahoma City, and Cape Coral. Continued branch additions in growth metros signal organic build‑out alongside M&A.
Diversified Revenue Streams: A record quarter for wealth management fees and $15.65 billion in assets under care underscore meaningful noninterest income contribution. Expanding treasury and payments capabilities complement core banking to support steadier revenue mix.

Welcome to ATLAS Advisors That Listen And Serve We are a regional professional services firm with services in Accounting, Tax, Audit, Consulting, Business Valuation, Insurance, Financial Services, Marketing, Human Resources, IT and more! We seek to provide a holistic approach of services to our clients to help them achieve their goals in business and life. We service clients all of the globe. We...

Osaic provides the support, resources, and community designed for the future of wealth management. Securities and investment advisory services are offered through the firms: Osaic Wealth, Inc., Osaic Institutions, Inc., Osaic FA, Inc., Osaic FS, Inc., and Triad Advisors, LLC, broker-dealers, registered investment advisers, and members of FINRA and SIPC. Securities are offered through Securities America, Inc., American Portfolios Financial Services,...
Osaic's Top Stability & Growth Strengths
Strong Market Position & Advantage: Scale and ranking are repeatedly highlighted, with about 11,000 financial professionals and $700B+ in assets under administration placing the firm among the largest independent wealth platforms. Leadership references include top-three revenue positioning and national reach across all 50 states.
Market Expansion: Ongoing acquisitions and advisor recruitment expand the footprint into banks, credit unions, independent advisors, and HNW RIA channels (e.g., Ladenburg, Infinex, American Portfolios, Lincoln Wealth, CW Advisors). Consolidation under a unified platform and continued affiliations signal sustained reach growth.
Investor Backing & Capital Strength: Backing from Reverence Capital and a January 2026 refinancing of $750 million to extend maturities and lower costs indicate available capital to support strategy. Ratings commentary notes stable outlooks and improving margins tied to scale and a fee‑only shift.
At Synchrony (NYSE: SYF), we’re changing what’s possible for people and businesses every single day. From offering financing options to creating innovative tech, we help make shopping go smoothly across a variety of industries, like retail, auto, travel and home. Synchrony is one of the largest issuers of store credit cards in the United States. We help consumers pay over time...
Synchrony's Top Stability & Growth Strengths
Profitability: Earnings per share and returns improved markedly in Q3 2025, aided by better credit performance and a higher net interest margin. ROA and ROE reached elevated levels while net interest income rose year over year.
Strategic Partnerships: Recent wins and renewals with marquee brands—including the regained Walmart program and ongoing Amazon/PayPal relationships—signal durable partner trust and distribution. Commercial momentum through 2025 additions/renewals supports embedded financing reach across retail and specialty verticals.
Investor Backing & Capital Strength: Capital levels remained strong with a CET1 ratio in the mid‑13% range. The board expanded share repurchases to approximately $2.1B through mid‑2026, reflecting confidence in earnings capacity.



