Top Fintech Companies in Atlanta, GA (198)

REPAY is a full-service payment technology and processing provider that enables the expedient and secure collection of payments through any channel at any time. Our omnichannel payment platform provides direct integration with enterprise management systems and access to a suite of payment solutions, including credit/debit card processing, ACH processing, Instant Funding, IVR/phone pay, text pay, electronic bill payment and presentment...
REPAY's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show clear acceleration, with reported revenue rising strongly and organic growth remaining positive, while late‑2025 normalized trends also improved. Management’s outlook indicates continued growth through 2026.
Market Expansion: Scale and reach expanded meaningfully through the KUBRA acquisition, adding breadth across bill‑payment verticals and materially increasing overall platform activity. Distribution indicators such as software relationships and the AP supplier network also grew markedly.
Healthy Cash Flow: Cash generation is solid, highlighted by substantial free cash flow and strong conversion in the latest quarter. Adjusted profitability also improved alongside the expanding revenue base.
Mastercard powers economies and empowers people in 200+ countries and territories worldwide. Together with our customers, we’re building a resilient economy where everyone can prosper. We support a wide range of digital payments choices, making transactions secure, simple, smart and accessible. Our technology and innovation, partnerships and networks combine to deliver a unique set of products and services that help...

Mastercard's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue rose at double‑digit rates in 2025 and continued to increase at a similar pace in early 2026, supported by higher gross dollar volume, cross‑border activity, and switched transactions. The multi‑quarter trend indicates consistent top‑line momentum rather than a one‑off spike.
Profitability: Operating income outpaced revenue growth in 2025, expanding margins, while net income and EPS also advanced strongly. This points to operating leverage as volumes and higher‑yield cross‑border flows scale.
Diversified Revenue Streams: Value‑added services and solutions grew markedly faster than the core network, with security, digital authentication, analytics, and consulting cited as key contributors. This mix shift broadens growth beyond card payment fees and supports resilience.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating income has risen materially alongside growth, with the latest quarter reporting meaningful GAAP and adjusted operating profits and expanding margins. This indicates the business is scaling while improving earnings quality.
Resilient & Sustainable Growth: Gross profit is expanding at a strong, accelerating pace, with both Cash App and Square contributing and management raising full‑year outlooks. Longer‑term disclosures also highlight multi‑year compounding in gross profit per user across ecosystems.
Cost & Operational Efficiency: A leaner organizational structure and disciplined spending have driven record adjusted operating margins and improved operating leverage. Efficiency gains appear to be a second engine alongside revenue drivers.
At Capital One, we think and work like a tech company, using our digital fluency to transform everything about the customer experience. We’re bending data to our will, and turning a stodgy industry on its head. That’s reflected in our ranking as the number one business technology innovator in the U.S. in the 2016 InformationWeek Elite 100.
Capital One's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show total net revenue rising sharply—up 37% in 2025 and about 26% year over year in Q2 2026—while management described performance as reflecting solid top-line growth. Purchase volume also expanded materially, including a 27% increase in 2025 and strong gains into 2026.
Market Expansion: Scale expanded meaningfully with the May 2025 Discover acquisition, which added assets, deposits, loan portfolios, and payment-network capabilities. As of early 2026, reported assets of about $683 billion and deposits near $489 billion underscore the larger combined footprint, and external commentary anticipates further expansion.
Strong Market Position & Advantage: The company is identified as the largest U.S. credit-card issuer by outstanding balances as of year-end 2025 and one of the nation’s largest banks by deposits, with customer-satisfaction leadership among national banks. The addition of Discover’s network further reinforces a differentiated competitive position.
As the world’s largest asset manager, BlackRock partners with investors around the globe to help them (and those on whose behalf they invest) plan for life’s most important goals – like retirement, home ownership and their children’s education. Our clients range from governments, foundations and other large institutions to those investing on behalf of individuals, including firefighters, nurses, teachers and...

BlackRock's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in 2025 and accelerated further in early 2026, with adjusted operating income also rising. This points to broad-based top-line momentum beyond a single period.
Strong Market Position & Advantage: The company is characterized as the world’s largest asset manager with record-high assets under management and leading ETF scale. This scale advantage underpins continued client inflows and platform reach.
Diversified Revenue Streams: Growth is coming from multiple engines, including iShares ETFs, active strategies, private markets, and technology services such as Aladdin, alongside newer digital-asset offerings. This breadth reduces reliance on any single product line.
As a member-owned, not-for-profit financial cooperative, we are guided by the credit union philosophy of “people helping people.” Putting people over profit guides our everyday business decisions. Unlike many financial institutions, we aren’t privately owned. As a cooperative, we are owned by our members. This drives us to do right by the member, and right by each other as coworkers....
BECU's Top Stability & Growth Strengths
Market Expansion: Physical footprint has been expanding with new Neighborhood Financial Centers in 2025 and additional openings announced for 2026–2027. A proposed combination with SAFE Credit Union would extend reach into California, pending required approvals and member vote.
Investor Backing & Capital Strength: Cooperative equity increased over the latest period, and the 2025 net‑worth ratio was reported well above well‑capitalized thresholds. This strong capital position supports continued investment and resilience.
Resilient & Sustainable Growth: After a flat patch in 2025, mid‑2026 results indicate renewed balance‑sheet growth across assets, loans, and member shares. Membership also continued to rise in 2024 and 2025, reinforcing durable franchise momentum.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...
Square's Top Stability & Growth Strengths
Profitability: Square gross profit increased year over year in 2025 and again in recent quarters, with gains driven by processing, software, and financial solutions like Square Loans. Filings indicate this momentum continued into 2026, with growth excluding hardware also improving.
Strong Market Position & Advantage: Square is described as a leader in small-business POS and commerce, serving millions of sellers and processing a very large volume of payments. Industry recognition and scale suggest durable competitive positioning in its core segments.
Market Expansion: International payment volume is growing faster than the U.S., and sectors such as food and beverage led recent gains. Seller acquisition accelerated late in 2025, indicating widening reach across geographies and customer segments.
Initially built to take the pain out of peer-to-peer payments, Cash App has gone from a simple product with a single purpose to a dynamic app, bringing a better way to send, spend, invest, borrow and save to our millions of monthly active users. With a mission to redefine the world's relationship with money by making it more relatable, instantly...

Cash App's Top Stability & Growth Strengths
Profitability: Cash App gross profit has risen strongly over multiple periods, with momentum attributed to growth in Borrow, BNPL products, and the Cash App Card. Company communications indicate continued year-over-year expansion that has supported raised outlooks.
Diversified Revenue Streams: Multiple monetization pillars—consumer lending, card spend/commerce enablement, banking features, and payments—are contributing to growth, while Bitcoin-related revenue has relatively little impact on gross profit. Excluding Bitcoin, segment net revenue growth has been materially stronger, and per-active monetization has increased.
Strong Market Position & Advantage: The platform has built a very large transacting active base and ranks near the top of U.S. finance app downloads, supporting scale-driven advantages. Engagement indicators such as inflows per active and primary banking adoption have increased, signaling deepening usage.
Intuit is the global technology platform that powers prosperity for the people and communities we serve with TurboTax, Credit Karma, QuickBooks, and Mailchimp. Our teams innovate using a common architecture shared across all of our products to unlock powerful insights and deliver personalized customer experiences. Our robust data and AI capabilities are instrumental to our success as an industry leader...
Intuit's Top Stability & Growth Strengths
Strong Market Position & Advantage: TurboTax and QuickBooks are repeatedly characterized as dominant in U.S. DIY tax filing and small‑business accounting, with Mailchimp widely recognized among SMB marketing platforms. Leadership is strongest in the small‑business tier and the U.S., supported by scale across core franchises.
Strong Revenue Growth: Recent filings and earnings through the first half of FY2026 show double‑digit year‑over‑year increases at the company level and across key segments. Management has reiterated full‑year guidance pointing to continued double‑digit growth.
Diversified Revenue Streams: Company disclosures highlight sizable revenue across Consumer (TurboTax), Global Business Solutions (QuickBooks + Mailchimp), and Credit Karma, demonstrating category‑defining breadth. Strength in multiple units, including QuickBooks Online and Credit Karma, provides several growth engines even as performance varies by product.

Trimont (www.trimont.com) is a specialized global commercial real estate loan services provider and partner for lenders and investors seeking the infrastructure and capabilities needed to help them scale their business and make informed, effective decisions related to the deployment, management and administration of commercial real estate secured credit. Data-driven, collaborative and focused on commercial real estate, Trimont brings a distinctive mix...
Trimont's Top Stability & Growth Strengths
Strong Market Position & Advantage: Market standing is reinforced by top industry rankings, leadership in U.S. master and CMBS servicing, and upgraded STRONG servicer evaluations from S&P. Recognition across trade organizations and league tables indicates a defensible competitive position.
Market Expansion: Expansion into master servicing and deeper participation in CMBS/public credit followed the acquisition of Wells Fargo’s non-agency CMS business. Global reach and broader segment coverage point to a widened addressable market.
Strong Hiring & Retention: Headcount growth and Top Workplace recognition in Atlanta signal organizational scaling to support a larger portfolio. New leadership appointments and an expanded office footprint further reflect capacity-building.
.png)
Shaping the future for 135 years, NCR is the world’s enterprise technology leader for restaurants, retailers and banks. The #1 global POS software provider for retail and hospitality, and the #1 provider of multi-vendor ATM software, we create software, hardware and services that run the enterprise from back office to the front end and everything in between for our clients.
NCR Corporation's Top Stability & Growth Strengths
Strong Revenue Growth: Recent quarter performance shows revenue rising year over year to about $720M, described as a better-than-expected result. This indicates some near-term top-line momentum despite broader transition noise.
Strong Market Position & Advantage: Market position remains strong in several core niches, including a large global installed base in POS software and leadership in self-checkout by installed base. The ATM-focused business is also described as operating the largest retail-based surcharge-free network and the largest independently owned ATM network.
Cost & Operational Efficiency: Operational emphasis is shifting toward margin and cash flow improvement, with guidance pointing to higher adjusted EBITDA and EPS even while reported revenue dips due to a hardware/ODM transition. This suggests execution is prioritizing efficiency and mix improvement over headline growth in the near term.
Corserv provides turn-key credit card issuing programs, and APIs to payment issuing and processing services that are used by Banks, Fintechs, and eCommerce companies to create innovative payment, commerce, and finance programs. Corserv's credit credit card issuing and processing programs provides the technology, scale, and expertise for financial institutions of all sizes to profitably offer credit card products to consumer,...
Invesco is an independent investment management firm delivering an investment experience designed to help people get more out of life.
Invesco's Top Stability & Growth Strengths
Resilient & Sustainable Growth: AUM reached record levels in 2025 and continued to rise into early 2026 on sustained net long‑term inflows beyond market appreciation. Momentum in ETFs/Index, global liquidity, and the China JV supported organic growth alongside favorable markets.
Strong Market Position & Advantage: Invesco is a top‑tier global manager and the No. 4 U.S. ETF issuer, anchored by the QQQ franchise among the largest ETFs globally. The late‑2025 conversion of QQQ to an open‑end ETF enhanced ongoing fund‑level revenues from this crown‑jewel product.
Cost & Operational Efficiency: Adjusted operating margins improved in 2025 with positive operating leverage, aided by cost discipline and a leaner headcount. A mix shift toward scalable ETFs/Index and liquidity products further supports efficiency.
Principal Financial Group provides retirement savings, investment, and insurance products and services worldwide.
Principal Financial Group's Top Stability & Growth Strengths
Profitability: Non‑GAAP operating EPS rose 11% in 2024 and accelerated at double‑digit rates in 2Q–3Q25, with segment margin expansion supporting earnings momentum.
Investor Backing & Capital Strength: Management raised dividends multiple times in 2025 and executed ongoing buybacks consistent with annual capital deployment guidance, indicating balance‑sheet flexibility and disciplined return of capital.
Strong Market Position & Advantage: The company is a leader in SMB/pooled retirement solutions, plan‑sponsor experience, and real‑estate investing while remaining a credible scaled competitor across broader retirement and asset‑management markets.
Voya Financial, Inc. (NYSE: VOYA), provides health, wealth and investment solutions that enable its approximately 14.8 million individual, workplace and institutional clients to achieve their financial wellness goals with confidence. With a vision to be America’s Retirement Company®, Voya’s products, solutions and digital capabilities help create a better financial future for all. Voya is a Fortune 500 company that had...
Voya Financial's Top Stability & Growth Strengths
Strong Market Position & Advantage: Workplace retirement recordkeeping is positioned as a top-tier niche, with large participant scale and expanded presence after the OneAmerica retirement acquisition.
Profitability: Earnings strength is indicated by more than $1B in pre-tax adjusted operating earnings and a higher adjusted operating ROE, alongside a rebound in Employee Benefits profitability.
Healthy Cash Flow: Cash generation is described as strong, with excess capital generation exceeding targets and ongoing share repurchases supported by high free cash flow conversion.
Sage Intacct is 100% invested in meeting the needs of financial professionals, 100% focused on customer success, and 100% committed to the cloud. That’s who we are, and always will be. Thousands of organizations rely on Sage Intacct’s best-in-class cloud ERP software, which is part of the Sage Business Cloud, to deliver the efficiencies and insight
At Fifth Third Bank, we are always listening to new ideas so that we can strengthen our commitment to you and the communities we serve.
Fifth Third Bank's Top Stability & Growth Strengths
Market Expansion: Feedback suggests the bank is expanding into high‑growth regions, planning 200+ new Southeast branches by 2028 and building out Texas following the 2026 Comerica merger. The combination extended its presence to 17 of the 20 fastest‑growing large markets with a multi‑year deposit growth target of $15–$20B.
Strong Revenue Growth: Feedback suggests top‑line momentum is solid, including record net interest income in 2025 and a 33% year‑over‑year revenue increase in Q1 2026 with fee revenues up materially. Net interest margin and new deposits also improved sequentially after the merger closed.
Diversified Revenue Streams: Feedback suggests treasury, payments, and wealth services are meaningful contributors, with fee lines growing and supported by targeted acquisitions such as DTS Connex and Rize. Wealth and asset management reported sustained growth, and commercial payments activity increased.

We reimagine everyday business challenges through advanced analytics, technology-enabled and market-driven solutions built to solve some of industries’ biggest obstacles to growth. Inmar Intelligence’s customer-centric approach is evident through our success helping companies dynamically engage audiences, build brand loyalty, create efficiencies and drive profitable growth. We help leading Fortune 500 companies and emerging brands stay relevant and propel growth while providing...
Inmar Intelligence's Top Stability & Growth Strengths
Strong Market Position & Advantage: Evidence across digital incentives/coupon settlement, grocery retail media enablement, and healthcare compliance shows leadership in core niches and a credible role as a retailer tech/services partner. Historical analyst recognition and marquee retailer selections reinforce category strength where the company is most focused.
Strategic Partnerships: Recent partnerships with Ahold Delhaize USA, RSA America, Northeast Grocery, bp/Axonet, and national GPOs alongside a U.S. HHS contract point to durable external anchors across retail and healthcare. These alliances expand reach, validate credibility, and underpin momentum in the refocused core businesses.
Market Expansion: Expansion beyond grocery into convenience/gas and activations across additional retailer networks indicate widening channel coverage and new use cases. New logos and programs (e.g., sports and entertainment) further demonstrate extension into adjacent audiences and formats.
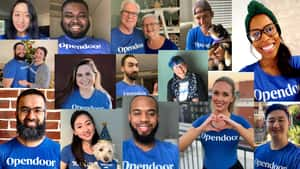
Founded in 2014, Opendoor’s mission is to empower everyone with the freedom to move. We believe the traditional real estate process is broken and confusing. It often comes with unexpected costs, the added burden of coordinating multiple third parties and the uncertainty of a transaction falling through. Our goal is simple: build a digital, end-to-end customer experience that makes buying...
Opendoor's Top Stability & Growth Strengths
Cost & Operational Efficiency: Q2 2026 showed healthier unit economics, with gross margin at 9.7% (up from 8.2% a year earlier) and contribution margin improving alongside lower aged inventory and faster resale velocity. Operations expense per acquisition close also declined materially, reinforcing operating leverage as volumes rebuild.
Investor Backing & Capital Strength: On August 13, 2026, the company announced its first share buyback (reducing shares outstanding by about 5%) and raised roughly $440M of 0%‑coupon growth capital. This added capacity is positioned to fund continued acquisition growth.
Market Expansion: The platform expanded coverage to nearly all homeowners across the contiguous U.S. by integrating ~200 MLS datasets and 1,000+ data pipelines. This broader reach is described as generating thousands of incremental qualified leads per week without additional marketing spend.
We help people achieve a lifetime of financial security and to enjoy a meaningful life – both now and in retirement. Not only do we offer products and services to achieve this but we also focus on financial wellbeing. When we talk about financial wellbeing this is how you feel about the control you have over your financial future –...