

Top Software Companies in San Diego, CA (676)
CSC is a global leader in providing business, legal, tax, and digital brand services to companies around the world. With more than 8,000 employees, CSC operates in more than 140 jurisdictions, delivering solutions that help businesses thrive. We pride ourselves on our client-focused approach, market-leading expertise, and unmatched global reach.
CSC's Top Stability & Growth Strengths
Strong Market Position & Advantage: Customer base is described as including a very large share of major global enterprises across Fortune-ranked companies, top brands, and leading private equity firms, indicating entrenched enterprise reach. This positioning underscores a strong competitive footing across multiple service lines.
Market Expansion: Operations have scaled to capabilities in more than 140 jurisdictions, aided by the approximately $3 billion Intertrust acquisition and its full integration in 2024. Continued investment and activity are highlighted across Europe, the Americas, Asia-Pacific, and the Middle East.
Product Line Growth: The company has expanded from incorporation services into corporate/legal compliance, fund administration, capital markets, tax, digital brand protection, domain services, and global subsidiary management. Corporate and Legal Solutions is described as the largest revenue-generating unit with a sizable workforce.

At Spectrum, our Product & Technology teams build the platforms and tools that power seamless connectivity and entertainment across Internet, WiFi, Video, Mobile and Voice. Supporting more than 500 million devices, we’re transforming the next era of connected experiences with some of the fastest, most reliable and advanced services in the nation. It’s an unmatched environment for designers, architects, engineers,...

Spectrum's Top Stability & Growth Strengths
Product Line Growth: Mobile services are expanding rapidly, with strong growth in Spectrum Mobile lines and mobile-service revenue highlighted across recent periods.
Market Expansion: The physical network footprint continues to widen through additional passings and rural buildouts, supported by substantial capital investment and line extensions.
Strong Hiring & Retention: Hiring activity is active across corporate, field operations, sales, and technology, and the company points to workforce development initiatives and hiring events as ongoing priorities.
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased 10% in 2025 and 9% in H1 2026, with leadership upgrading 2026 guidance to 8–10% sales growth. Growth was reported across all major sectors.
Profitability: Underlying EBIT rose 12% in 2025 and 11% in H1 2026, alongside an improved return on sales. This points to stronger margins in addition to top-line expansion.
Resilient & Sustainable Growth: A record order backlog of roughly £83.6–84.0 billion and multi‑year contracts provide substantial future revenue visibility. The 2026 outlook also signals continued expansion.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Strong Revenue Growth: Optum’s consolidated revenue expanded from $253.0B in 2024 to $270.6B in 2025, indicating continued top-line growth. Multi‑year reporting also highlights ongoing increases at the consolidated level even as segment performance diverges.
Diversified Revenue Streams: Performance is spread across three businesses, with Optum Rx delivering substantial gains, Optum Insight growing modestly, and Optum Health contracting. This mix shows pharmacy and technology services helping sustain overall scale despite softness in care delivery.
Cost & Operational Efficiency: Operating performance improved in 2026 as Optum’s operating income rose year over year to about $4B in Q2 alongside reported gains in technology and clinical operations. UnitedHealth also raised its 2026 adjusted EPS outlook, signaling confidence in execution.
STR makes the world a safer place by developing technology and applying it to solve emerging national security challenges.
STR's Top Stability & Growth Strengths
Strong Revenue Growth: Subscription revenue is described as growing at a double‑digit year‑over‑year pace as of late 2023, signaling solid momentum in the core recurring model.
Customer Loyalty & Retention: Renewal rates are reported as extremely high, indicating sticky relationships and a durable subscription base.
Market Expansion: The underlying hotel‑data network has expanded materially to a larger global sample across nearly 200 countries, pointing to broader reach and scale.
Schrödinger is a leading provider of advanced molecular simulations and enterprise software solutions and services for pharmaceutical, biotechnology, and materials science research. The predictive power of Schrödinger's software allows scientists to accelerate their research and development, reduce research costs, and make novel discoveries.
Schrödinger, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate total revenue increased year over year in 2025 and continued to rise in the latest reported quarter. Guidance and quarterly updates point to ongoing top-line expansion even as mix shifts occur.
Resilient & Sustainable Growth: Underlying annual contract value expanded and accelerated in 2026, with management indicating continued growth despite the transition to hosted licensing. This suggests the core subscription base is strengthening even when reported revenue timing varies.
Diversified Revenue Streams: Growth is visible in both the software business and the milestone-driven drug discovery segment. The latter stepped up meaningfully in recent periods, complementing steady software momentum.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding rapidly, with recent quarters showing accelerated year-over-year gains in both total and subscription revenue. Multi-year growth at a high double-digit pace is also evident in the latest annual results.
Resilient & Sustainable Growth: Contracted revenue indicators appear robust, with total RPO at $29.0B and current RPO at $13.2B in Q2 2026. Management also raised its full-year 2026 subscription outlook, signaling confidence in continued expansion.
Innovation-Driven Growth: Newer AI offerings are gaining commercial traction, with ServiceNow AI surpassing $1 billion in annual contract value and agentic deployments scaling quickly. Large-deal activity and the count of very large customers also increased, indicating product-led expansion.
Licensing education has a reputation for being dry content, clunky, and courses designed to check a box rather than actually teach anything. We decided that was a problem worth solving. Our courses are mobile-first, fully accredited, and built around one obsessive question: what’s the most effective, engaging way to get someone to actually learn this? We’re proud that our students...
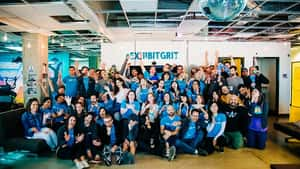
Aceable's Top Stability & Growth Strengths
Market Expansion: Coverage has broadened across 40+ states with continued entry into new geographies, including an Illinois foothold via the Real Estate Institute acquisition and insurance launches in Illinois and California. Real-estate partner materials list many major states and ongoing plans to expand to additional states.
Product Line Growth: Offerings have extended beyond driver’s ed into real estate, insurance, and mortgage, with new launches such as a free e‑bike/e‑scooter safety course and career-development content for newly licensed agents. The company highlights operation across four verticals, with continued additions signaled by recent releases.
Strong Revenue Growth: Real‑estate education revenue is described as growing at a 38% CAGR over five years with EBITDA tripling, indicating strong momentum in a major business line. Company‑wide revenue is not publicly quantified, but this segment trend supports a broader growth narrative.
Clear Street’s mission is to give every sophisticated investor access to every asset, in every market, through a unified platform built for speed, transparency and scale. We give our clients the technology, tools, and service once reserved for the largest institutions, rebuilt with modern infrastructure. Our single, cloud-native, end-to-end capital markets platform powers investor growth today and is transforming how they...

Clear Street's Top Stability & Growth Strengths
Strong Revenue Growth: Disclosures indicate revenue grew 137% in 2024 and 160% in the first nine months of 2025, reaching $783.7M for that period. Gains in average daily client balances and trading volume further underscore broad-based top-line acceleration.
Profitability: Net income turned meaningfully positive, with $89.1M in 2024 and $157.2M in the first nine months of 2025. This profitability alongside rapid scaling supports financial stability.
Market Expansion: The company expanded beyond U.S. prime brokerage into UK and European equities (e.g., LSE clearing membership) and pursued APAC access via regulatory approvals and acquisitions. It also broadened offerings across futures, fixed income, options, digital assets, and investment banking.

Vannevar combines Silicon Valley innovation with former special operators to build AI for real-world national security outcomes. Since our founding in 2019, Vannevar has deployed its technology across 125 missions, safeguarding our service members and improving our country's deterrence. We believe our military service members and intelligence officers deserve access to the best technology American innovation can offer, and we are...

Vannevar's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as rising from about $3.5M in 2021 to roughly $80M in 2024, with annual contract value also increasing substantially. Feedback suggests this momentum reflects rapid scaling of contracted business.
Profitability: The company is reported to have become profitable within three years and to have maintained profitability thereafter. This points to efficient scaling rather than reliance solely on external financing.
Market Expansion: Contracting progressed from prototypes to a DIU production vehicle with a $99M ceiling, followed by additional Air Force and OSD awards through 2025–26. The stated footprint grew to about 125 deployments across every service branch and combatant command.
 copy.jpg)
At 8am, our vision is to power a world where professionals thrive. We start every day on a mission to empower professionals with the most trusted, innovative technology to deliver world-class outcomes for their clients and exceptional financial results for their business. They count on our purpose-built solutions to simplify operations, ensure compliance, and fuel profitable growth, so they can...

8am (Formerly AffiniPay)'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is portrayed as rising consistently, with multi-year acceleration alongside increases in recurring revenue and total payments processed. Company communications across 2024–2026 emphasize continued momentum rather than stagnation.
Product Line Growth: The portfolio expanded beyond payments into practice management, financial tools, and AI capabilities, unifying brands such as LawPay, MyCase, CasePeer, DocketWise, and CPACharge. This broader offering is presented as fueling adoption and deeper engagement among professionals.
Investor Backing & Capital Strength: Major private-equity investors partnered with the company in 2024 to support its next phase of expansion. This backing is framed as enabling acquisitions, platform development, and scaling initiatives.
At Shield AI, you won't wait years to see your work reach the field. You'll build hardware and software that operates in the real world right now, in the hands of the people who depend on it. Hivemind, our AI pilot, has been flying since 2018. It has flown more than 30 platforms, including an F-16, and it now sits under...
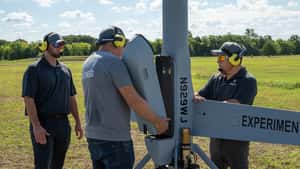
Shield AI's Top Stability & Growth Strengths
Strong Revenue Growth: Company reports indicate FY2026 orders and revenue doubled year over year. Management projections point to revenue well above $500 million for 2026, signaling rapid topline acceleration.
Investor Backing & Capital Strength: Recent financings include a $1.5 billion Series G and $500 million in preferred equity at a $12.7 billion valuation. These steps indicate substantial capital access and confidence from major financial backers.
Market Expansion: Program momentum includes a U.S. Air Force production award for CCA autonomy and a U.S. Navy ISR vehicle with a high task‑order ceiling. International traction spans India, Greece, Poland, and Taiwan, alongside plans for regional offices.

Revolutionize How Your Business Works. Apple IT Support for the Modern World. Built by Apple employees, Interlaced is the industry’s most operationally mature provider of Apple IT services. Access real-time support from an Apple-certified technical consultant with the simple click of a button. Our team of certified Apple IT Consultants, Jamf Pros and IT Strategists use the industry’s leading support tools to...
At Pacific Office Automation (POA), we take pride in being a privately held office technology and managed services provider headquartered in Beaverton, Oregon. Since our founding in 1976 by Terry Newsom, we have grown from a small photocopier business into the largest independent office equipment dealer in the United States. Today, we generate approximately $491 million in annual revenue and...
Pacific Office Automation's Top Stability & Growth Strengths
Strong Revenue Growth: POA reported finishing 2025 above $507 million in revenue and cites 49 consecutive years of annual growth, with inclusion on regional fastest-growing lists reinforcing momentum.
Strong Market Position & Advantage: Multiple industry and OEM references describe POA as the largest independent U.S. office‑equipment dealer and a top-tier channel partner, with repeated Elite Dealer recognitions and OEM awards signaling standing.
Market Expansion: The company announced plans to enter four new cities in 2026 and executed acquisitions in April 2026 (Western Business Products and MKCnext), broadening its Western U.S. footprint and adding wide‑format capabilities.
For over 240 years, Takeda’s propensity to evolve has driven the next generation of innovation, and as a future-focused organization, we’re continuing to drive forward with endurance in our steadfast pursuit to achieve the best outcomes for our patients in a rapidly changing world. We have been preparing for this period of value creation by investing in data, digital and...
Takeda's Top Stability & Growth Strengths
Strong Market Position & Advantage: Takeda is consistently placed among the global top 15–20 by revenue and is a clear category leader in GI/IBD, plasma-derived therapies, and dengue vaccines with broad international authorizations and WHO support. Subcutaneous ENTYVIO and new oncology approvals like FRUZAQLA broaden real‑world use and extend reach.
Profitability: Reported FY2025 operating profit rose 19.3% year over year and EPS nearly doubled despite a slight revenue decline, supported by lower amortization and restructuring expense. Core profitability remained broadly stable as Growth & Launch Products expanded their share.
Future-Ready Strategy: Management is investing through FY2026 to convert a late‑stage pipeline (e.g., oveporexton, rusfertide, zasocitinib) into multiple launches, with Growth & Launch Products prioritized as near‑term engines. A multi‑year transformation and efficiency program targeting significant savings by FY2028 is intended to fund launches and strengthen competitiveness.

We create technology that simplifies life for employees and helps our clients succeed.

Paycom's Top Stability & Growth Strengths
Profitability: Recent results indicate growing revenue alongside strong margins and cash generation, with management emphasizing disciplined spending and operating leverage. This financial profile points to durable earnings power that can support reinvestment and shareholder returns.
Innovation-Driven Growth: Ongoing launches such as employee-driven payroll and an AI engine are highlighted as improving accuracy, reducing manual effort, and increasing adoption and retention. Recognition for innovation and expanding usage of these tools suggests product momentum that supports long-term growth.
Market Expansion: The company has extended offerings into additional countries, added sales offices, and is moving upmarket with larger customers. These steps increase its addressable market and create multiple avenues for future revenue.

We are GDIT. The people supporting some of the most complex government, defense, and intelligence projects across the country. We deliver. Bringing the expertise needed to understand and advance critical missions. We transform. Shifting the ways clients invest in, integrate, and innovate technology solutions. We ensure today is safe and tomorrow is smarter. We are there. On the ground, beside...
General Dynamics Information Technology's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Forward visibility looks durable due to a $100+ billion companywide backlog and repeated references to multi‑year contract wins that extend revenue coverage into 2026. The outlook frames demand as supported by defense and federal IT modernization priorities, suggesting the business can absorb near-term volatility.
Strong Market Position & Advantage: GDIT is positioned as a top-tier federal IT prime, reinforced by recurring placement in major federal contractor rankings and a steady cadence of marquee awards across DoD, intel, and civilian agencies. Its scale inside General Dynamics and ability to deliver mission-critical programs (e.g., enterprise IT modernization and large federal systems) signal competitive advantage in accreditation-heavy government work.
Diversified Revenue Streams: Revenue support is described as coming from multiple General Dynamics segments (Aerospace, Marine, Combat Systems, Technologies) alongside GDIT’s mix of defense, intelligence, health, and civilian programs. This multi-segment and multi-mission exposure reduces dependence on any single program area and supports stability through procurement cycles.
Wrike, Inc. is a fast-growing privately held corporation that gets thousands of new customers on board year after year and shows stable annual growth. Wrike’s diversified, international customer base includes well-known brands, such as PayPal, Hootsuite, Hubspot, Citrix, and many others.

Workiz is the the only field service management and communication platform for small-medium on-demand businesses in North America
Workiz's Top Stability & Growth Strengths
Strong Revenue Growth: Independent growth lists and multi‑year placements indicate sustained expansion, supported by ongoing product releases and signals of a broad user footprint. As a private company, precise revenue isn’t disclosed, but multiple third‑party indicators point to continued momentum through mid‑2026.
Product Line Growth: Recent launches in the “Genius” suite (e.g., AI answering/dispatch and marketing) expand the platform’s capabilities and move it toward an autonomous growth engine vision. Differentiation around built‑in communications and AI is consistently highlighted as a core strength.
Strategic Partnerships: Collaborations in HVAC and ecosystem integrations (e.g., with major brands and lead channels) extend reach and reinforce relevance in target trades. These moves suggest deliberate expansion of distribution and value through partners.

At Housecall Pro, we're committed to making the everyday lives of home services professionals better by providing solutions that support their paths to success. Our core SaaS software platform runs all aspects of a home services business, including scheduling, dispatching, job management, invoicing, payment processing, and marketing. Housecall Pro will be there to help these businesses that keep America’s homes...

Housecall Pro's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent roundups and buyer shortlists frequently feature the company among top field service tools for home services, and G2 category pages identify it as a Leader. Presence on Capterra’s 2026 Shortlist reinforces sustained visibility with active buyers.
Investor Backing & Capital Strength: A $125M financing in 2022 from Permira and Vista is cited as enabling expansion, with subsequent hiring and brand activity in 2026 indicating continued go‑to‑market investment. Stripe case materials also point to meaningful engagement with embedded financial products.
Innovation-Driven Growth: Regular releases emphasizing automation and AI, along with publication of industry benchmarks and AI‑usage reports, indicate ongoing product and thought‑leadership investment. Mainstream business media citations for trades‑tech trends further support an innovation posture.



