


The Structured Finance Analytics Team is composed of a Quant team, a Data Analytics team, a Solutions team, and a Cashflow Modelling team. The Quant team has been growing over the last few years, comprising a global team of a dozen people today, located in the US and in Europe. The Quant team builds models and analytical tools to help rating analysts assess the credit risk of a transaction.
The Role
As a Quant Analyst you will execute proprietary research for building various types of credit rating models, such as factor models and predictive models covering asset classes of ABS, CMBS, RMBS and Structured Credit. The Quant team will collaborate with members from the Credit Ratings, Credit Practices, Methodology Review Function, Data Engendering and Technology teams to create class leading models that are as innovative as understandable in the marketplace.
Responsibilities
- Support rating methodology development and participate in the implementation of quantitative models such as credit predictive models.
- Develop, maintain and enhance proprietary Python and C++ libraries related to model building.
- Leverage structured and unstructured datasets to build new quantitative frameworks to assist analysts in informed decision making.
- Assisting development of analytics-based solutions, taking ownership of the design and development of solutions to scale out information ingestion, storage, computation (training/inference), validation.
- Participate in analyst conversations to understand ongoing analyst issues and merging market trend.
- Contribute to the development and writing of quantitative research papers supporting model development, methodology enhancements, and analytical innovation.
Requirements
- Bachelor’s degree; Master’s degree or PhD preferred in Mathematics, Engineering, Physics, Economics, Finance, Statistics, or a related quantitative discipline.
- Minimum 5 years of experience within a rating agency.
- Minimum 5 years of hands-on experience in RMBS/ABS/CLO defaults and losses modelling.
- Coding skills in a major programming language Python or C++ and experience writing research articles and/or technical documentation using LaTeX.
- Strong knowledge of statistical modelling, probability theory, numerical analysis and stochastic calculus.
- Strong knowledge of numerical methods (numerical integration, Monte Carlo simulation, root-finding and general optimisation techniques).
- Excellent understanding of securitisation products.
- Understanding both business and technical requirements, and the ability to serve as a conduit between technical and non-technical departments.
Nice to have
- CQF or postgraduate degree in quantitative finance, economics, or STEM fields is highly desired.
- Exposure to main Python packages for numerical computing and Machine Learning / Data Science (NumPy, Pandas, Scikit-Learn and SciPy).
- Ability to perform rigorous data analysis on large datasets.
- Experience developing cloud applications (AWS preferably).
If you receive and accept an offer from us, we require that personal and any related investments be disclosed confidentially to our Compliance team. These investments will be reviewed to ensure they meet Code of Ethics requirements. If any conflicts of interest are identified, then you will be required to liquidate those holdings immediately. In addition, dependent on your department and location of work certain employee accounts must be held with an approved broker (for example all, U.S. employee accounts). If this applies and your account(s) are not with an approved broker, you will be required to move your holdings to an approved broker.
Base Salary Compensation RangeEUR 69,000.00-104,466.66Bonus Target:
20% AnnualWe expect the compensation and target bonus for this role to fall within the stated range. The specific compensation offered will depend on the candidate’s qualifications, experience, and other job-related factors.
Morningstar's hybrid work environment gives you the opportunity to collaborate in-person each week as we've found that we're at our best when we're purposely together on a regular basis. In most of our locations, our hybrid work model is four days in-office each week. A range of other benefits are also available to enhance flexibility as needs change. No matter where you are, you'll have tools and resources to engage meaningfully with your global colleagues.
R09_DBRSRtgsGmbHGermany DBRS Ratings GmbH - Germany Legal EntitySkills Required
- Bachelor's degree in Mathematics, Engineering, Physics, Economics, Finance, Statistics, or a related quantitative discipline
- Minimum 5 years of experience within a rating agency
- Minimum 5 years of hands-on experience in RMBS, ABS, or CLO defaults and losses modeling
- Programming experience in Python or C++
- Experience writing research articles or technical documentation using LaTeX
- Strong knowledge of statistical modeling, probability theory, numerical analysis, and stochastic calculus
- Strong knowledge of numerical integration, Monte Carlo simulation, root-finding, and optimization techniques
- Excellent understanding of securitization products
- Ability to understand business and technical requirements and serve as a liaison between technical and non-technical departments
- Master's degree or PhD in a quantitative discipline
- CQF or postgraduate degree in quantitative finance, economics, or a STEM field
- Experience with NumPy, Pandas, Scikit-Learn, and SciPy
- Ability to perform rigorous data analysis on large datasets
- Experience developing cloud applications, preferably using AWS
What the Team is Saying


Morningstar Compensation & Benefits Highlights
-
Leave & Time Off Breadth — Policies include a paid sabbatical every four years and flexible PTO covering vacation, sick, and personal days, alongside paid volunteer time. Feedback suggests these features create meaningful flexibility and rest opportunities beyond standard leave plans.
-
Parental & Family Support — A global minimum of 16 weeks paid parental leave for primary caregivers (up to 8 weeks for secondary) and at least six weeks of paid caregiving leave are publicly stated, with adoption assistance also available. These provisions indicate robust support for families during key life events.
-
Retirement Support — U.S. materials document a 401(k) match of $0.75 per $1 up to 7% of pay and no‑cost access to Morningstar retirement tools. This combination strengthens long‑term savings and planning for employees.
Morningstar Insights

What We Do
We are a global investment research and financial data company with 40-plus offices across North America, Europe, Australia, and Asia. Our products and services are used daily by individual investors, financial advisors, asset managers, retirement plan providers, and institutional investors. We provide data, research, and analysis across managed investment products, publicly listed companies, private capital markets, debt securities, and real-time global market data. The financial system can have real barriers—hidden information, friction that can slow decisions, and forces that can limit transparency and access. We work to remove them, bringing independent research, connected data, and investor-first tools to a system that needs more clarity. The people doing this work span research, technology, design, product, sales, and functional areas. We build many of our products in-house, so the work can connect directly to the tools investors use to make real financial decisions.
Why Work With Us
Morningstar’s missing is to empower investor success. We can only do that if our people feel empowered. That means finding people who think independently, bring a wide range of backgrounds with analytical rigor and genuine intellectual curiosity to the work.
Gallery
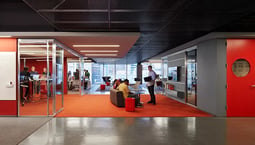
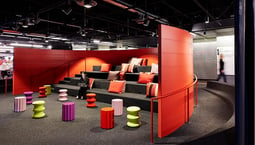
Morningstar Teams
Morningstar Offices
Hybrid Workspace
Employees engage in a combination of remote and on-site work.
Across most of our offices globally, employees work four days a week in the office and one day from home. We recognize that life doesn't always fit a fixed schedule and offer programs that can help provided increased workplace flexibility.


