

Top Software Companies (10,000+)
It’s an exciting time to be a Teragonian! Come help us transform the Private Equity industry and drive AI innovation while taking on new challenges and career growth opportunity. Teragonia provides an AI-based Value Orchestration platform for private equity backed mid-market operators, helping them transform fragmented operational data into an execution-focused view of business performance. With Teragonia, mid-market leaders align their...
Teragonia's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported as more than tripled in 2025, with annual recurring subscription and service revenue increasing by over 220%. Growth is attributed to new and expanding relationships with private equity sponsors and their portfolio companies.
Market Expansion: Office openings and relocations across Chicago, Dallas, New York, and Toronto, plus expanded sponsor footprint and portfolio reach, indicate widening geographic and commercial coverage. The company cites doubling sponsor partnerships and reach into a network representing about $400B AUM.
Strong Hiring & Retention: Headcount is estimated to have risen sharply over 2023–2026, and multiple executive appointments (e.g., EVPs for Finance & Corporate Development and for Technology & Operations) were made to support scaling. Added locations and planned team growth in hubs like Chicago and New York further signal ongoing talent expansion.
KPA solutions help clients identify, remedy, and prevent workplace safety and compliance problems across their entire enterprise. The combination of KPA’s easy-to-use software platforms, consulting services, and award-winning training content helps organizations minimize risk so they can focus on what’s important—their core business. For nearly 40 years, KPA has helped 10,000+ clients achieve regulatory compliance, protect their business, and keep...

KPA's Top Stability & Growth Strengths
Strong Market Position & Advantage: KPA is described as serving more than 15,000 businesses and cites relationships with 40 of the top 50 U.S. dealer groups, indicating deep penetration in its core automotive vertical. Its substantial customer footprint is repeatedly tied to a record year and ongoing expansion efforts.
Product Line Growth: The company reports an expanded product portfolio, including AI-powered compliance tools and enhancements like an updated Vera Suite dashboard. Announcements across 2025–2026 frame these launches as fueling accelerating innovation and growth.
Future-Ready Strategy: A 2026 reorganization refocused KPA on automotive, with leadership changes positioned to enable faster product development and deeper specialization. Continued partnerships and capability investments are presented as building for future growth.
Founded in 2020 by George Sivulka and backed by Peter Thiel and Andreessen Horowitz, Hebbia powers investment decisions for BlackRock, KKR, Carlyle, Centerview, and 40% of the world’s largest asset managers. Our flagship product, Matrix, delivers industry-leading accuracy, speed, and transparency in AI-driven analysis. It is trusted to help manage over $15 trillion in assets globally. We deliver the intelligence that...

Hebbia's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue momentum is described as rapid, with the company citing 15× growth over 18 months and coverage noting roughly $13M ARR in mid-2024. Independent estimates indicate ARR scaling into the tens of millions through 2025–2026, suggesting continued top-line expansion despite the absence of audited figures.
Investor Backing & Capital Strength: A sizable $130M Series B in 2024 led by Andreessen Horowitz, bringing total funding to roughly $161M alongside a reported ~$700M valuation, signals strong capital support. This investor base and funding depth provide capacity to invest in product and go-to-market.
Market Expansion: Geographic and product scope have broadened, including expansion into the UK and Europe and additions such as agents, research capabilities, and financial-data integrations. Company-reported activity—hundreds of thousands of daily prompts, billions of pages processed, and 1,000+ use cases across finance, legal, banking, and corporate finance—points to widening reach.
Over the last 15 years, we’ve grown from a startup to a market-leading organization with over 150 team members, and we’ve created an award-winning culture that makes this company an amazing place to work. We've been ranked on multiple best places to work lists including the 2026 BuiltIn Chicago rankings.

Hireology's Top Stability & Growth Strengths
Innovation-Driven Growth: Product development is described as continuously expanding — AI recruiting (e.g., Beaker), an Action Center, advanced analytics/insights, and an integrations marketplace — signaling innovation as a growth lever. These capabilities are presented as helping distributed businesses streamline hiring and deepen platform use.
Strategic Partnerships: Partnerships with major automotive OEM programs (e.g., Ford and GM dealerships) and ecosystem integrations (e.g., Indeed, ADP, UKG) are highlighted as extending distribution and customer reach. These ties reinforce go-to-market channels within core verticals.
Market Expansion: Expansion beyond automotive into healthcare and hospitality, plus the EmployUs acquisition, is noted alongside growth in users and substantial platform throughput. Company updates also indicate customers are broadening usage across sourcing, hiring, and onboarding.
.png)
Worth is the AI-powered platform that consolidates onboarding, underwriting, and risk monitoring for fintechs, lenders, payment processors, and financial institutions. Founded in 2023, we built Worth to replace slow, manual underwriting with a single system that verifies, scores, and monitors small and medium-sized businesses (SMBs) in real time. At the center of the platform is Crosswalking Technology. Our proprietary AI/ML models...

Worth's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raises include a $25M round in 2025 and a $30M Series A in 2026 led by Fulcrum Equity Partners with participation from Amex Ventures and TTV Capital. These milestones indicate resources to scale and reinforce confidence in the company’s trajectory.
Market Expansion: Operations and customer deployments have broadened, with 50+ enterprise customers in production across 200+ countries and an Orlando expansion adding 30 high-impact jobs. Third-party regional reporting characterizes the move as supporting a growing workforce and technology offerings.
Product Line Growth: The platform has expanded from core data matching into broader onboarding and underwriting capabilities, including Decision Intelligence, KYB/KYC, and continuous monitoring. Company materials also point to a larger SMB data footprint, increasing from roughly 242M+ to 350M+ profiles and more data points per entity.
Movable Ink personalizes every customer engagement through automation and artificial intelligence. The world’s most innovative brands rely on Movable Ink to maximize revenue, simplify workflow and achieve the optimal customer experience. Headquartered in New York City with 600 employees, Movable Ink serves its global client base with operations throughout North America, Central America, Europe, and Australia.
Movable Ink's Top Stability & Growth Strengths
Innovation-Driven Growth: Product announcements highlight expansion of the Da Vinci AI platform into new channels and the launch of Programmatic CRM/agentic capabilities, indicating an active cadence of AI-led features. These moves extend the company beyond its historical email-personalization focus into broader omnichannel decisioning.
Market Expansion: The company expanded Da Vinci into Europe and reported winning more than 100 new enterprise customers in the year prior to mid-2025. These signals point to increased geographic reach and deeper penetration in enterprise segments.
Investor Backing & Capital Strength: Symphony Technology Group agreed to acquire the company in June 2025 and explicitly referenced its growth and 100+ new enterprise wins as part of the rationale. This transaction represents significant institutional backing aligned to the company’s next phase of growth.
PagerDuty, Inc. (NYSE:PD) is a global leader in digital operations management, enabling customers to achieve operational efficiency at scale with the PagerDuty Operations Cloud. The PagerDuty Operations Cloud combines AIOps, Automation, Customer Service Operations and Incident Management with a powerful generative AI assistant to create a flexible, resilient and scalable platform to increase innovation velocity, grow revenue, reduce cost, and...

PagerDuty's Top Stability & Growth Strengths
Profitability: Feedback suggests GAAP operating income turned positive in FY2026 and profitability has continued across recent quarters, indicating stronger earnings discipline.
Healthy Cash Flow: Feedback suggests free cash flow reached roughly $100M+ in FY2026 and remained solid in subsequent quarters, signaling improved cash generation.
Cost & Operational Efficiency: Feedback suggests margin expansion and restructuring efforts have driven better operating efficiency even as top-line growth slowed.
MFour turns consumer behavior into a competitive advantage. We operate the largest opt-in, first-party consumer panel in the U.S., tracking 4B+ monthly signals across location, apps, web, receipts, and AI conversations. Our platform, powered by DANI™, delivers instant insights to the world's biggest brands, from Google to Walmart to Disney. We're building the future of market research, and we're just...
MFour Data Research's Top Stability & Growth Strengths
Product Line Growth: MFour expanded beyond mobile surveys into connected first‑party behavioral data and launched offerings such as OmniTraffic Digital Ads, ChatGPT conversation data, OOH attribution, DANI, and the MFour Studio platform. This demonstrates a broader commercial surface area and sustained product investment.
Investor Backing & Capital Strength: Semrush made a strategic investment in July 2024 and took a board role. This outside capital and governance involvement signal confidence in MFour’s trajectory.
Innovation-Driven Growth: The company is scaling AI-enabled capabilities and datasets, including rapid growth in ChatGPT conversation data, while linking app, web, location, purchase, and survey signals in one platform. These moves indicate a push to modernize around validated first‑party data and AI.
STR makes the world a safer place by developing technology and applying it to solve emerging national security challenges.
STR's Top Stability & Growth Strengths
Strong Revenue Growth: Subscription revenue is described as growing at a double‑digit year‑over‑year pace as of late 2023, signaling solid momentum in the core recurring model.
Customer Loyalty & Retention: Renewal rates are reported as extremely high, indicating sticky relationships and a durable subscription base.
Market Expansion: The underlying hotel‑data network has expanded materially to a larger global sample across nearly 200 countries, pointing to broader reach and scale.

Tulip, the leader in frontline operations, is helping companies around the world equip their workforce with connected apps, leading to higher quality work, improved efficiency, and end-to-end traceability across operations. Companies of all sizes and across industries have implemented composable solutions with Tulip’s cloud-native, no-code platform to solve some of the most pressing challenges in operations: error-proofing processes and boosting...
Tulip's Top Stability & Growth Strengths
Strong Revenue Growth: Tulip reported 536% revenue growth over three years and cited its 2024 Deloitte Technology Fast 500 ranking as evidence of rapid top-line expansion. This momentum is further supported by disclosures of large increases in customer deployments and usage through 2025.
Investor Backing & Capital Strength: A $120M Series D announced in January 2026 at a stated $1.3B valuation, led by Mitsubishi Electric, is presented as funding further growth and expansion. Strategic investment alongside a commercial alliance signals durable capital access and support.
Market Expansion: Headcount reportedly grew 135% to 300+ with new offices opened in Singapore, Munich, Budapest, Tokyo, and Tel Aviv. The company also points to scale across 1,000 customer sites in 45 countries as of 2025.
Fusion Risk Management is recognized as the most innovative and fastest growing provider of cloud-based enterprise software for business continuity risk management, IT disaster recovery and crisis management. Fusion is transforming the industry and has been named a leader in Gartner's Magic Quadrant for Business Continuity Management software.
Fusion Risk Management's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A majority investment by Great Hill Partners in 2023, with Vista Equity Partners remaining a significant stakeholder, is described as funding to accelerate go-to-market, product innovation, and both organic and inorganic growth. This private-equity support positions the company to underwrite expansion initiatives.
Market Expansion: Appointing a leader to drive growth across EMEA and APAC in 2026 and adding a CRO (2025) and CMO (2026) to scale global revenue indicate widening geographic and go-to-market reach. Company communications highlight continued investment in international presence and partner ecosystems.
Product Line Growth: Announcements in 2025–2026 introduce new offerings such as AI-enabled capabilities, Recovery Optimization, and the Enterprise Resilience Decision System. This steady release cadence signals an expanding portfolio aligned to operational resilience use cases.
We believe insurance is about relationships. And technology should only make them stronger. We exist to empower independent agents, carriers, and MGAs. To drive their success. Because their success is our success. And their ambitions for tomorrow are our goals for today. Since our inception, we’ve been the technology backbone of the insurance industry. We began punching cards for independent agents over...
Vertafore's Top Stability & Growth Strengths
Resilient & Sustainable Growth: ARR is reported as growing across agency, MGA, and carrier businesses, with parent-segment commentary pointing to steady, mid‑single‑digit organic expansion. This pattern, alongside ongoing product launches and tuck‑in M&A, suggests durable momentum.
Strong Market Position & Advantage: The company reports serving the vast majority of top agencies and carriers and a base of more than 1.6 million insurance professionals. Such reach across its core markets underpins competitive advantage and long‑term stability.
Innovation-Driven Growth: New platforms and capabilities—such as the Velocity AI Platform, multiple AI agents, and the integrated Surefyre offering—extend functionality across AgencyOne, MGA, and Sircon. Continued workflow improvements like Project Impact increasing time savings indicate product‑led expansion.
.png)
Navan (Nasdaq: NAVN) is the leading all-in-one business travel, payments, and expense management platform that makes travel easy for frequent travelers. From finding flights and hotels to automating expense reconciliation, with 24/7 support along the way, Navan delivers an intuitive experience travelers love and finance teams rely on. See how Navan customers benefit and learn more at navan.com.
Navan's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is scaling at strong double-digit rates, reaching $702M in FY2026 and continuing to rise in subsequent quarters, with full‑year FY2027 guidance lifted into the low‑$900M range. Multiple updates indicate momentum in both reported results and outlook.
Healthy Cash Flow: Operating cash flow turned positive in FY2026 and free cash flow was also positive, alongside progress in non‑GAAP profitability in later quarters. These milestones suggest improving financial efficiency as scale increases.
Diversified Customer Base: The company reports 12,500+ active customers and continued wins with large enterprises across technology, manufacturing, and healthcare. This breadth points to demand resilience across multiple industries.
ePayPolicy offers easier payment tools, built just for insurance. ePayPolicy's products bring insurance payments up to speed for agencies, carriers, MGAs and PFCs, with secure online payment pages, automated check processing, accounting reconciliation and more. 11,000+ insurance companies trust ePayPolicy and their expert support team to handle their payments every day.

ePayPolicy's Top Stability & Growth Strengths
Strong Revenue Growth: Inc. 5000 placements across five consecutive years, including a recent cycle with triple-digit multi‑year growth, indicate sustained revenue expansion. Earlier cycles cited even higher multi‑year growth, reinforcing a pattern of continued momentum.
Market Expansion: Customer count reportedly advanced from roughly 7,000 organizations to 10,000+ in 2025 and 12,000+ in 2026. This trajectory points to broader adoption across agencies, MGAs, carriers, and premium finance companies.
Investor Backing & Capital Strength: A new investment from LLR Partners in August 2025, alongside existing backer Serent Capital, was framed to support the next stage of growth. This institutional backing signals capacity to fund product innovation and go‑to‑market expansion.

Together, we power advertising that enables billions of people to stay informed, entertained, and connected. We introduce them to new ideas, products, and services that make their lives better. And we help media owners of all sizes realize their full potential. That’s a lot — that’s the power of advertising. But it’s only possible with great technology. And that’s where Magnite...
Magnite's Top Stability & Growth Strengths
Profitability: Adjusted EBITDA and margins expanded, with Q2 2026 EBITDA up 30% year over year and margin improving to 37%, alongside higher net income. This pattern indicates operating leverage as earnings outpace the top line.
Strong Revenue Growth: Revenue rose 7% in 2025 and accelerated to 11% year over year in Q2 2026, with multiple sequential quarters showing improving trends. The recent trajectory points to faster growth rather than a flat profile.
Healthy Cash Flow: Free cash flow is guided to grow at more than 30% for 2026 and was later raised to the high-40% range, while Q2 2026 generated $57.4M in operating cash. Debt reduction in 1H 2026, including repayment of $205M in convertibles, further supports balance-sheet strength.
Cin7 connects your channels, inventory and accounting together. It dramatically reduces the cost of selling products across multiple channels, and opens up exciting new opportunities for product sellers. We're built on innovation, trust & collaboration, and a passion to see our customers thrive.
Cin7's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Significant new capital was secured via a $500 million single-asset continuation fund dedicated to support Cin7’s continued growth, including organic initiatives and acquisitions. This indicates strong sponsor commitment and liquidity to fund expansion.
Product Line Growth: The acquisition of AI forecasting firm Inventoro and the launch of Cin7 ForesightAI, along with added offerings like Cin7 Pay and Cin7 Capital, point to active expansion of capabilities and addressable market. These moves broaden the product portfolio beyond core inventory and order management.
Market Expansion: Cin7 reports 8,500+ customers across 100+ countries and 125+ million orders processed annually, with 1,500+ new customers added in 2024. These indicators suggest growing global reach and sustained operating scale.

Datadog (NASDAQ: DDOG) is a global SaaS business, delivering a rare combination of growth and profitability. We are on a mission to break down silos and solve complexity in the cloud age by enabling digital transformation, cloud migration, and infrastructure monitoring of our customers' entire technology stacks. Built by engineers, for engineers, Datadog is used by organizations of all sizes...

Datadog's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show accelerating top-line momentum, with FY2025 up 28% and Q2 2026 revenue up 36% year over year after 32% in Q1. Management also raised 2026 revenue guidance to $4.45B–$4.47B, indicating confidence in continued expansion.
Healthy Cash Flow: Cash generation is substantial, including Q2 2026 operating cash flow of $316M and free cash flow of $279M with about a 25% free-cash-flow margin. The company also reported roughly $5.0B in cash, cash equivalents and marketable securities as of June 30, 2026.
Customer Loyalty & Retention: Expansion within the installed base is a key driver, with about 75% of the 2025 revenue increase coming from existing customers and rising multi‑product adoption. Larger accounts are also expanding, as $100K+ ARR customers grew roughly 23% year over year to ~4,720 in Q2 2026.

SciPlay is a leading developer and publisher of digital games, providing entertaining free-to-play casual and social games to millions. Our data-driven approach, advanced game economy and high-quality content offer a thrilling experience. Our games are true to the authentic spirit of the world’s biggest casino brands and bring users hours of fun.

SciPlay's Top Stability & Growth Strengths
Profitability: AEBITDA increased year over year in 2025 and margins expanded, even as revenue softened. Feedback suggests this continued into late 2025 and early 2026 with additional AEBITDA gains.
Diversified Revenue Streams: The direct-to-consumer platform scaled rapidly, lifting its share from about 11% of revenue in 2024 to 19% in 2025 and roughly a quarter in Q4 2025. Feedback suggests this mix shift has supported margin improvement.
Strong Market Position & Advantage: The business is consistently characterized as a leading player in social casino, anchored by durable franchises such as Jackpot Party Casino, Quick Hit Slots, and 88 Fortunes. Feedback suggests industry recognition and share gains have reinforced this standing over recent years.
For over a decade, we built the infrastructure behind conversations, chat, voice, video, messaging APIs. We became the #1 CPaaS platform for in-app communications. 4,000+ brands trust us. 7 billion messages flow through our platform every month. 300 million monthly active users. We powered conversations for DoorDash, Match Group, Noom, Yahoo Sports, Rakuten, and thousands of others. We were good at...
Sendbird's Top Stability & Growth Strengths
Product Line Growth: Expansion from in‑app chat/voice/video APIs into business messaging and AI agents, with 2025–2026 launches such as Voice AI agents, Delight.ai, Trust OS, and multi‑agent capabilities, broadens the platform’s scope. Feedback suggests this move up the stack toward AI-powered customer experience increases addressable demand.
Innovation-Driven Growth: A rapid cadence of AI-first product updates and new integrations (email, SMS, WhatsApp, Salesforce, Freshworks) signals strong R&D momentum. Feedback suggests these enhancements are enabling more use cases beyond the original chat SDKs.
Strategic Partnerships: A multi‑year collaboration with AWS and marketplace availability strengthen distribution and enterprise credibility for newer AI offerings. Feedback suggests such partnerships can accelerate adoption across the thousands of applications already using the platform.

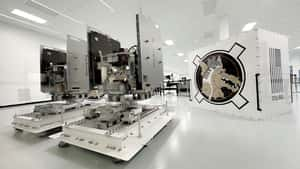
Space was once the quietest place in the universe. Now, it's crowded, contested, and confrontational. We are True Anomaly: the only defense company focused exclusively on space defense. Founded in 2022 by ex-U.S. Space Force members, True Anomaly designs and builds advanced systems for space superiority: agile and powerful spacecraft platforms, mission software engineered for unmatched command and control, and payloads...
True Anomaly's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised has accelerated from a $260M Series C in 2025 to a $650M Series D in 2026, pushing cumulative funding above $1B and indicating substantial financing capacity. Funding is described as enabling facility expansion, manufacturing scale-up, and a larger mission cadence.
Strong Hiring & Retention: Headcount expanded from a small founding team to ~250 by end-2025, with stated targets of 500+ in 2026 and 1,000+ in 2028 alongside multi-site growth in Colorado and Long Beach. Independent coverage during 2026 also points to 250–300+ employees, reinforcing tangible workforce scaling.
Strong Market Position & Advantage: Selection for multiple Space Force efforts—such as VICTUS HAZE operations, Kronos software, GHOST-R/RG-XX, and Space-Based Interceptors—signals movement from small R&D awards toward larger defense procurement. The company reports transition from development flights to operational missions, including a space-to-space pursuit during VICTUS HAZE.



